On Oct 14, 2026
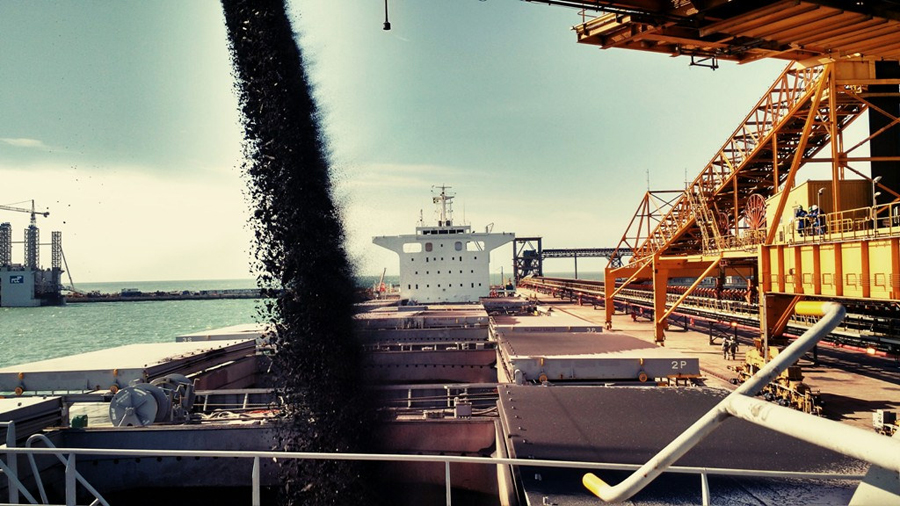
The Ore Wars: From Traditional Mining to the Strategic Battle for Critical Minerals
The global race for mineral resources has evolved into a major economic and geopolitical contest, reshaping trade relations, industrial policies and national security strategies between 2002 and 2026. From iron ore and copper to lithium, cobalt, nickel and rare earth elements, countries are increasingly competing to secure the raw materials essential for manufacturing, renewable energy, electric vehicles, defence equipment and advanced technologies.
Often described as the “Ore Wars,” this struggle reflects the growing importance of mineral supply chains in determining economic competitiveness and strategic influence. What began as a contest for traditional industrial commodities has expanded into a broader competition over critical minerals, processing capacity, mining technology and control of global supply networks.
2002–2008: China’s Industrial Boom Changes the Mining Landscape
The early 2000s marked a turning point in global mineral demand. China’s rapid industrialisation, infrastructure expansion and urbanisation drove a significant increase in demand for iron ore, copper, aluminium and other industrial commodities.
Mining companies expanded production, new projects attracted investment, and resource-rich countries gained greater bargaining power. Australia, Brazil and several African nations strengthened their positions as important suppliers of raw materials.
The period also exposed a fundamental weakness in global manufacturing: countries with limited domestic mineral resources increasingly depended on international supply chains. As demand grew, competition for long-term supply agreements, mining concessions and access to ports and railways intensified.
2008–2015: Commodity Volatility and Resource Nationalism
The global financial crisis of 2008 disrupted commodity markets, demonstrating how closely mining revenues were connected to international economic conditions. Although prices fell sharply during the crisis, demand recovered in subsequent years, particularly as major economies introduced stimulus measures and infrastructure investments.
Governments in mineral-rich countries increasingly sought greater economic benefits from their natural resources. Royalties, export restrictions, local processing requirements and revisions to mining contracts became important policy tools.
The debate shifted beyond extracting ore to determining who would capture the greatest value from it. Countries began reassessing whether exporting unprocessed minerals was sufficient to support long-term industrial development.
2016–2020: Electric Vehicles Bring Critical Minerals into Focus
The expansion of electric vehicles, battery manufacturing, wind power and solar energy changed the strategic importance of minerals. Lithium, cobalt, nickel, graphite and rare earth elements became increasingly important to emerging industries.
China developed a strong position across several mineral processing and manufacturing supply chains. Meanwhile, countries with significant reserves began exploring ways to attract investment in domestic refining, battery production and advanced manufacturing.
The United States, European countries, Japan and other industrial economies increasingly recognised that access to critical minerals could influence their energy transition and technological competitiveness.
The COVID-19 pandemic in 2020 further exposed vulnerabilities in international supply chains. Disruptions to transportation, mining operations and industrial production strengthened calls for diversified suppliers, strategic stockpiles and more resilient sourcing arrangements.
2021–2023: Supply Security Becomes a National Priority
As economies recovered from the pandemic, demand for energy-transition materials continued to attract investment. Governments introduced or expanded policies intended to strengthen domestic production, encourage recycling and reduce dependence on concentrated supply networks.
The United States introduced major clean-energy and manufacturing incentives, while the European Union advanced efforts to improve access to critical raw materials. Other countries pursued partnerships with resource-rich economies to secure supplies for their industrial sectors.
At the same time, the mineral market experienced considerable price volatility. Rapid changes in lithium and other battery-material prices highlighted the risks associated with investment cycles, uncertain demand forecasts and the pace of new mining projects.
The competition increasingly involved not only mineral reserves but also processing facilities, technical expertise, financing and access to advanced manufacturing capabilities.
2024–2026: The Strategic Battle Moves Beyond Mining
By the middle of the 2020s, the Ore Wars had become a contest over entire mineral value chains. Governments and companies increasingly focused on securing supplies of copper, lithium, nickel, graphite, cobalt and rare earth elements while reducing exposure to concentrated processing capacity.
Copper gained strategic importance because of its extensive use in electricity networks, renewable-energy installations, data centres and electrification. Lithium and graphite remained important to battery supply chains, while rare earth elements played essential roles in selected high-performance magnets, electronics and defence applications.
Export controls, investment screening, trade restrictions and strategic partnerships became increasingly important instruments of industrial policy. Countries also placed greater emphasis on recycling, alternative materials and technologies designed to reduce mineral intensity.
India, with its expanding manufacturing ambitions, renewable-energy investments and electric-mobility market, has strong incentives to diversify mineral sourcing, develop domestic processing capabilities and strengthen international partnerships. For other emerging economies, the challenge is to turn mineral wealth into jobs, infrastructure, technology transfer and higher-value industrial production.
The outcome of this period will depend not only on geological resources but also on how effectively countries develop infrastructure, attract responsible investment, manage environmental impacts and establish reliable trading relationships.
Why the Ore Wars Matter
The competition for minerals has consequences far beyond the mining industry.
Economic power: Access to reliable mineral supplies can influence manufacturing costs, industrial growth and national competitiveness.
Energy transition: Copper, lithium, graphite, nickel and other materials support different parts of clean-energy and electrification supply chains.
National security: Selected minerals are essential for defence systems, semiconductors, communications equipment and advanced manufacturing.
Trade and diplomacy: Mineral agreements increasingly shape relationships between resource-producing and industrial economies.
Environmental responsibility: Mining expansion raises questions about water use, land degradation, biodiversity, waste management and the rights of local communities.
Industrial development: Countries that invest in refining, recycling and manufacturing can capture more value than those that depend solely on exporting raw ore.
The Road Ahead: Who Will Control the Mineral Economy?
The next phase of the Ore Wars will be shaped by the balance between resource availability, technological innovation, environmental responsibility and geopolitical competition.
Countries with substantial reserves may enjoy an initial advantage, but geological wealth alone does not guarantee industrial leadership. Refining capacity, skilled workers, affordable energy, efficient logistics, access to capital and stable regulations will remain critical.
Recycling could also become a more important source of supply as batteries, electronics and renewable-energy equipment reach the end of their useful lives. New extraction techniques and alternative materials may reduce pressure on certain resources, although their commercial impact will vary by mineral and application.
For mining companies, the challenge will be to expand production while controlling costs and meeting increasingly demanding environmental and social expectations. For governments, the priority will be to balance resource sovereignty with investment, international cooperation and reliable trade.
Conclusion
From China’s industrial expansion in the early 2000s to the strategic mineral competition of 2026, the Ore Wars illustrate how natural resources have become central to global economic and political power. The contest is no longer simply about who possesses the richest deposits. It is about who can extract, process, transport, recycle and transform minerals into the technologies that will shape the future.
No comments:
Post a Comment