Wednesday, September 23, 2026

The Secret Houthi-U.S. Deal That Could Push Saudi Arabia Back to Beijing

  • The Houthis could further escalate Red Sea disruptions.

  • Washington has reportedly opened direct talks with the Houthis while declining Saudi requests for military intervention, potentially complicating Riyadh’s security relationship with the United States.

  • Growing Chinese influence around the Red Sea and Indian Ocean could ultimately encourage Riyadh to deepen its ties with Beijing.

Back at the start of the U.S.’s ‘Operation Epic Fury’, OilPrice.com predicted three courses of action that Iran would take as it moved through the conflict escalation gears. First, most obviously, although apparently not to President Donald Trump’s team, was to close the Strait of Hormuz to cause oil, liquefied natural gas (LNG) and refined products prices to soar -- check. Second, was to launch attacks on Saudi Arabian oil infrastructure via the Tehran-backed Yemeni Houthis to further inflate energy prices and undermine the idea that U.S. allies in the Middle East could rely on Washington to protect them from Iran -- check. Third, was the blockade of the Bab el-Mandeb Strait, the other critical regional transit route for the world’s oil, LNG and refined products, to ramp up both the higher energy price- and regional insecurity-pressure still further. This last element has not yet been fully activated, but it is not far off. So, where do Iran and its Houthi protagonists go from here?

Within the next few days, the Houthis are likely to ‘officially’ close off the Bab el-Mandeb Strait to all ‘enemy’ shipping rather than to just the Saudis, as has been the case, a very senior energy source who works closely with Iran’s Petroleum Ministry exclusively told OilPrice.com over the weekend. “That will mean Iran effectively holds hostage up to 42% of the world’s crude oil flows [the Strait of Hormuz roughly 30% of oil, and Bab el-Mandeb about 12%] historically flowed on a historical basis and up to 30% of its LNG flows [Strait of Hormuz roughly 20% and Bab el-Mandeb around 10%], and the figures for refined products are at least as disturbing,” he said. Indeed, before the current blockades, the Strait of Hormuz accounted for up to 5.5 million barrels per day (bpd) of fully refined petroleum products including diesel, jet fuel, and petrochemical feedstocks like naphtha that were already cracked at Middle Eastern mega-refineries before entering maritime transit lanes. Meanwhile, the Bab el-Mandeb Strait -- the key gateway into southern Europe from the Gulf of Aden through the Red Sea and then Suez Canal -- handled up to 2.6 million bpd. “The soaring prices of many of these refined products -- notably diesel and jet fuel -- are possibly even more serious than for oil and LNG because Europe shut down many of its own ageing refineries over the years, so it relies on importing pre-cracked, finished diesel and jet fuel directly coming from the Middle East through the Bab el-Mandeb Strait,” he added. The recent seizures by the Houthis of several key islands in the Red Sea -- including the centrally-positioned Perim Island in the mouth of the Strait between Yemen and Djibouti -- give the group and Iran far greater leverage over the Red Sea/Suez Canal transit route than they had before. In fact, International Monetary Fund (IMF) PortWatch data shows that overall shipping through the Bab el-Mandeb Strait has dropped nearly 90% below normal averages, even without the Houthis declaring a general blockade on it. “Using the Houthis on the Bab el-Mandeb has been a clever move from Tehran because it stretches already-stretched U.S. forces, and leaves Washington’s previous assurances that it would look after its allies in the region looking like hot air,” he highlighted.

Staggeringly for many observers -- not least, the Saudis -- came recent news that not only had the U.S. directly refused to help the country militarily against the latest Houthi, and by extension Iranian, threats but also that Washington was in direct contact with the Houthi leaders. Confirmed by OilPrice.com through Iranian and Washington sources with close knowledge of the matter, just over a week ago Trump refused to authorise direct U.S. air strikes to halt the Houthi advance along the Red Sea coast when asked to do so by Saudi Arabia’s Crown Prince Mohammed bin Salman (MbS) in two separate telephone calls on 10 September. This was the day the Houthis completed their capture of the strategic port city of Mokha and were pushing quickly across several Red Coast targets. Trump instead sent CENTCOM Commander Admiral Brad Cooper to Riyadh for emergency intelligence-sharing coordination and has still not authorised any military assistance for the Saudis. Given Trump’s legendary long memory when it comes to grudges, perhaps the refusal was partly because MbS had persistently refused to take the telephone calls from former U.S. President Joe Biden in March 2022, when Washington desperately needed help from the Saudis to help bring spiralling oil prices down after Russia’s invasion of Ukraine, as analysed in full in my latest book. Perhaps it was due to ‘assurances’ from the Houthis that they would not attack U.S. vessels in the Bab el-Mandeb Strait. Such assurances were reiterated during the direct U.S.–Houthi negotiations that took place at the U.S. Embassy in Muscat, Oman, mediated by the Omani government, over the weekend of 12–13 September 2026, with the specific face-to-face session occurring on 13 September. “Up until then, the Saudis still thought the U.S. had its back,” a senior source who works closely with the European Union’s (E.U.) security complex exclusively told OilPrice.com last week. “After that, it [Saudi Arabia] knows it’s on its own now,” he added.

Widening the current military campaign against Saudi Arabia is certainly another of the next steps the Houthis will take, if it gets the chance, according to the Iranian source. This may come sooner rather than later, given Saudi plans -- discussed again over the weekend -- to form a standalone 14-country task force called the Multinational Maritime Defense Coalition (MMDC), which will also include elements of the recently formed Mecca Joint Defence Agreement (MJDA) framework analysed by OilPrice.com. The MMDC comprises MJDA countries (Saudi Arabia, Pakistan and Turkey), Egypt, Kuwait, Bahrain, Qatar, Jordan, Yemen (the anti-Houthi Presidential Leadership Council), Djibouti, Somalia, Sudan, Bangladesh, and Nigeria. The inclusion here of Djibouti may not be helpful to the Saudis because -- as also examined in my latest book on the new global oil market order -- Iran’s main superpower backer, China, has a vice-like grip over the country due to predatory loans connected to its ‘Belt and Road Initiative’ multi-generational power-grab project. In fact, following Chinese investment of around US$14 billion in the country (totalling over 70% of Djibouti’s debt, and making it the country’s biggest debtor), Beijing in 2017 created its first overseas military base there. Given that Chinese vessels remain largely unaffected on the orders of Iran from the current blockades on the Strait of Hormuz or the Bab el-Mandeb Strait, it appears that Djibouti’s involvement in the MMDC will just be part of a balancing act geared toward protecting Chinese economic self-interest, rather than a genuine geopolitical desire to undermine Iran’s strategic goals. Consequently, anything China does in this ‘alliance’ is likely to be confined to quietly pressuring Tehran to tell the Houthis to keep the disruptions selective.

Worse still for Saudi Arabia’s plans to quell the Houthis threat is that Beijing’s highly integrated BRI-related economic and logistics corridor runs all the way from the Horn of Africa to the wider western Indian Ocean, and into another of Riyadh’s ‘partners’ in the MJDA -- Pakistan. Djibouti is not just home to a massive Chinese military base but also acts as the maritime centre for Ethiopia, with Beijing owning the US$4 billion Addis Ababa–Djibouti Railway essential for Ethiopia’s exports. To the south of Ethiopia is Kenya, which China has established as its primary commercial maritime gateway into the African continent through the building of the Mombasa Port Expansion project and the Lamu Deep-Water Port.  And northeast of Djibouti across the Arabian Sea is the crown jewel in China’s maritime choke point strategy -- Pakistan’s Gwadar Port. As thoroughly detailed in my latest book, Gwadar is directly tied to the China-Pakistan Economic Corridor, officially a commercial deep-water port operated by China Overseas Ports Holding Company, but it is heavily constructed to act as a dual-use facility capable of resupplying, repairing, and docking the People’s Liberation Army Navy’s capital ships. Moreover, in each of these areas there is also ample opportunity for the Houthis to hook up with fellow like-minded Islamic extremist terrorists too, thus creating a force multiplier effect across the region. Aside from the Tehrik-e-Taliban Pakistan operating widely across that country, Al-Qaeda-affiliated extremist group Al-Shabaab is based in Somalia with a very broad reach into Djibouti, Ethiopia, Kenya, and Sudan. Looking at all of these factors, and given the strong relationship that had built up between Saudi Arabia and China in the years following the end of the 2014-2016 Oil Price War, it may well be that the key victory for the Houthis to come will be a switch back in Riyadh’s primary geopolitical alliance to China, and away from the U.S

By Simon Watkins for Oilprice.com

 HE DISAGREES WITH THE BOSS

U.S. Energy Secretary: Blunt Tool of Banning Diesel Exports Doesn't Work

US Energy Secretary Chris Wright has publicly opposed calls for a ban on US diesel exports, arguing on Wednesday that the measure would backfire by increasing gasoline and jet fuel prices.

"The blunt tool of banning diesel exports definitely doesn't ‌work," Wright said at an event in New York, as reported by Reuters.

Wright said restricting exports would leave refiners with excess diesel inventories, forcing them to cut refinery output.

Lower refinery runs, he warned, would tighten supplies of other fuels, ultimately driving up costs for consumers and businesses.

His comments put him at odds with President Trump, who signaled support for the idea on Tuesday as diesel prices surge to record highs in the US and Europe (and Treasury Secretary Bessent has been assigned to see "if it's feasible."

Trump's comments already sent European prices for the fuel surging.

With flows from the region’s top supplier at risk, Bloomberg reports that European diesel’s premium to Brent crude jumped to more than $95 a barrel on Wednesday, a record in Bloomberg data going back to 2011.

Known as the crack spread, the indicator has been keenly watched by central bankers as they seek to tame inflation. The equivalent measure in the US, meanwhile, weakened.

Trump’s threat comes as Europe is already grappling with the loss of diesel shipments from the Middle East, and Russian export curbs have tightened the global fuel market further. The US has become Europe’s main overseas supplier, with American exports of the workhorse fuel surging to a weekly record near 2 million barrels a day last month.

A key US oil industry group cautioned against the move, saying it could lower American fuel production and damage the global economy.

Of the 8 million barrels of diesel traded globally by sea each day, the U.S. supplies about 1.5 million of them - about 20%. An export ban would remove the single largest source of global diesel from the market, and the consequences could be catastrophic.

“Restricting exports is not a solution to high prices,” the American Petroleum Institute says.

“Removing US diesel from the market could instead result in reduced refinery runs, global economic damage and even higher US prices.”

Indeed, as Bloomberg macro strategist Michael Ball wrote this morning, while the White House may be able to engineer a brief drop in US diesel prices by limiting exports, it risks creating a bigger supply problem down the road.

With distillate stocks at seasonally record lows...

...the appeal is obvious with US diesel above $6.50 a gallon...

But a broad curb could strand as much as 1.5 million barrels a day, roughly 29% of US diesel output.

If enacted, Ball writes, the effects would be uneven across the US.

A surplus would build on the Gulf Coast, while pipeline, shipping and fuel-specification constraints limit how easily those barrels can reach tighter East and West Coast markets.

Bloomberg Intelligence estimates Gulf Coast storage could only absorb about three weeks of net diesel exports before constraints bite.

The global impact would be worse.

Kpler argues there is no real replacement for US export volumes, leaving Latin America and Northwest Europe particularly exposed and increasing competition for Indian barrels.

China could compound the squeeze as domestic inventories fall and the risk of renewed export curbs rises.

The response from refiners would create a negative feedback loop.

If trapped barrels crush margins, refiners are incentivized to cut runs and undertake maintenance.

S&P Global Energy estimates crude runs might need to fall by nearly 2 million barrels a day - more than 10% of the current production level - to clear the surplus.

That is the asymmetry: lower US diesel prices first, tighter global product markets follow, and potentially less US fuel supply later.

The more aggressive the restriction, the greater the risk that today’s price relief becomes tomorrow’s supply problem.

By Zerohedge.com


Global Refinery Crunch Pushes Diesel Prices to New Records

  • U.S. diesel prices have surged above $6.50 per gallon, as lost Middle Eastern and Russian fuel supplies collide with limited global refining capacity.

  • Washington is debating a diesel export ban to ease domestic prices, but opponents warn it could worsen the global shortage and potentially trigger similar restrictions elsewhere.

  • Europe is particularly vulnerable, having closed significant refining capacity while becoming increasingly dependent on imported crude and refined fuels from the Middle East and other regions.

U.S. diesel prices broke another record last week, topping $6.50 per gallon. In Europe, fuel prices are soaring, and shortages are looming over already struggling economies. There is simply not enough refining capacity in the world to make up for the loss of Middle Eastern and Russian barrels. And there is no quick fix.

Last week, Russia said it would extend a ban on diesel exports until the end of October, as Ukrainian drone attacks on refineries continued, despite President Donald Trump’s call on the Zelensky government to stop attacking energy infrastructure, blaming the diesel price surge solely on those attacks. The latest attack came on Sunday, targeting one of Russia’s largest refineries.

However, the loss of fuel supply from the Middle East is much larger, the Wall Street Journal reported last week, citing figures from the International Energy Agency showing the amount of diesel output lost in the Middle East was three times as high as lost Russian supply.

Now, there are calls in Congress for a U.S. ban on diesel exports. Rep. Tim Burchett tabled a bill to that effect last week, and Senate Majority Leader John Thune has backed the proposal. Energy Secretary Chris Wright and Interior Secretary Doug Burgum oppose it as a bad idea that would ultimately backfire, but the very fact that some legislators considered an export ban suggests the supply situation is pretty grim even for the world’s largest oil producer.

Diesel prices underpin the price of pretty much everything else. When they rise, other prices follow, notably food prices, to which people are particularly sensitive. This is of particular concern in Washington ahead of the midterm elections in November, hence the idea of an export ban. A ban could bring down prices at home, but it would push prices even higher elsewhere, aggravating an already quite grave fuel supply crisis. It is a crisis that no one could have foreseen, but also one that might have arguably been less grave had there been more refining capacity in the world.

The fact is that over the past decade or so, a lot of refineries have been shut down under pressure from the net-zero movement that has come to dominate energy policies, mainly in Europe, but also in the U.S. under Democratic administrations. Refining had become a losing game for many, so they either shut down or converted their capacity to biofuels.

“We’ve seen the oil majors effectively reduce their exposure to that sector because the returns on actual capital employed have been poor,” Wood Mackenzie senior VP for refining, chemicals, and oil markets Alan Gelder told the Wall Street Journal. “The classic phrase we used was: ‘How do you make a small fortune? Take a large fortune and build a refinery.’”

While refineries closed in Europe and the United States, however, Middle Eastern petrostates built new ones, coming to account for a bigger portion of global refining capacity. Profit, per the experts cited by the WSJ, was not the primary motivation. Employment and domestic fuel supply security were. Now, that capacity has been compromised – and some of it has been damaged by Iranian strikes on Gulf energy infrastructure – and there is no one to pick up the slack, with U.S. refiners already operating at rates as high as they can.

To add insult to injury, there is one refinery in Europe sitting idle because it is the property of Russia’s Lukoil, which the Trump administration sanctioned last November, prompting the company to put its international business up for sale. According to a recent report by the Financial Times, a deal between Lukoil and Carlyle Group for the latter’s acquisition of the business had become “bogged down in an inter-agency process involving the National Security Council, State Department and Department of Energy,” leaving urgently needed refining capacity offline.

“There is significant underutilised refining capacity across Lukoil’s European assets that could help bring additional refined-product supply to market and ease pressure on fuel prices,” Carlyle said, as quoted by the FT, referring probably to the Romanian Petrotel refinery, which has been idled since the U.S. sanctions went into effect. Lukoil’s Bulgarian facility is operating. Petrotel has a capacity of about 50,000 barrels daily. This is not a huge amount of fuel, but in the current crisis, every barrel matters.

There is no solution to the world’s fuel problem in sight. Tanker traffic via the Strait of Hormuz remains severely depressed, Ukrainian drone attacks on Russian refineries continue, and if the U.S. bans diesel exports, according to the WSJ, China and India may follow its example, plunging the rest of the world into hitherto unseen levels of fuel shortages. The biggest loser of the situation, it appears, will be Europe, due to its heavy dependence on energy imports in both crude oil and refined products, and its shrinking refining capacity.

By Irina Slav for Oilprice.com


Hormuz Supply Crisis to Change LNG Market Forever

  • The Hormuz crisis has effectively made around 20% of global LNG supply “interruptible,” pushing buyers to prioritize security and geographic diversification.

  • Europe and Asia are seeking LNG beyond the Gulf, boosting interest in projects in Canada, Mozambique, Indonesia, Papua New Guinea and Argentina.

  • The crisis is reshaping energy strategies beyond LNG, with importers diversifying fuels, routes and contracts while countries such as Thailand accelerate renewables to reduce gas dependence.

The Strait of Hormuz crisis has turned roughly 20% of global LNG supply into something buyers now have to treat as interruptible.

Nearly seven months after traffic through the strait collapsed, LNG exports from Qatar and the UAE remain severely constrained. Buyers in Europe and Asia are responding by looking for supply that does not depend on Hormuz at all—from Canada, Mozambique, Indonesia, Papua New Guinea and Argentina—and reconsidering how much of their future gas demand they are willing to tie to a single export route.

The war has changed the near-term outlook and sent LNG prices in Asia and Europe soaring to the highs last seen in the 2022 crisis. Europe is hard-pressed for supply ahead of winter, while price-sensitive buyers in Asia are scrambling for alternatives, burning more coal, and boosting renewable energy generation targets to avoid supply crunches and hefty gas import bills when the next crisis hits the energy market.

Diversification Drive

The current crisis goes well beyond the concerns about winter supply in Europe or how high prices in Asia destroy demand. The war and the Strait of Hormuz supply crunch have undermined the decade-old belief among buyers that relying on cheap fixed-term supply from one or two sources is enough.Related: Saudi Arabia Restarts East-West Oil Pipeline

“The market seems now to be viewing the 20% of global supply behind the straits as ‘interruptible’ – even if it does return, it could easily be constrained again, feeding market volatility and further complicating contracting decisions,” Wood Mackenzie analysts said about their conversations with LNG leaders at the Gastech 2026 conference in Bangkok earlier this month.

“An important consequence is that the value of more reliable supply has increased,” WoodMac’s analysts say.

Following the halt to LNG shipments from the Strait of Hormuz for months, buyers have started to think about energy security more than anything else and are busy diversifying their sources of supply.

European buyers started exploring purchases from Canada after it became clear in April that U.S.-Iran ceasefires aren’t bringing back Qatar’s supply to the market.

China’s giant state LNG importers are reportedly in talks to secure long-term LNG supplies from exporters that don’t need the Strait of Hormuz, as the world’s biggest LNG buyer seeks to reduce its exposure to gas deliveries from the Persian Gulf.

China is the top LNG customer of Qatar, and it sourced nearly 30% of its LNG supply from the Gulf exporter last year.

Some of China’s state-controlled majors have signed long-term deals in recent years with Qatar in exchange for minority stakes in some of the expansion projects of the Gulf producer, part of which will be delayed due to the war.

But Beijing is exploring options to reduce its exposure to Gulf supply. Some of the biggest Chinese LNG buyers, including PetroChina and Sinopec, are in talks with exporters for potential deliveries starting before 2030 for a period of at least ten years, sources familiar with the plans told Bloomberg in July.

The global drive among buyers to secure LNG supply that’s not threatened by geopolitically charged chokepoints is strengthening the case for LNG projects in Mozambique, Timor-Leste, Indonesia, Papua New Guinea, Argentina, and Canada to move forward.

“Buyers, governments and export credit agencies are increasingly supportive of this supply diversification as they push for energy security, though the set of risks these projects carry remains an obstacle for some,” WoodMac said.

Priorities Realigned

But energy importers are diversifying not only their source of supply. They will be increasingly looking to diversify “among fuels, energies, delivery entry points, shipping access, technologies, and contract and price structures,” Leslie Palti-Guzman, a senior associate (non-resident) with the Energy Security and Climate Change Program at the Washington-based Center for Strategic and International Studies, said last month.

The Western Hemisphere, especially the West Coast of North America, is gaining prominence as a new source of LNG supply in stable jurisdictions such as Canada and Mexico, according to Palti-Guzman. Such supply has direct access to Asia without the need to use any of the chokepoints: the Strait of Hormuz, the Panama Canal, the Suez Canal, or the Straits of Malacca.

Qatar’s LNG supply will recover eventually and could position the Gulf state as a winner in the long term. However, the recovery and the faith buyers will have in continued access to the Qatari supply will depend on uninterrupted navigability of the Strait of Hormuz and Qatar’s relationship with Iran, Palti-Guzman said.

Buyers nevertheless are now open to exploring LNG supply that’s not coming from Qatar and the U.S., to diversify energy sources and hedge against the risk of depending on a limited number of supply options.

Some LNG importers in Southeast Asia, which have relied on Qatar for too much for too long, have moved to accelerate their renewable energy buildout to boost the share of solar power in their electricity mix and reduce dependence on gas imports.

Thailand, for example, is launching a public solar power scheme of 10 gigawatts (GW) that would cover about 1 million households. The rooftop solar panels are expected to reduce Thailand’s massive reliance on gas for electricity generation.

Thailand needs to diversify its energy sources “because otherwise we’ll be subjected to what’s happening in the Middle East forever,” Energy Minister Akanat Promphan said in comments to the solar scheme, as carried by the Financial Times.

By Tsvetana Paraskova for Oilprice.com

Imperial Oil Becomes First Major Alberta Energy Company to Oppose Separatism


Imperial Oil chief executive John Whelan has stated his opposition to Alberta separatism, making this the first major energy company in the province to take a public position on the movement, Financial Post reported, citing Bloomberg. 

"As a national company, we believe a united Canada is the strongest position we can take to face the challenges and opportunities ahead," Whelan told a Calgary conference, adding that "Canada and Alberta work best when people, products, energy and investment can move freely and reliably across the country." 

On October 19, Alberta will vote on whether to authorize the provincial government to pursue a binding independence referendum, which would be in the form of a procedural question, not a direct vote to separate.

A government-commissioned study from the University of Calgary School of Public Policy models two different potential outcomes. In the first, a smooth transition costs Alberta's GDP an estimated 2.2% in the short term, but leaves it 3.4% higher over the long term compared to staying in Canada. The second scenario spells out a difficult transition that costs 10.1% in the short term and 16.2% over the long term. The province's own cost estimate for the first five years runs $50 billion to $170 billion, with $40 billion to $55 billion of that in start-up costs alone.

Other Alberta energy executives have not jumped on board. Cenovus Energy chief executive Jon McKenzie said earlier this year that separatist sentiment is rooted in genuine grievances and would subside if addressed. ATCO chief executive Nancy Southern called the separatist discussion "very unhelpful”.

Whelan also lent his support to Premier Danielle Smith's production goals, saying Imperial "has the potential to double our gross operated upstream production while also advancing additional downstream biofuel production" under a supportive fiscal and regulatory framework. Imperial, a unit of Exxon Mobil, operates the Kearl oil sands mine, the Cold Lake in-situ site, and refineries in Alberta and Ontario.

Alberta's separatist movement gained momentum after a meeting between separatist organizers and Donald Trump, and the province has pushed ahead with the referendum despite a court challenge to its legality. Recent polling shows most Albertans oppose separation.

By Charles Kennedy for Oilprice.com


Jefferies-linked fund suing Radiant World says it may only hold $10,000 in cash


Stock image.

The iron ore trader Radiant World may hold only $10,000 in cash, even though its most recent financial statements refer to cash balances of more than $200 million, lawyers for a Jefferies-linked fund suing Radiant over an alleged fraud said on Thursday.

LAM Trade Finance Group II, in which US bank Jefferies holds a minority stake, obtained a freezing order last month from London’s High Court against Radiant World and its founder Pinkesh Nahar as well as Sapphire Minmetals, which used to be part of the company.

Singapore’s police force last month said it was investigating Radiant World after reports that invoices provided to its banks may not have been valid.

Radiant World, which has denied the allegations, did not reply to a request for comment on Thursday. Sapphire Minmetals did not respond to a request for comment.

LAM Trade Finance Group II, which has also obtained freezing orders in Hong Kong and Singapore, says it purchased iron ore receivables from companies linked to Radiant and/or Sapphire, by which it bought the right to be paid by traders such as Glencore and Vitol.

But those receivables either did not exist or were not validly assigned, it said in its claim against Radiant World.

“It appears that the defendants used debit notes to paper over the cracks, as it is put by the claimant, for as long as they could and it is characterised that ‘the well has now run dry’,” Judge Simon Bryan said when he made the freezing order.

In trading, receivables are amounts of money that a company is owed by its customers for goods that have already been delivered but not yet paid for.

Nahar said in a document submitted by his lawyers for Thursday’s hearing that it was not clear precisely what role he was alleged to have played.

Nahar has indicated his intention to challenge the court’s jurisdiction, said the document, which described the case as “a substantial, complex, $500 million international fraud claim”.

At Thursday’s hearing, lawyers representing LAM Trade Finance Group II argued in court documents that the freezing order should remain in place because of the risk that the defendants would dissipate assets.

They said asset totals provided in a witness statement on behalf of Radiant World were “substantially different” from those in financial statements for the year to September 30, 2025.

“The audited financial statements refer to cash balances of over $200 million whereas (the statement) says that Radiant World holds only $10,000 in cash,” they said.

Radiant World is embroiled in other lawsuits. It has sued Glencore (LON: GLEN) in Singapore seeking more than $2 billion.

Judge Andrew Henshaw said on Thursday that the next London hearing was likely to take place in late December.

(Reporting by Polina Devitt; writing by Sam Tobin; Editing by Louise Heavens)

KCM signs $498 million deal with Chinese firm for copper recovery plant


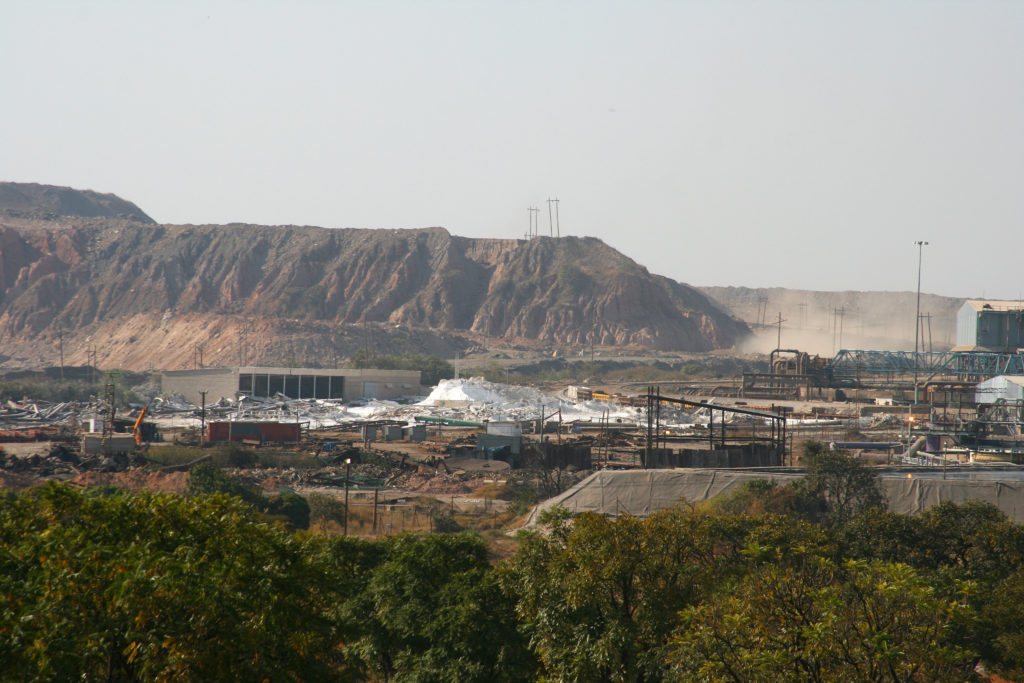
Nchanga mine in Chingola, in the Copperbelt Province of Zambia. (Image courtesy of Wikimedia Commons)

Vedanta’s (NSE: VDAN) Konkola Copper Mines (KCM) has signed a $498 million deal with China’s NERIN Engineering (SHA: 603257) to build a copper recovery plant that will add 70,000 metric tons of annual output by extracting metal from existing mine tailings.

The facility, to be built at KCM’s operations in Chingola, a town in Zambia’s copperbelt, will use leaching technology to process the mine waste and is expected to be the largest plant of its kind in Africa, the company said in a statement on Thursday.

The investment forms part of KCM’s expansion plans and Zambia’s ambition to raise annual copper output to 3 million metric tons by 2031 from 890,346 metric tons in 2025.

Under the agreement, China NERIN will provide engineering, procurement and construction services, along with support for commissioning, performance testing and training, KCM said.

Demand for copper, a key metal used in power grids, renewable energy infrastructure, data centres and electric vehicles, is expected to rise as countries pursue energy-transition goals.

Zambia is Africa’s second-largest copper producer after the Democratic Republic of Congo, whose exports of the red metal fell almost 15% in the first quarter.

(Reporting by Chris Mfula;Writing by Sfundo Parakozov;Editing by Joe Bavier)

Constellium may drop EU metal recycling plans due to scrap squeeze, CEO says


Credit: Constellium

Aluminium products maker Constellium may drop plans to expand recycling in the European Union unless policymakers resolve a scrap shortfall linked to used metal being exported overseas, its CEO said on Tuesday.

The European Commission angered industry representatives this month by abandoning plans to impose an export duty on aluminium scrap, which the industry says is crucial to keeping more of the low-cost raw material in Europe. The EU’s executive is now proposing to curb scrap outflows through waste shipment rules.

Constellium, like other producers in Europe, is sceptical about the waste approach given a large number of non-OECD countries seeking exemptions, CEO Ingrid Joerg told Reuters.

“We have several recycling projects in the pipeline that we are investigating. But if there’s no scrap, they’re not going to happen,” she said.

The projects covered Constellium’s different market segments, such as packaging, auto and aerospace, and could be larger or smaller than a previous €130 million ($148.82 million) recycling expansion at its Neuf-Brisach plant in France, she said, declining further details.

Constellium recycles some of its production in a closed loop but also relies on external scrap.

The loss of scrap to exports is among grievances of an EU aluminium sector also grappling with the bloc’s carbon border-tax scheme and soaring energy prices.

Constellium welcomed changes to the carbon border levy voted by the European Parliament last week, but final adoption was needed swiftly to close loopholes, Joerg said.

The border levy is expected to push up European aluminium premiums, adding to global inflation pressures linked to energy costs, tariffs and Mideast disruption, she said.

Constellium’s US operations were benefiting overall from tariffs, with a high recycling rate and US retention of scrap offsetting the impact of tariffs on Canadian aluminium, she added.

($1 = 0.8735 euros)

(Reporting by Gus Trompiz; Additional reporting by Kate Abnett; Editing by Susan Fenton)


EU waste proposal would ban India from importing bloc’s metal scrap


Aluminum and ferrous materials scrap ready for recycling. Stock image.

India will be among the countries barred from importing EU metal waste, including aluminium scrap, under a new law due to take effect in May 2027, according to a European Commission proposal setting out exemptions for non-OECD countries.

The Commission published the proposal on Friday, confirming an earlier Reuters report, and opened a public consultation on the exemptions list until October 16.

The move comes after the Commission earlier this month ditched a plan to impose a 15% export duty on aluminium scrap following pressure from the biggest buyer — India. Disagreements among EU officials diluted the trade proposal by exempting India, significantly reducing its impact.

The Commission has argued that the same objective can be achieved through the bloc’s waste shipment rules rather than trade measures.

Industry group European Aluminium remains unconvinced, however, having viewed the proposed export duty as crucial to keeping more of the low-cost raw material within Europe for struggling smelters.

The Waste Shipment Regulation will take effect in May 2027. The Commission said 32 non-OECD countries applied for exemptions covering non-hazardous waste categories including paper, plastics, rubber, metal and glass. Exemptions are granted only if applicants can demonstrate the waste will be treated in an “environmentally sound manner”.

Metal waste faces stricter scrutiny because it presents a “higher hazard profile … due to the potential presence of persistent and toxic heavy metals,” the Commission said.

The EU executive added that the exemptions list, known as a delegated act, will be updated regularly, at least every two years, and countries will be able to reapply.

(Reporting by Julia Payne. Editing by Mark Potter)