Showing posts sorted by date for query Huawei. Sort by relevance Show all posts

Tuesday, October 20, 2026


Trumpism and Latin America’s new right governments
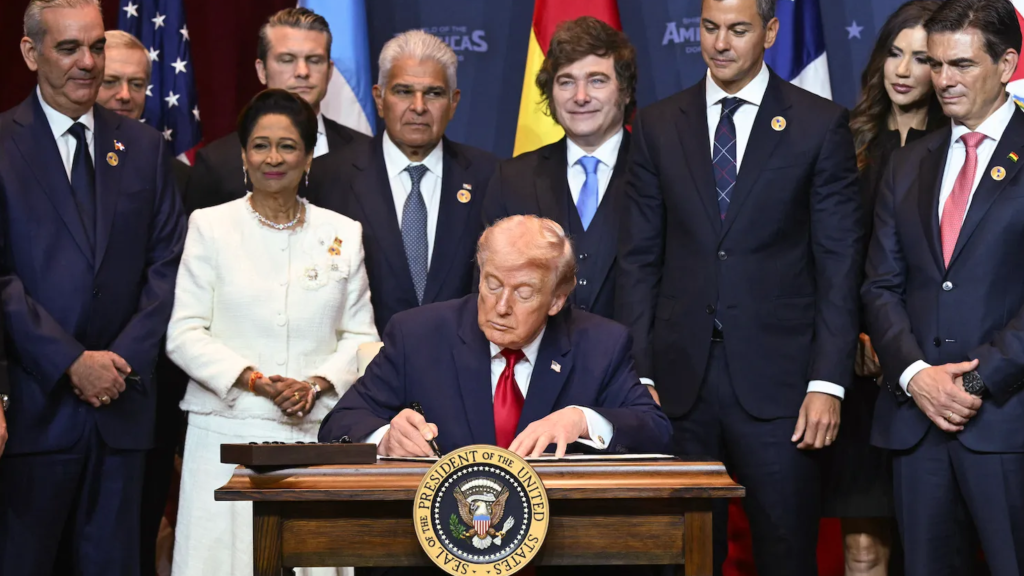
Trump Shield of the Americas

First published in Spanish at Viento Sur. Translation by International Viewpoint.

Perhaps paraphrasing Marx and Engels in the Communist Manifesto, when they described the revolutionary process that swept through Europe at the end of the 1940s as a spectre, we could describe the counter-revolutionary cycle that is sweeping through Our America in these 2020s as a spectre, albeit of the opposite kind.

This is a cycle that began tentatively with the electoral victories of Jair Bolsonaro and Nayib Bukele in Brazil and El Salvador in 2019, continued with the governments of Santiago Peña, Javier Milei, and Daniel Noboa in Paraguay, Argentina, and Ecuador in 2023, and then began to accelerate with the victories of Rodrigo Paz in Bolivia in 2025, José Antonio Kast, Nasry Asfurade (elected in 2025 but taking office in 2026), and Laura Fernández Delgado in Chile, Honduras, and Costa Rica. Meanwhile, Abelardo de la Espriella and Keiko Fujimori in Colombia and Peru won their respective elections in 2026 and were awaiting the inauguration of their respective countries at the time of writing.

If we consider the period from 2023 to 2026, far-right victories were seen in 13 of the 16 presidential elections held during that time. But it is since Donald Trump assumed the presidency of the United States 18 months ago that this political shift has intensified, with far-right candidates winning the last seven presidential elections in the region.

Simultaneity of processes

It is a politically novel phenomenon, both because of its simultaneity and coincidence, and because of the depth of the regressive reforms and structural changes it proposes. Furthermore, it does not appear to be a random or merely episodic event. In any case, its effects will be long-lasting.

A political shift has occurred. The “orange wave,” as The Economist dubbed it (referring to the US president’s skin tone), is dominant, embodied by a group of leaders who have attained political power in their countries through liberal democracy, capitalizing on popular frustrations with previous periods and governments. In a way, they are a product of the social decay imposed by decades of neoliberalism (concentration of wealth, expansion of poverty, uncertainty, and a lack of future prospects), which have instilled in the world the idea that there is no way out. However, the capitalist crisis that has been unfolding since 2008, which remains unresolved, cannot be ignored. In Latin America, this crisis has taken the form of an organic crisis characterized by high social and environmental vulnerability.

These governments, despite their differences and heterogeneity, have adopted the style, rhetoric, and agenda of Trumpism (authoritarianism, racism, sexism, homophobia, anti-environmentalism, the reconstruction of patriarchy, and the use of hate as a political tool). They have found that simple and direct messages on social media are a very effective way to connect with voters.

With Venezuela transformed by imperialist military aggression into a kind of US protectorate, and with Cuba blockaded and threatened with invasion, for now only Brazil, led by Lula, who is seeking reelection, and Mexico — the region’s two largest economies, together representing almost 70% of the regional GDP — are resisting this wave. Uruguay is also resisting to the extent possible.

In this context, the upcoming presidential elections in Brazil take on a decisive character. If the far right and Bolsonaro’s movement were to triumph, the consequences would be significant. Should the PT regain political power, the region will present an unprecedented and difficult-to-predict political landscape. Conversely, if the PT manages to win the elections, the country’s size could put a powerful brake on the current wave sweeping the region.

A turning point

It would be a mistake to interpret this rightward shift in the governments of Our America as a new phase in the alternation between right-wing and progressive governments, as a new turn resulting from frustrations, adaptations of progressive movements, and a return to traditional conservatism, or as an electoral wave in which all the opposition parties win. This surge of the extreme right can be seen as a response to the so-called leftward turn of the progressive- neo-developmentalist governments of the first 15 years of this century; however, it is a true turning point.

Those experiences altered the balance of social power but failed to change the pattern of accumulation and the subordinate integration into the global market, nor did they distribute wealth. Thus, predatory extractivism and the primary sector grew, while manufacturing declined.

US destabilization maneuvers, attempts at re-election, corruption, or demobilizing practices, the multi-class consensus that allowed them to achieve a degree of hegemony broke down, and governments ended up relying on clientelism and electoralism to guarantee governability. They have ultimately made it clear that progressivism, by failing to envision a horizon of overcoming capitalism and remaining solely focused on reforms — with varying degrees of intensity — and adopting a conservative stance regarding the autonomy of the masses, found its own limitations there.

The following period saw a return of traditional conservative right-wing politics (the Macri, Bolsonaro, Piñera, and Añez governments in Argentina, Brazil, Chile, and Bolivia) and then a tepid attempt at low-intensity progressivism (the Boric, Fernández, and Arce governments in Chile, Argentina, and Bolivia), to name just the Southern Cone of Latin America. These attempts were short-lived and resulted in significant frustrations. Building on these frustrations, whether neoliberal or neo-developmentalist, the extreme right has been gaining ideological and electoral ground, a process in which the crisis of political representation, attacks on journalism, disinformation, and the half-truths or outright lies circulating on social media have played a decisive role.

These new right-wing movements are far more radical, far more profound in the structural changes they promise, and far more aggressive in dismantling the democratic consensus achieved in the previous period. They promote the broadest deregulation of capital flows, the curtailment, if not the elimination, of social and political rights, the lack of protection for workers, women, peasants, Indigenous peoples, common goods, and nature, the dismantling of education and healthcare policies, the expropriation of Indigenous peoples and their identities, and the use of public debt to justify permanent austerity policies. It is a full-scale attack against the working class and in favor of capital, seeking to establish a long-lasting, regressive balance of power.

Much more market-intensive. An extreme neoliberalism that defines the market as the best allocator of resources and as the measure of all values, that emphasizes modernizing repressive forces and increasing military spending in each country. They are thus a turning point, a watershed moment with respect to the entire preceding period.

In Argentina, the Milei government, completely subservient to the US, is at the forefront of this process, with an ultraliberal experiment in the regressive reconfiguration of the productive matrix and society. It aspires to lead a group of countries identified with Trumpist policies in the context of the China- US dispute. The current diplomatic crisis with Brazil is an expression of this global conflict. Within this framework, the Argentine government is preparing a meeting of leaders from these far-right groups for the end of the year, dubbed the Blue Summit, seeking to consolidate ties and position President Milei as the regional leader. Of course, much depends on the results of the upcoming elections in Brazil and the US, which could influence the region and particularly the presidential elections next year in Argentina.

Associated with Trumpism

The region is entering a new period of militarization with the integration of the Shield of the Americas. This multinational political-military coalition, proposed by the US, comprises 12 countries that have pledged to combat drug cartels and terrorism militarily within their respective nations. It serves as a smokescreen to justify US troop intervention in the region. In mid-July, US Secretary of State Marco Rubio convened numerous representatives from various countries to present an international strategy aimed at combating what he defined as "far-left political terrorism," seeking to coordinate security agencies and intelligence sharing.

US’s New National Security Strategy (November 2025), which has been deploying a much more aggressive imperial policy, inaugurated under the pretext of combating drug trafficking and the indiscriminate bombing, without evidence and in violation of international agreements, of small vessels in the Caribbean. An executive order from the Trump administration, "Establishing an America First Arms Transfer Strategy," promotes arms sales abroad. Latin America is considered a good market, and investments in the arms industry will further constrain public policies that could be implemented to address growing social inequalities. With the increased involvement of militaries in internal affairs, the dangers to the future of liberal democracies in the region grow, as national defense and internal control become intertwined.

The military invasion of Venezuela and the kidnapping of its president and his wife (a national deputy) on January 3 of this year were a continuation of that offensive. Simultaneously, the US threatened to annex Greenland until it had established three military bases on the island and to rename the Gulf of Mexico the Gulf of the Americas. It succeeded in getting Panama to expel Asian companies from the canal, which it declared a priority for US national security, even knowing that, due to its shallow draft, only commercial vessels can pass through. It forced Chile to suspend the project for a submarine fiber optic cable from Concón to Hong Kong, while Argentina suspended the agreement to build a radio telescope in the province of San Juan. Recently, the US ambassador to Argentina threatened members of an electric cooperative over an agreement with Huawei and warned about the continuation of US investments in Vaca Muerta. This is a pressure strategy aimed at achieving a highly ambitious objective: control of more than 30,000 km of fiber optics, an essential infrastructure for the deployment of 5G.

Trump has understood that unilateralism in the world is over, and with it, the role of US hegemonic power. He is therefore seeking to redesign the global landscape, reorganizing it into areas of influence and security dominated by the major powers (US, China, Russia) while withdrawing into the Western Hemisphere (from the Arctic to Antarctica). With this withdrawal, he aims to address what he considers strategic objectives: blocking China’s access (with $600 billion in annual trade, it is the region’s largest trading partner, in addition to financing substantial investments) and guaranteeing political control for his subordinate and unconditional allies.

They also need access to the natural resources necessary for their value chains and the energy transition. Latin America takes on particular importance in this regard, with the enormous biodiversity of the Amazon, the Andean ecosystems, and the vast wetlands. According to ECLAC, the region holds almost 20% of the world’s hydrocarbon reserves, more than 40% of global biodiversity, and 30% of primary forests, along with large river basins and the Guarani Aquifer, one of the world’s largest underground freshwater reservoirs.

In this era of accumulation by dispossession, major powers are vying for abundant resources in our region: metallic minerals (gold, silver) and so-called critical minerals (lithium, copper, nickel, cobalt, among others), as well as rare earth elements (17 little-known elements that play a central role in the manufacture of lithium batteries, magnets for electric vehicles, electronic circuits, catalysts for the chemical industry, and turbines for wind turbines and the arms industry). Various international organizations have estimated that the demand for these minerals will quadruple in the coming decades.

Almost all the far-right governments in Latin America are followers of Trumpism’s environmental denialism. They deny climate change and encourage the indiscriminate exploitation of our societies’ common resources, since most of our countries’ economies depend on the export of primary products and are heavily reliant on extractive industries. This exacerbates the climate crisis already affecting the subcontinent (loss of biodiversity, air and soil pollution, and contribution to global warming). According to National According to the United Nations, since 2000 a total of 152 million people in the region have been affected by 1,205 natural disasters, including droughts, floods, landslides, fires, hurricanes, and earthquakes. The United Nations considers Latin America and the Caribbean the second most disaster-prone region in the world.

According to the Pentagon’s National Defense Strategy (January 2026), the Atlantic Ocean is of paramount importance due to its interoceanic passages. In this context, the southern part of our subcontinent plays a crucial role, thanks to the Strait of Magellan, the Beagle Channel, and the Drake Passage. Together, these constitute one of the six strategic waterways worldwide and the natural replacement for the Panama Canal in case of emergency or traffic congestion.

However, it would be a mistake to characterize this US withdrawal as implying a disengagement from its interests in other regions of the world. In reality, using a football analogy (permissible amid the World Cup atmosphere), "the team is built from the back." That is precisely what Trump has been doing since assuming his second presidential term: guaranteeing political, economic, and military control of what the US has always considered (as the Monroe Doctrine dictates ) its "backyard." To this end, he has not hesitated to interfere politically and financially in the elections of sovereign nations (the paradigmatic case of Argentina) and to militarize the region under the pretext of drug trafficking, national security, and migration. It is from this position that he seeks to recover hegemonic ground within the context of his relative decline, which, given the results of the war in the Middle East, casts doubt on his capacity for global leadership due to his undeniable defeat.

The disputed future

Most of the electoral victories that allowed the rise of far-right governments were decided in second rounds and by very few points of difference, in some cases by tenths, so the governments take over in totally polarized societies, which calls into question governability.

So far, these governments have focused more on dismantling the achievements of the previous period and modifying the role of the State (which ceases to arbitrate between social classes and reverts to being the general manager of capital’s interests) than on projecting any future. The extreme neoliberalism they profess faces serious difficulties in relaunching the process of capital accumulation and reproduction. They depend increasingly on foreign investment, generally directed toward agribusiness or extractive industries, which, to materialize, demands ever more tax breaks, legal guarantees, and capital flow restrictions that ultimately undermine the sovereignty of peoples and nations.

Thus, projects become trapped by the contradictions of the current situation, with the particularity that the long progressive decade left a foundation of social and democratic rights that workers and popular sectors do not seem willing to relinquish without a fight. Bolivia, with its months of highway blockades by thousands of workers, Indigenous people, and peasants demanding the resignation of President Paz just months after he took office; the precipitous drop in President Kast’s popularity in Chile; and the ongoing mobilizations of various sectors in Argentina are just a few examples of this resistance. In the immediate term, however, if we look beyond the immediate, what weighs heavily and determines the situation is the organic nature of the crisis of capital in the region. This crisis manifests itself in the marked inability to relaunch the accumulation process and in the disaffection of citizens with traditional parties and leaders, which is already a structural problem. These political processes are not irreversible, but their effects will be long-lasting. Nothing guarantees that far-right governments will consolidate their power, only that they will govern in a state of permanent instability, while extreme polarization foreshadows new resistance and opens up a space for the anti-capitalist left.

However, in this historical period, capital centralizes, concentrates, and homogenizes from above, while simultaneously fracturing, dividing, and creating heterogeneity from below. Thus, workers’ and popular struggles against the fascist-like nature of the extreme right and imperialist domination are fragmented and dispersed, not only at the national level but also internationally. This underscores the importance of solidarity and the integration of antifascist and anti-imperialist resistance with the defense of national and popular sovereignty.

Earlier this year, 1,800 prominent figures from around the world signed the “Call for an Antifascist International,” calling on all forces fighting against the rise of the far right, fascism, and imperialist aggression to “coordinate these struggles against increasingly threatening enemies.” The call states: “This convergence can and must include all forces willing to defend the working class, the peasantry, migrants, women, LGBTQ+ people, racialized people, oppressed national or religious minorities, and Indigenous peoples; to defend nature against ecocidal capitalism; to combat imperialist and colonial aggression, regardless of its origin, and to support the struggles of peoples resisting it.”

This call materialized at the end of last March when thousands of people from more than 30 countries gathered in the city of Porto Alegre, Brazil, giving rise to the 1st International Antifascist, Anti-imperialist and for the Sovereignty of Peoples Conference, to share analyses, strengthen ties and agree on concrete actions.

The task will be continued by the Latin American Anti-Imperialist and Anti-Fascist Regional Conference, to be held in Buenos Aires on December 17, 18 and 19 of this year, and then another one in Mexico possibly in March 2027.

The path is laid out; it will be difficult to achieve, but not impossible.

Eduardo Lucita is a Director of the Marxist review Cuadernos del Sur, and member of the Argentinian group Economists of the Left (EDI) and of the Fourth International. He has been active on the revolutionary left since the 1960s.

Thursday, October 15, 2026


TU Graz uncovers major security flaws in data migration tools


Digital security breach when changing mobile phones


Graz University of Technology

Florian Draschbacher

image: 

Florian Draschbacher from the Institute of Information Security at Graz University of Technology (TU Graz).

view more 

Credit: Lunghammer - TU Graz


The standard data migration tools offered by major Android manufacturers such as Samsung, Google and Xiaomi pose significant security risks, as researchers from the Institute of Information Security at Graz University of Technology (TU Graz) and Zentrum für sichere Informationstechnologie (A-SIT) have revealed in a recent study. Their research revealed that critical vulnerabilities in all the tools examined allowed attackers within Wi-Fi range to spy on private user data such as call logs, photos and login details.

Security risk associated with phone cloning

So-called phone clone tools or data migration tools are designed to make it easier to switch from an old smartphone to a new device. The aim is to transfer all data, settings and apps seamlessly from the old device to the new one. These tools usually establish a direct Wi-Fi (WLAN) connection between two smartphones without the need for an external server. However, research carried out by the Graz-based IT security researchers Florian Draschbacher, Lukas Maar, Lorenz Schumm, Rene Denifl, Lukas Treffner and Stefan Mangard now shows that this convenience comes at a huge cost to security.

In all the data migration apps examined from seven Android manufacturers – Google, Samsung, Vivo, Xiaomi, Oppo, Huawei and Honor – the team found vulnerabilities that would allow them, as attackers, to manipulate the transfer or eavesdrop on it. They simply had to be within radio range of the devices – indoors, that’s around 20 to 45 metres. Using inexpensive equipment costing less than 100 euros, they were able to eavesdrop on the data transfer. Places where large numbers of new mobile phones are set up every day, such as specialist electronics shops or mobile phone shops, are particularly vulnerable to such attacks.

Digital life in the spotlight

The potential risk posed by these vulnerabilities is enormous, as almost the entire contents of a smartphone are transferred during a data migration. As part of their investigation, the researchers were not only able to access text messages, contacts and photos, but also to extract highly sensitive information such as health data, login details for saved Wi-Fi (WLAN) networks and app passwords. In some cases, it was even possible to inject malware directly into the new device via app packages that had been tampered with during the transfer.

Billions of users affected – manufacturers respond

The significance of the discovery is evident from the installation figures. The apps examined have been downloaded more than 12 billion times in total and come pre-installed on almost every Android device. “Because these apps are pre-installed and are very convenient for transferring data to a new mobile phone, these security vulnerabilities have a huge impact,” says Florian Draschbacher. The team at TU Graz had already reported the vulnerabilities to the manufacturers in advance as part of a responsible disclosure process. They had confirmed the severity of the issues (including five security alerts classified as high).  All seven manufacturers have now released security updates to address the reported vulnerabilities. The researchers urge users, before migrating data between two smartphones, to “ensure that the latest version of the data migration app is installed on both devices, and to always install all relevant updates.” In some cases, this may require updating the entire operating system.

The following Android manufacturers and data transfer apps were examined:
Google Android: Android Switch
Samsung: Smart Switch
Vivo: EasyShare
Xiaomi: Mi Mover
Oppo: Clone Phone
Huawei: Phone Clone
Honor: Device Clone

About the study:
The paper “Clone2Pwn: A Systematic Security Analysis of Data Migration Tools in the Android Ecosystem” was authored by researchers from TU Graz and A-SIT Austria and published at the European Symposium on Research in Computer Security (ESORICS) 2026.

Successful cybersecurity research at TU Graz

This study is the latest in a series of globally significant cybersecurity risks that have been identified by the Institute of Information Security at TU Graz. For example, a team from the institute was involved in the discovery of the security vulnerabilities Meltdown and Spectre, which affected the vast majority of modern computer processors. In 2024, researchers discovered SnailLoad, which allows users’ online activities to be monitored by comparing the latency times of internet connections with the digital fingerprint of online content. They also discovered the attack method Collide+Power, in which an analysis of a computer processor’s energy consumption makes it possible to read data from its memory. However, the institute is also conducting research in the opposite direction. The Ascon algorithm developed by Maria Eichlseder, Christoph Dobraunig, Florian Mendel and Martin Schläffer, was designated the international standard for lightweight cryptography in 2023. In April 2026 TU Graz opened the Cybersecurity Campus Graz, a new facility dedicated to cutting-edge research and teaching in the field of IT security.

Monday, October 12, 2026


LATAM BLOG: Bolsonaro will strip the B from BRICS

LATAM BLOG: Bolsonaro will strip the B from BRICS
Brazil, Latin America's largest economy, would be the biggest catch in the region’s run of right-wing victories. / X


By IntelliNews Latam desk October 11, 2026

When Goldman Sachs’ Jim O’Neill coined the BRICS acronym in 2001, Brazil stood at the front of it. A quarter of a century later, it may be the first founding member to walk away from the burgeoning trading bloc.

Flávio Bolsonaro’s narrow first-round win on October 4, with 47.03% of valid votes against 45.16% for President Luiz Inácio Lula da Silva, is hardening into a lead. The first post-ballot survey by PoderData/Aya puts the senator on 53% and the seasoned leftist leader on 47% ahead of the October 25 runoff, a three-point swing each way since its last pre-vote poll. Lula, 80 and seeking a fourth term, is fighting a rival 35 years his junior who carries his imprisoned father’s name and his father’s grievances.

Most commentary on the race has focused on crime, the dire fiscal outlook and the fate of Brazil’s Supreme Court, embroiled in a sprawling scandal linked to a failed bank. The bigger consequences, however, may lie abroad. Flávio Bolsonaro said in June that on his first day in office he would reassess whether Brazil should remain in a bloc he called “highly ideological”, accusing it of baiting Washington over the dollar, and that leaving was on the table. His foreign policy programme runs to two pages. It does not mention BRICS, prioritising OECD accession and closer ties with the US, Israel and Argentina.

History suggests he may not follow through. After all, his father kept Brazil in the group, trade with China hit records on his watch and Brasília resisted US pressure to exclude Huawei from its 5G rollout. Analysts argue that export interests and institutional inertia would constrain the son just as they constrained the father. “China’s weight in Brazil’s trade and investment relationships would impose substantial limits on any effort to privilege Washington at Beijing’s expense,” Brookings scholars Diana Paz García and Bruce Jones wrote in a short essay.

That reading underestimates how much has changed. In 2019, BRICS was a low-cost talking shop of five. Today it includes Iran, Egypt, Ethiopia, the UAE and Indonesia, and its agenda leans openly towards dedollarisation. Washington no longer tolerates hedging either. President Donald Trump has threatened extra tariffs on any country aligning with what he calls the bloc’s anti-American policies, and he slapped heavy duties on Brazilian goods in 2025 partly in retaliation for the prosecution of former president Jair Bolsonaro, a close ideological ally. A Bolsonaro 2.0 government indebted to Washington for an overt campaign of interference on its behalf would find a BRICS exit a cheap way to settle the debt.

And cheap is the operative word, because BRICS is not China. Brazil exported $99.9bn of goods to China last year, nearly three times the $37.7bn it sold to the US, and almost 80% of its soybean exports went to Chinese buyers. None of that trade runs through BRICS. Beijing buys soybeans and iron ore because it needs them, not because Brazilian diplomats attend summits. A president can leave the club and keep the customer. The only real tie is Brazil’s nearly 20% stake in the New Development Bank, and that is a balance-sheet question rather than a strategic one.

For Washington, meanwhile, the prize is considerable. The so-called Donroe Doctrine, Trump’s revival of the Monroe Doctrine, has moved from slogan to practice this year. US forces seized Nicolás Maduro in January and left his deputy, Delcy Rodríguez, running Venezuela under US tutelage. In March, Trump gathered a dozen friendly governments at his Doral resort to launch the Shield of the Americas, a flagship counter-cartel security coalition. Brazil, Mexico and Colombia were not invited. Flávio Bolsonaro, by contrast, used a White House meeting in May to ask Trump to designate two Brazilian criminal groups as foreign terrorist organisations, and Washington promptly obliged.

Brazil, Latin America's largest economy, would be the biggest catch in the region’s run of right-wing victories, from Chile last December to Colombia and Peru this year, all of them cheered on openly by the Trump administration. Once it falls, Mexico will be the only large nation in the region still governed by the left, and Claudia Sheinbaum has proved far more pliable to US demands than Lula. Argentina, which set the pace for the region’s swing to the right, was the proof of concept. Javier Milei turned down the country’s BRICS invitation on taking office in 2023 to pursue closer US ties, yet kept its trade and financial links with Beijing intact. Brazil would be the consolidation.

It would also be the richer haul: Brazil offers almost everything the US wants to stop buying from China. It holds nearly a quarter of global rare earth reserves yet produced less than 1% of world output last year. The test case came in September, when USA Rare Earth completed its roughly $2.8bn takeover of Serra Verde, Brazil’s only commercial rare earth producer. The deal was backed by a $565mn loan from the US International Development Finance Corporation and $750mn from the Department of War. Lula criticised the deal but did not block it. He did sign a critical minerals law that creates an interministerial council with power to approve and prioritise projects. Talks on a federal minerals accord with Washington have stalled over a clause Brazilian officials read as granting the US preferential access.

Under Lula, that council is a gatekeeper. Under a Bolsonaro, it becomes a turnstile. Flávio raised rare earths with Trump in May and has backed closer cooperation on processing. Add oil exports heading for a record this year, and Brazil starts to look like the resource anchor of an American hemisphere rather than the swing state of a multipolar one.

That is the blow to Beijing and Moscow. BRICS’ claim to speak for the Global South rests on geography as much as on economics. It needs a democratic, non-aligned Latin American heavyweight to rebut the charge that it is a front for Russian and, most importantly, Chinese ambitions. Lula supplied exactly that. He pushed local-currency settlement with China, planned a yuan-denominated sovereign bond and installed former president Dilma Rousseff at the helm of the New Development Bank in Shanghai. He also co-founded the Partners for Multilateralism initiative with Canada, the EU and India last month, a project Brookings' García and Jones expect a Bolsonaro victory would interrupt.

The bloc’s champions insist the loss would not matter. Pepe Escobar, a Brazilian commentator and longtime advocate of the Sino-Russian project, told Brazil’s TV 247 that Moscow and Beijing are building a multipolar architecture “with or without Brazil”. He warned that the country risks reverting to “a mere backyard of the empire”. The first claim undercuts itself. A multipolar order built without Brazil, and with Argentina already gone, has no foothold in the Americas. It shrinks to a coalition of Eurasian and Gulf powers plus South Africa and an India that hedges as carefully as Brazil once did. That is a concession of the hemisphere, which is exactly what the Donroe Doctrine demands.

Even a formal exit may prove unnecessary, and the bloc’s defenders know it. Escobar’s real fear is not a clean break. He expects the White House to push a Bolsonaro government to “start destroying BRICS from within”, leaving Brazil a “pro forma” member. Flávio Bolsonaro has already shown his hand, reportedly assuring the US Trade Representative in July that he would keep Brazil’s homegrown Pix instant payments system, which Washington has targeted in a trade investigation, out of non-Western cross-border settlement schemes.

A Brazil that stays nominally inside BRICS while vetoing its financial plumbing would do the project more damage than one that slams the door. The next pressure point is likely to be Chinese industrial investment rather than soybeans. Escobar predicts Washington will press Brasília to erect barriers to Chinese electric vehicle and technology groups, whose weight in Brazil is growing fast. BYD’s plant in Bahia, opened last year, would be the first target.

Latin American politics moves in waves, and the region is currently following a rightward tide that has swept much of the democratic world. The left may return in time and reverse summit communiqués overnight, but rare earth concessions, US-financed processing plants and ironclad security pacts would prove far harder to unpick. If the polls hold, the multipolar order will lose more than a letter on October 25. It will lose the hemisphere.

Sunday, September 20, 2026


It's not malicious, it's indifference: Thousands of books sent to AI woodchipper

Cover image: © France 24


Issued on:
18/09/2026 
Play (13:55 min)


In this edition, FRANCE 24’s François Picard speaks to investigative journalist Emanuel Maiberg, Co-founder of 404 Media. As we embark on AI's uncharted waters, Maiberg has made a most unexpected discovery: the mass acquisition, dismemberment and scanning of rare books for use as training data. His investigation reveals a globalised and deliberately opaque supply chain in which books purchased through anonymous marketplaces arrive at large-scale scanning facilities, where their bindings are removed so that pages can be processed at great speed.


Maiberg’s analysis reaches far beyond the striking dystopian image of books being destroyed. What happens when knowledge changes form, changing ownership and accessibility? A book can circulate between readers, libraries and generations. Once destroyed and absorbed into a proprietary AI system, however, its contents survive virtually, encoded within a model whose outputs and rules of access are controlled by a private company. The paradox is striking: an industry seeking to ingest ever more human knowledge may simultaneously erase the very sources of that knowledge.

Maiberg does not to portray this process as a diabolical campaign to rid society of books. His more unsettling interpretation is that the destruction is driven by something more mundane: indifference. In the race to build increasingly capable AI systems, books become inputs to be optimized, and their destruction becomes an acceptable operational cost. That logic, he argues, belongs to a broader concentration of informational power already visible in search engines and social media. And now AI is taking it to a whole new level.

The investigation raises a larger question in the world of culture and academia: as more of the world's accumulated knowledge is mediated through AI systems, who controls the infrastructure through which that knowledge can be accessed?

VIDEO BY: François PICARD


China's Ulanqab plans 5mn server racks in AI compute race with US

China's Ulanqab plans 5mn server racks in AI compute race with US
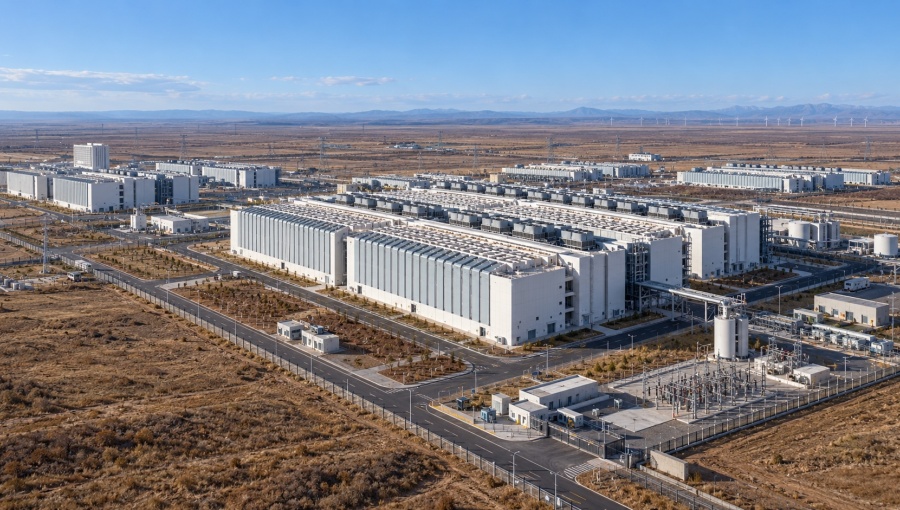
A windswept prefecture of 1.5mn people on the Mongolian plateau already uses nearly 1% of China's electricity as the country's tech giants pile in with data centres. / bne IntelliNews
By Ben Aris in Berlin September 17, 2026

A remote prefecture in China's Inner Mongolia is becoming a global centre of AI computing power. Ulanqab, home to 1.5mn people on the grasslands of the Mongolian plateau, consumes nearly 1% of all the electricity used in China, and its demand is growing by double digits every year.

Spread across the prefecture's households, that load would work out at about 105,000 kWh each a year, roughly 10 times the consumption of an average American home, by his calculation. The power is going into servers.

Over the past few years Ulanqab has signed investment agreements worth more than CNY500bn ($74bn) with China's largest technology companies, and the build-out planned there runs to more than 5mn data centre racks, according to Science and Technology Daily, the newspaper of China's Ministry of Science and Technology.

Set that against Elon Musk's Colossus supercomputer in Memphis, Tennessee, which xAI markets as the world's largest AI supercomputer. On xAI's own count of 200,000 chips, Colossus fills something like 5,000-6,000 racks, Bertrand estimated, which implies roughly a thousand times as many racks. The comparison does not measure equivalent computing power: Chinese standard racks are rated at 2.5 kW, while modern Nvidia AI cabinets can draw more than 100 kW.

"What we see appearing in this Inner Mongolian steppe may be the closest thing to a world brain humanity has ever built - a place where a large share of the world's thinking will physically happen," commentator Arnaud Bertrand wrote on X on September 14.

Anthropic chief executive Dario Amodei said China presented the hardest problem for his proposal to slow AI development, CNBC reported on September 13.

If AI turns out to be the defining technology of the century, as Bertrand argues both Washington and Beijing believe, that makes Ulanqab "one of the single most relevant geopolitical places in the world right now", he wrote.

From cloud valley to token capital.

Inner Mongolia signed 12 commercial deals worth CNY186.46bn ($27.6bn) at a green computing and AI conference in Hohhot on August 22, with China Telecom (SHA: 601728), chipmaker Cambricon Technologies (SHA: 688256) and Volcano Engine, the cloud platform of TikTok owner ByteDance, among the signatories. Active processing power in Ulanqab had by then reached 172,000 PFlops, with more than 95% of it allocated to AI work.

The largest single project so far belongs to Envision, the Shanghai-based wind turbine and battery maker, which commissioned its Galaxy campus in Ulanqab in August. The company says the 2 GW AI campus runs on renewable power and contains the world's largest single data centre building.

The Chinese business magazine Caixin devoted an in-depth report on August 14 to how the city turned itself into an AI powerhouse. Inner Mongolia is one of eight national computing hubs designated under Beijing's "East Data, West Computing" programme, which shifts data processing from the crowded, power-hungry coast to the resource-rich interior.

Cheap wind and cold air

Electricity makes up 55% of a data centre's cost, according to a McKinsey Global Institute study published in June, so the price of power decides where the servers go.

Inner Mongolia is China's "green power bank", regularly producing more wind and solar electricity than it can use at home. Envision finished a 12.8 GWh battery storage cluster across the region at the end of 2025, with sites in Ulanqab, Hohhot, Ordos and elsewhere, to soak up the surplus.

The surplus comes cheap: firm wind power backed by batteries cost about $59/MWh in Inner Mongolia in 2025, against $88-94/MWh in Brazil, Germany and Australia, the International Renewable Energy Agency (Irena) said in May.

Ulanqab's wind already runs a 1 GW electrolysis plant supplying Sinopec's green hydrogen pipeline to Beijing, nearly 400 km away, and the cool plateau climate trims the bill for keeping servers from overheating.

The data centre boom is the latest expression of China's rise as the first Electrostate, an economy built on cheap electrons, and of its position as the world's green energy champion, building two-thirds of the world's new wind and solar plants.

Racks are not chips

Chinese planners typically count data centre capacity in "standard racks" rated at 2.5 kW, while a single cabinet of the latest Nvidia AI servers draws more than 100 kW, so a rack-for-rack comparison with Colossus overstates the gap.

Measured in power, 5mn standard racks come to about 12.5 GW, in line with the planned capacity for Ulanqab reported by the newsletter AI Weekly. That is still more than six times the size of Envision's Galaxy campus. China's total data centre capacity is on course to top 60 GW by 2030, doubling the sector's power demand, according to Rystad Energy.

China's handicap lies in the chips. American hardware keeps a 9:1 lead in raw computing performance, according to American Enterprise Institute researcher Ryan Fedasiuk, and even in the most optimistic 2028 scenario Huawei would supply at most an eighth of the compute available in the US. The AEI's most pessimistic case still has domestic AI chips meeting a third of China's compute demand by 2028, up from about a fifth in 2026.

Chinese chips burn more electricity per calculation than their American rivals, which puts a premium on power that is abundant and cheap. Abundant wind power could lower operating costs, but does not by itself close the chip-performance gap.

Demand to fill it

Daily token requests to AI models across China jumped from about 100bn in early 2024 to 140 trillion by March 2026, and Inner Mongolia has started building a trade platform in the Hohhot free trade zone to sell clean computing power and access to Chinese AI models to foreign developers.

Neighbouring Mongolia unveiled plans for a renewable-powered data centre in August, pitching the same cool, dry climate and wind and solar resources, plus a location between China and Russia.

Bertrand said he had travelled to Inner Mongolia twice without hearing of Ulanqab before he began researching it. "It's really surprising this hasn't been talked about more because the scale is beyond anything else, and by an immense margin," he wrote.

High tech FDI into China climbs even as total inflows fall

High tech FDI into China climbs even as total inflows fall
/ Li Yang - UnsplashFacebook
By IntelliNews - New Taipei Bureau September 19, 2026

Foreign direct investment into China's high-tech industries rose 35.1% year on year to CNY200.26bn ($29.88bn) in the first eight months of 2026, even as total inflows declined, Xinhua reported on September 19.

The divergence points to a shift in the composition of foreign capital entering the world's second-largest economy, where Beijing has been courting research centres and advanced manufacturing plants while overall investor appetite has cooled. High-tech sectors accounted for 41.7% of all FDI in the period, up 12.4 percentage points from a year earlier, according to the Ministry of Commerce.

Actual FDI in use across all sectors fell 5.3% to CNY479.95bn. A total of 42,582 new foreign-invested enterprises were established, an increase of 0.3%.

Manufacturing drew CNY119.55bn, while the service sector took CNY350.42bn. Investment in research and development and design services jumped 74%, services for the commercialisation of scientific and technological achievements rose 64.2%, and electronic and telecommunications equipment manufacturing gained 41.9%.

Zhang Xiaotao, director of the International Investment Research Center at the Central University of Finance and Economics, said the country's growing pull in high-tech sectors marks a shift in what attracts global capital, from cost-driven to "innovation-driven," he told Xinhua. 

By source country, actual investment from France grew 39.2%, from Switzerland 16.7% and from South Korea 16.5%, with flows routed via free ports included.

South Korean semiconductor equipment maker STI is building a chip manufacturing base in Guangzhou with total investment of about CNY12.4bn, while German automotive parts group Schaeffler is adding CNY1bn to a humanoid robotics plant in Jiangsu province.

In June, Beijing issued a 15-measure action plan on foreign investment covering market access, investment procedures and protections for foreign investors. A revised Catalog of Encouraged Industries for Foreign Investment took effect on February 1, directing capital towards advanced manufacturing, modern services and the central, western and northeastern regions.


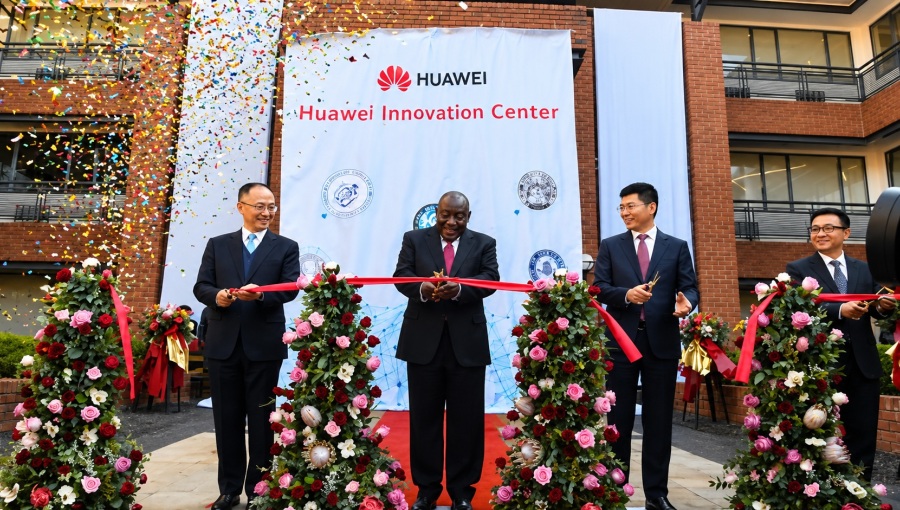
Trump’s war on Huawei spreads through Africa

Trump’s war on Huawei spreads through Africa
/ HuaweiFacebook
By bne IntelliNews September 20, 2026

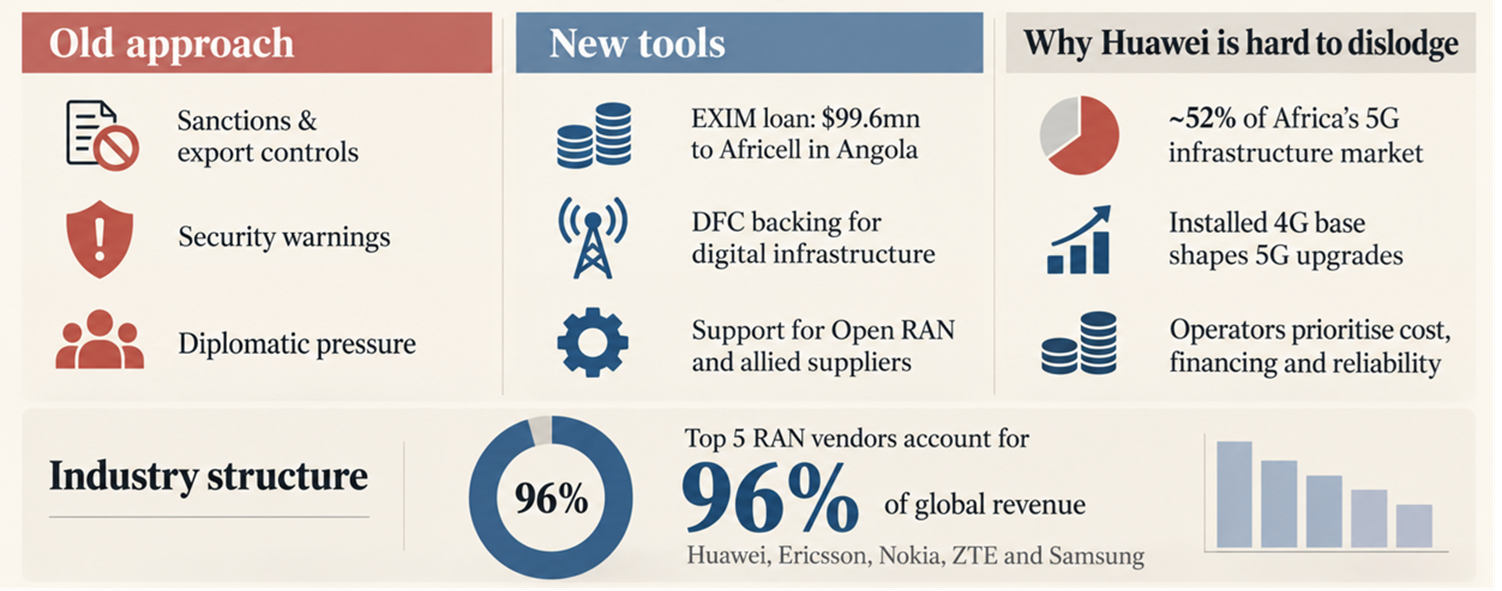
A $99.6mn US government loan to Africell in Angola would be unremarkable beside the sums being spent on Africa’s telecoms infrastructure were it not for what Washington wants the money to buy.

The Export-Import Bank of the United States announced this month that it would finance American and European network technology for the US-owned mobile operator. Reuters described the loan as part of the Trump administration’s effort to counter Huawei overseas, citing an estimate from Counterpoint Research that the Chinese company supplies about 52% of Africa’s 5G infrastructure.

Five days later, another arm of the US government widened the picture. The US International Development Finance Corporation approved an equity investment in WIOCC Group, whose fibre networks, wholesale connectivity and data-centre infrastructure span 30 African countries. DFC said the investment would support US technology companies and advance American strategic interests on the continent.

The two transactions fit a broader US approach to competing with Huawei despite lacking an American equivalent. Rather than trying to replace the Chinese group with a single US supplier, Washington is using public finance to support an alternative ecosystem built around European network equipment, American technology and non-Chinese digital infrastructure.

The Africell loan addresses the equipment side of that approach by financing Africell’s purchase of alternative network technology. The WIOCC investment suggests that the same strategic logic is extending to fibre, data centres and wholesale connectivity, infrastructure on which US technology companies depend. Neither deal amounts to an African telecoms strategy on its own, but together they show how Washington’s long confrontation with Huawei is acquiring a more financial dimension.

From pressure to finance

Donald Trump’s campaign against the Chinese group began much earlier. During his first term, the administration restricted Huawei’s access to US technology and launched the Clean Network initiative, pressing governments and operators to exclude suppliers Washington considered security risks. Eswatini became the first African country to join the programme in early 2021.

US officials argued that Huawei’s presence in critical communications networks created espionage and data-security risks because of the company’s relationship with Beijing and its obligations under Chinese law. Huawei has consistently rejected allegations that its equipment could be used for spying.

Africa presented a harder commercial problem.

Huawei had already spent years supplying equipment across the continent, building relationships with operators and governments and becoming embedded in existing networks. Unlike in markets where governments were prepared to restrict Chinese vendors, African operators also had to contend with the economics of expanding coverage in countries where capital was scarce and average revenue per customer was often low.

Washington recognised some of that problem even during Trump’s first term. When Eswatini joined the Clean Network, senior State Department official Keith Krach said EXIM had been given authority to finance 5G projects using equipment from trusted non-US suppliers such as Ericsson (STO: ERIC B; NASDAQ: ERIC), Nokia (HEL: NOKIA; NYSE: NOK) and Samsung Electronics (KRX: 005930; LSE: SMSN). US financing, he argued, could help close the cost gap with Huawei and ZTE (SZSE: 000063; HKEX: 0763).

The idea is therefore not entirely new. What is becoming more visible is the use of public capital to put it into practice.

Africell offers an unusually convenient starting point. It describes itself as Africa’s only US-owned mobile-network operator and has operations in Angola, the Democratic Republic of the Congo, Sierra Leone and The Gambia. Africell says its Angola business has attracted more than 8mn customers, while the group currently reports more than 15mn subscribers across its four markets.

Its network also already follows the kind of supplier model Washington would like to encourage. Nokia announced in 2021 that it would provide radio, core and IP technology for Africell’s Angola launch. US financing can therefore support European network hardware alongside American components, software and other technology.

The missing US champion

The structure of the global equipment market helps explain that approach.

The global radio access network (RAN) industry remains extraordinarily concentrated. Huawei, Ericsson, Nokia, ZTE and Samsung accounted for 96% of worldwide RAN revenue in the first half of 2026, according to Dell’Oro Group. Two of those companies are Chinese, two European and one South Korean. None is American.

That leaves Washington reliant on a combination of public financing, European radio equipment and American semiconductors, software, cloud and networking technology.

Open Radio Access Network (Open RAN) technology fits into the same strategy. By making interfaces between network components more interoperable, Open RAN is intended to reduce operators’ dependence on tightly integrated systems from a single supplier. US policymakers across successive administrations have put substantial funding behind open and interoperable networks, including through the $1.5bn Public Wireless Supply Chain Innovation Fund launched under the Biden administration. The Trump administration has since redirected part of that effort towards AI-native network architecture.

The administrations have differed in approach, but the attraction for Washington is consistent. A more fragmented network architecture creates room for US technology companies even if they do not manufacture complete mobile networks.

Huawei’s installed-base advantage

Huawei’s advantages, however, extend beyond the architecture of its equipment.

Chinese lenders historically played a significant role in financing African communications infrastructure. Boston University’s Chinese Loans to Africa database estimates that Chinese lenders committed about $15.7bn to African information and communications technology projects between 2000 and 2023. The model helped finance infrastructure in markets where governments and operators could otherwise struggle to raise capital.

That source of finance has since receded sharply. Boston University found no new Chinese loan commitments to African ICT projects in 2024, describing the sector as increasingly market-driven. Overall Chinese lending to Africa is also far below the levels reached during the early years of the Belt and Road Initiative.

The decline in sovereign lending does not amount to a broader Chinese retreat from Africa. IntelliNews reported in August that Chinese Belt and Road investment announcements in Africa reached a record $33.5bn in the first half of 2026, with the model increasingly shifting from state-backed lending towards direct corporate investment in productive assets.

The change therefore concerns the form of Chinese capital more than its disappearance. For Huawei, however, financing is only part of the advantage.

Huawei has retained an advantage that does not depend on cheap credit: its installed base.

Mobile networks are built incrementally. Existing 4G equipment influences how an operator moves into 5G, and changing vendors can require new hardware, integration work and retraining. An incumbent supplier able to offer a relatively straightforward upgrade therefore begins with an advantage before financing terms are even discussed.

The $99.6mn Africell loan tackles one part of that equation by reducing the financing constraint around alternative suppliers. It does not solve the switching problem for operators whose networks already rely heavily on Huawei.

Nor is Africell representative of the biggest commercial test. As a US-owned challenger already using Nokia equipment, it is unusually aligned with Washington’s objectives.

Persuading one of Africa’s large incumbent operators to change procurement strategy would be considerably harder. Such companies operate across multiple countries, have billions of dollars invested in existing infrastructure and generally buy equipment from several vendors. Network decisions have to satisfy commercial requirements that extend well beyond geopolitical preference.

Beyond the mobile network

The difficulty of dislodging an incumbent network supplier helps explain the significance of Washington’s push elsewhere in Africa’s digital infrastructure, even if the investments are not explicitly presented as substitutes for competition in mobile-network equipment.

DFC had already invested $50mn in pan-African digital infrastructure company Cassava Technologies before its latest WIOCC transaction. The agency explicitly presented that investment in terms of strategic competition, arguing that support for African fibre, data centres and digital services could expand the position of US and allied technology companies.

Its September investment in WIOCC pushes the same approach further across an infrastructure footprint covering 30 African countries. DFC called it its largest digital investment to date and said WIOCC’s networks were used by American technology companies expanding on the continent.

The strategy therefore reaches beyond who supplies a mobile operator’s antennas. Fibre networks, data centres and wholesale connectivity increasingly determine where cloud services and other digital businesses can expand. Huawei itself operates well beyond traditional telecom equipment, including in cloud computing and enterprise technology.

That infrastructure is becoming more economically important as Africa’s cloud and data-centre market expands. IntelliNews reported in January that Africa still accounted for only about 1% of global data-centre capacity, but capacity was forecast to grow rapidly as cloud adoption and internet use increased, with South Africa, Kenya, Nigeria and Egypt emerging as leading markets.

Africa’s commercial calculus

Describing all this simply as a US-China contest can obscure the calculations being made in African capitals and boardrooms.

Telecom operators need affordable equipment, financing, spectrum, fibre links and reliable electricity. Many are still spending heavily to increase ordinary 4G coverage even as richer markets debate advanced 5G services. Currency weakness and high borrowing costs can make capital expenditure particularly difficult.

The same constraints apply further down the digital-infrastructure chain. The Africa Data Centres Association says power availability has overtaken connectivity as the principal obstacle to data-centre expansion on the continent, meaning the effectiveness of new capital will also depend on access to reliable electricity at commercially viable sites.

That commercial pressure helps explain why African governments and operators are unlikely to treat technology procurement simply as a choice between geopolitical blocs. Dare Leke Idowu of the University of Johannesburg argues that African governments are increasingly hedging between the US and China, selecting partners according to infrastructure needs, domestic priorities and financing conditions rather than committing to either technology ecosystem.

Those conditions favour whichever supplier — Chinese, European, American or otherwise — can offer the best combination of price, financing, reliability and support. Washington’s security campaign can influence the political environment in which those decisions are taken, but it cannot by itself change their economics.

The growing use of EXIM loans, DFC equity and support for alternative network architectures suggests Washington is increasingly trying to compete on that terrain as well.

Huawei enters the contest with an extensive installed base and decades of relationships across the continent. The US enters without a Huawei of its own.

Its answer is to finance a coalition instead.

Whether that financing can alter the procurement decisions of Africa’s larger telecom operators will be the harder commercial test.