Six months after Trumpy & Bibi launched Operation Epic Fury against Iran on February 28th, the so-called kinetic campaign has settled into a costly stalemate, at best. And a de facto military defeat as a practical matter.
In fact, what began as another furious “shock and awe” military offensive designed to quickly and fatally degrade Iran’s nuclear program, missile forces, leadership, and regional power projection capability has instead produced:
- no regime change.
- no collapse of Iranian governance.
- the severe depletion of American high-end munitions.
- badly damaged US forward bases across the entire Persian Gulf (Bahrain, UAE, Qatar, Saudi Arabia, Kuwait, Iraq, Jordan)
- significant personnel casualties, including 18 dead and 400 injured US servicemen.
- Massive Federal budget costs now approaching $100 billion and rising rapidly.
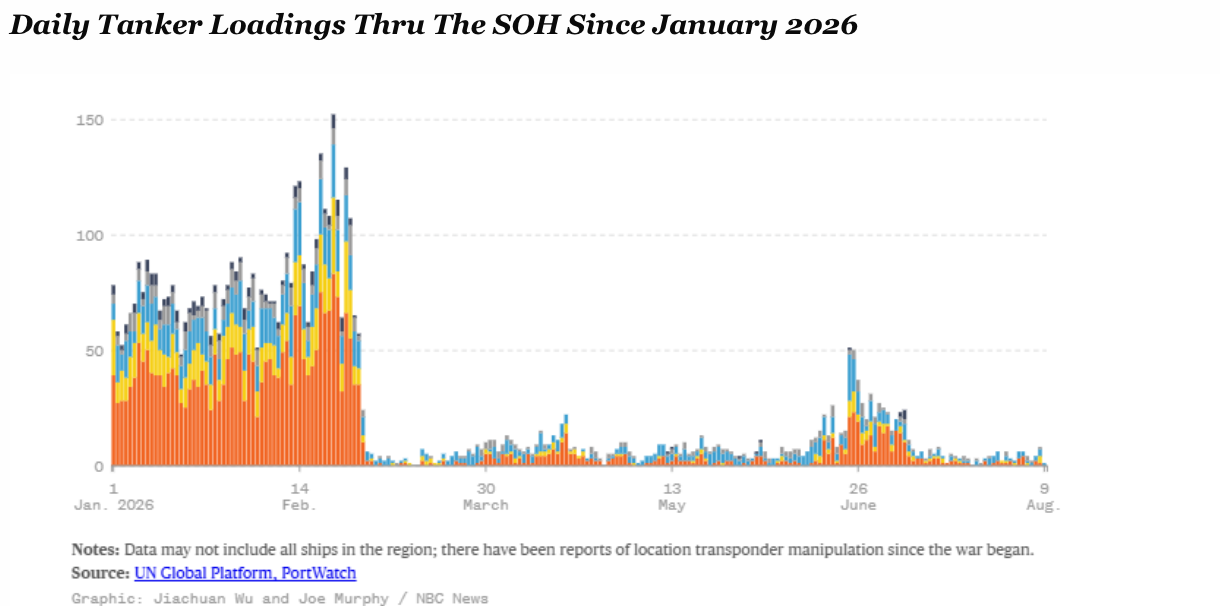
Even more importantly, this misbegotten war has handed Tehran a durable pretext for restricting maritime traffic through and around its territorial waters and the Strait of Hormuz (SOH). That is, with virtually inexhaustible supplies of homemade missiles, drones and other tools of sabotage, Iran has been handed what amounts to a global economic Kill Switch.
Yes, Washington’s naval blockade can reduce Iranian oil exports to a trickle, as shown in the table below. But the inverse is also true. Iran’s residual capacity to inflict damage on ships transiting the SOH, in combination with the resulting soaring insurance premiums, has also reduced non-Iranian export shipments through the SOH to barely 25% of steady state pre-war levels:
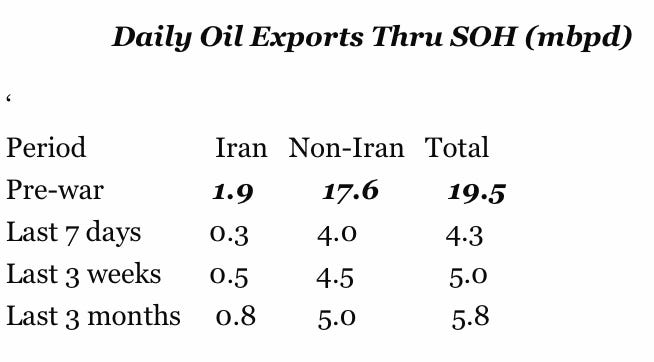
Needless to say, the cumulative economic disruptions from this drastic supply restriction, as measured in sharply higher energy prices, deep inventory draw-downs and increasing global growth drag, is making the current military stalemate untenable – especially as the November mid-terms draw ever closer.
Accordingly, Trumpy has now pivoted to an all-out economic war. Over the weekend Treasury Secretary Scott Bessent bombastically promised measures of economic isolation “never seen” in history. He was referring to an enhanced version of his ballyhooed Operation Economic Fury that is to be paired with the ongoing naval blockade.
Yet this economic escalation is not even remotely likely to succeed on the timeline or at the cost Bessent & Co assume. That’s because Iran remains substantially self-sufficient in food and many essentials, retains residual oil revenues through black-market channels and pre-blockade floating cargoes, and can endure prolonged isolation far longer than the already-strained global refined-product markets – especially diesel and jet fuel – can tolerate continued severe supply curtailment.
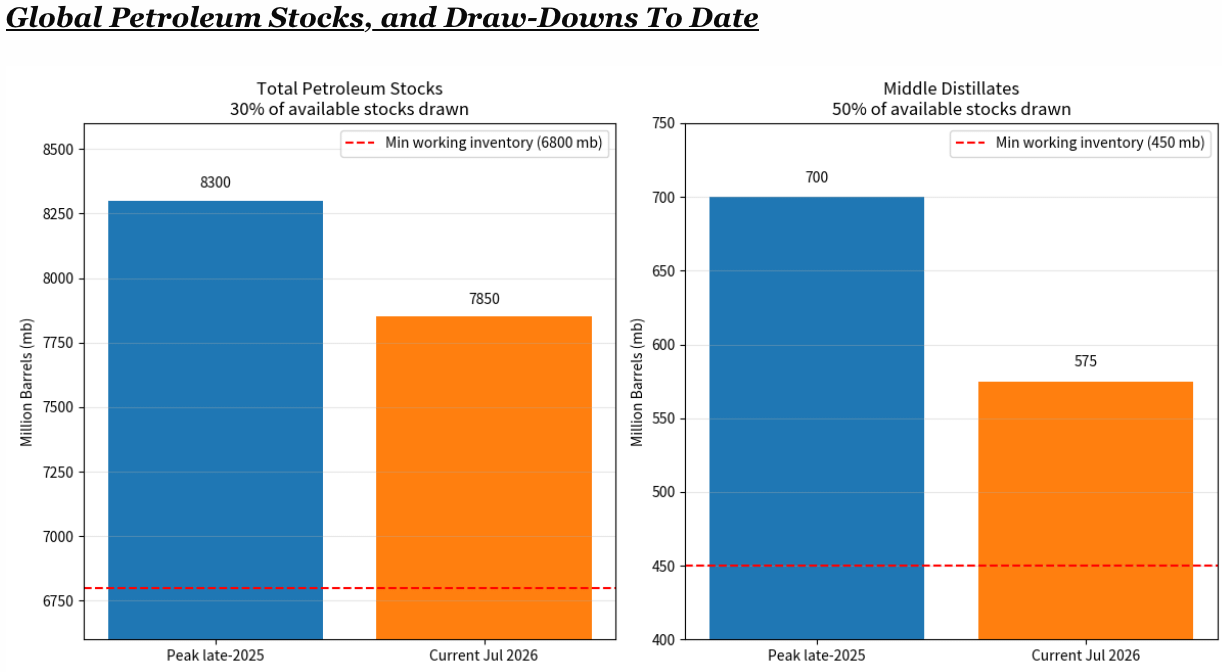
The fact is, global petroleum markets are badly strained, notwithstanding the more modest indications from what appears to be the Washington manipulated crude oil futures markets. As it happened, global physical stocks of petroleum were unusually high at the onset of the war – especially in China – so the initial impact of the 75% average reduction in shipments thru the SOH has been a one-time draw-down of these plentiful stocks.
As shown in the chart below, total global stocks (including government controlled “strategic reserves”) stood at 8.3 billion barrels in the peak months before February 2026. That compared to an estimated “working level minimum” for the global petroleum supply system of about 6.8 billion barrels. Accordingly, 30% of the pre-war excess stocks have already been drawn down – a safety valve that has kept a lid on global prices.
Moreover, on the crucial matter of middle distillates – diesel and jet fuel – which drive the global transportation of goods and people, the draw-down has been even more severe. The prewar stock level of 7oo million barrels contained 25o million barrels above the working minimum (est. 450 million barrels). Already, however, 125 million barrels or 50% has been consumed.
Needless to say, as stocks get ever closer to working minimums, the likelihood of consumer and distributor hoarding action increases sharply, thereby setting the stage for a blow-off top in global prices.
Indeed, a blow-off top in middle distillates and even gasoline is likely to happen long before the mullahs and their IRCG warlords are forced to cry UNCLE!
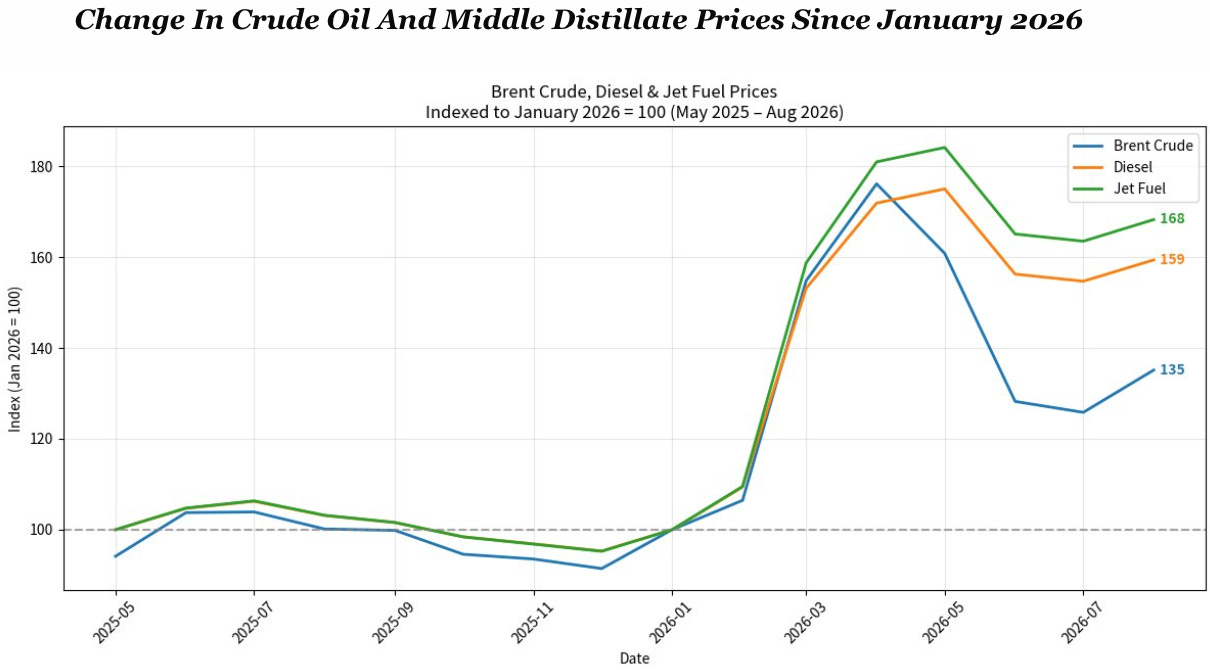
As shown in the graph below, while Brent crude (blue line) is currently up +35% from its pre-war level, diesel prices (orange line) are up by +59% and jet fuel prices (green line) are higher by+68%. This large differential is due to the sharp curtailment of middle distillates from Persian Gulf refineries and the manner in which overall crude shortfalls have impacted refinery slates around the world.
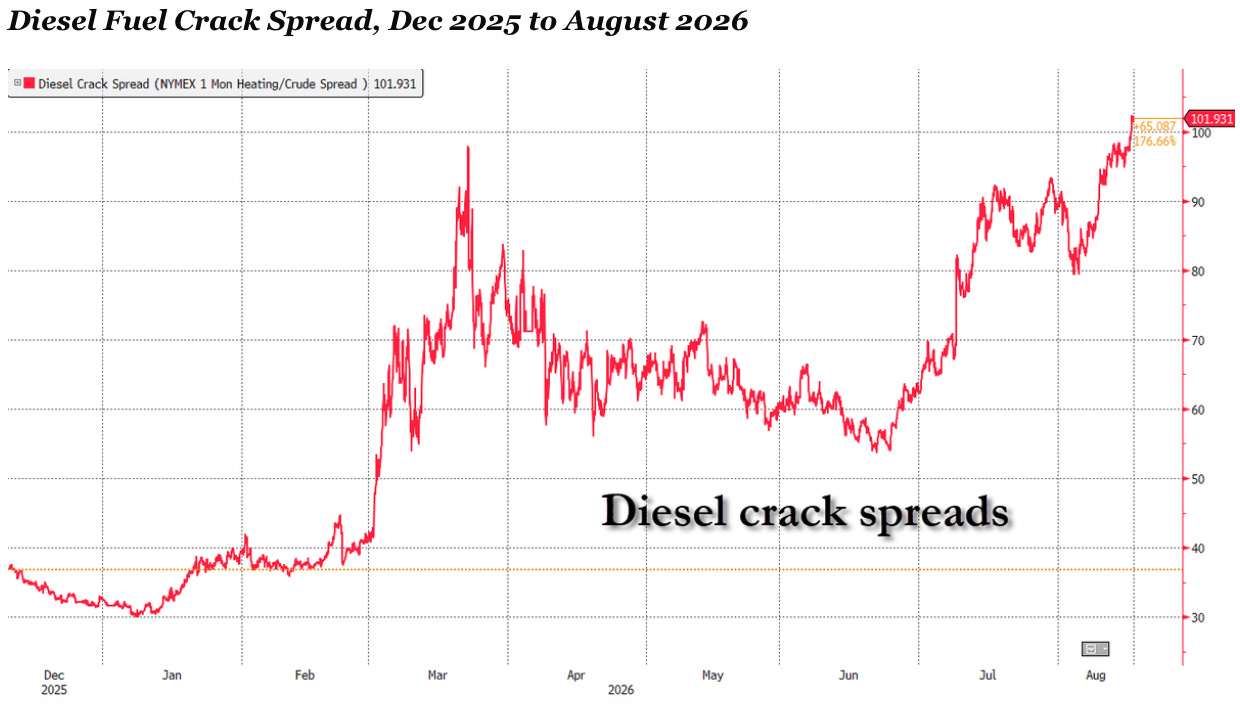
The evidence that the end product markets are far tighter than implied by the crude oil marker prices is clear as a bell in the graph below. The diesel crack spread – the per barrel price of input crude versus output diesel fuel – is now at previously imagined highs. As opposed to a normal spread of $40 per barrel, the diesel crack spread now exceeds $100 per barrel – a thundering testimony to the scarcity of a product that literally drives the goods-based economy.
So just give our wanna be warrior at the Treasury Department a few more months of 75% closure of the SOH export routes – and potentially a Houthi-caused jam-up in the Red Sea – and he will likely send refined product prices soaring – including for heating fuel uses just as the northern hemisphere heating season approaches.
Accordingly, Secy Bessent’s blustering proclamation of a new phase of Operation Economic Fury mirrors the same clueless overconfidence that marked the kinetic phase under Defense Secretary Pete Hegseth. That is to say, an exaggerated belief in the coercive power of American policy instruments and an under-appreciation of adaptation, second-order effects, and the relative resilience of the Iranian target versus the fragility of the global system that must absorb the costs.
The result, of course, is a lopsided race between a blockaded Iranian economy and the diesel- and jet-fuel-dependent economic arteries of the United States and the world. And on current evidence, the global petroleum market is the side closer to buckling.
The Kinetic Failure of Operation Epic Fury
At this point it is well to recall how badly the military phase of Operation Epic Fury has failed. It opened with much fanfare and overweening confidence that the intensive airstrikes that killed senior Iranian leaders, including Supreme Leader Ali Khamenei, degraded air defenses, struck naval and missile infrastructure and damaged nuclear-related sites would deliver a knock-out blow.
Indeed, early DOD claims spoke of thousands of targets hit and rapid progress toward decisive outcomes. But by mid-2026 the picture is drastically different. Fragile ceasefires and the June 17 Memorandum of Understanding produced temporary pauses and limited re-openings of SOH. However, hostilities quickly resumed, the U.S. blockade of Iranian ports has continued, and Iranian missile and drone attacks on U.S. and regional bases have persisted.
What has emerged, therefore, is ab echo of the stalemated trench warfare of WWI: That is, a “no end, no peace” equilibrium in which neither side can compel the other’s full capitulation without unacceptable further costs.
U.S. human costs include roughly 18 service members killed and more than 400 wounded – most owing to Iranian strikes on US Gulf bases. Financial estimates from the Center for Strategic and International Studies place direct war costs at upwards of $40 billion by late June, with munitions the largest component at approximately $26 billion.
However, when you factor in current defense supplementals and broader accounting estimates, the totals push far higher. Base and infrastructure damage across some 20 facilities in Kuwait, Bahrain, Qatar, the UAE, Saudi Arabia, Jordan and elsewhere have run into the tens of billions, rendering certain sites nearly uninhabitable and forcing personnel dispersal. Aircraft losses – dozens of platforms including Reapers, fighters, tankers and helicopters – add further hundreds of millions to billions.
Most constraining of all, however, is the munitions drawdown. Reliable reporting indicates Washington has expended virtually all of its global stockpiles of ATACMS and Precision Strike Missiles, roughly half of its Tomahawks, approximately 65 percent of Patriots, and upwards of 70% of THAAD interceptors. Replenishment will require years even under accelerated production.
At the same time, Iran’s residual capabilities remain significant. The nuclear program was heavily damaged but not eliminated; highly enriched uranium stocks and reconstitution potential persist. Missile and drone inventories were reduced but not exhausted, allowing continued strikes. And its deeply protected underground manufacturing sites continue to produce more missiles and drones.
Most importantly, the regime survived leadership losses and continues to function effectively owing to the highly decentralized governance structure put in place before the war but in anticipation of exactly the kind of strikes that the DOD carried out,
Critically, and as indicated above, the US/Israel initiated conflict gave Iran political cover to restrict or close traffic through the Strait of Hormuz – normally carrying roughly one-fifth of global oil and significant LNG – while the reciprocal U.S. blockade compounded the disruption, as quantified above.
In strategic terms the initiator of an offensive war that settles into attritional stalemate after six months without achieving its principal political or military objectives has failed. Epic Fury imposed real pain on Iran but at a steep cost and with residual Iranian agency that prevent any claim of victory.
Iran’s Resilience Under Blockade
The assumption underlying Bessent’s forthcoming Economic Fury measures is that tighter economic isolation, layered on the naval blockade, will rapidly compel Iranian concessions. But that assumption collides with Iran’s long-demonstrated structural resilience. Decades of prior sanctions and isolation forced Tehran to prioritize self-sufficiency and embrace an autrakic modelfor its domestic economy.
Domestic production covers approximately 85 percent of food needs; agriculture has continued to expand output in poultry, eggs, meat, greenhouse crops and wheat deliveries even amid drought and war. Northern ports and land borders with neighbors have facilitated continued imports of remaining essentials, while diversified trade routes and crisis-management mechanisms have prevented acute shortages of the sort that would force immediate political collapse. Iranian officials report that strategic food reserves have not drawn down during the conflict to date.
To be sure, the Iranian economy is under severe stress: year-on-year inflation has exceeded 70-80 percent, food inflation is higher still – even as the rial’s FX rate has collapsed and GDP is projected to contract several percentage points in 2026.
But these stresses are not the same as imminent buckling. Self-evidently, oil revenue has been sharply reduced by the blockade. Yet residual channels persist. Substantial volumes of Iranian oil left the Gulf before the tightest enforcement and remain in floating storage or on the blue water. Estimates of pre-blockade offshore stocks ran into the tens of millions of barrels, providing a multi-month revenue cushion as cargoes reach buyers (primarily China) and payments clear.
Shadow-fleet operations, ship-to-ship transfers off Malaysia and elsewhere, and temporary windows during the June-July MoU period allowed additional exports measured in tens of millions of barrels. Limited overland or alternative routing, while far smaller than seaborne volumes, further softens the oil revenue cut-back Black-market sales continue to generate hard currency even at steep discounts.
Iran is not immune to pressure, of course. Industrial damage, lost export revenue, hyperinflation and job losses are real. Input-output analyses suggest structural exposure in the range of 10-15 percent of output and value added from the combined kinetic and blockade shocks. But an economy that has practiced survival under sanctions for years, that feeds itself largely from domestic production, and that retains residual oil monetization can absorb months and months of further isolation.
The time horizon required for the blockade and new secondary measures to produce decisive political change is measured in multiple quarters or longer, not weeks.
The Global Stock Drawdown and the Tightness of Diesel and Jet Fuel
While Iran endures, the global stock buffers that absorbed the initial Hormuz shock have been largely exhausted, as we demonstrated above. Before February 28th commercial and strategic petroleum inventories sat well above recent historical ranges in many regions. China’s commercial and strategic holdings were estimated at well over one billion barrels after years of opportunistic filling.
IEA members also held emergency strategic stocks sufficient for coordinated release. After the conflict began, the market absorbed the largest supply disruption in modern oil-market history – at peaks more than 12–14 million barrels per day of affected Middle East flows – through a combination of demand destruction, alternative routing via pipelines, U.S. and other non-Gulf supply growth, the largest-ever IEA emergency stock release (400 million barrels), and aggressive inventory draws.
Despite all those mitigating factors, observable global crude inventories nonetheless fell at record rates in the March–May period. China reduced seaborne imports dramatically (by several million barrels per day at points) while drawing selectively on commercial stocks. So by mid-2026 China’s draws had totaled tens of millions of barrels even while total holdings remained large.
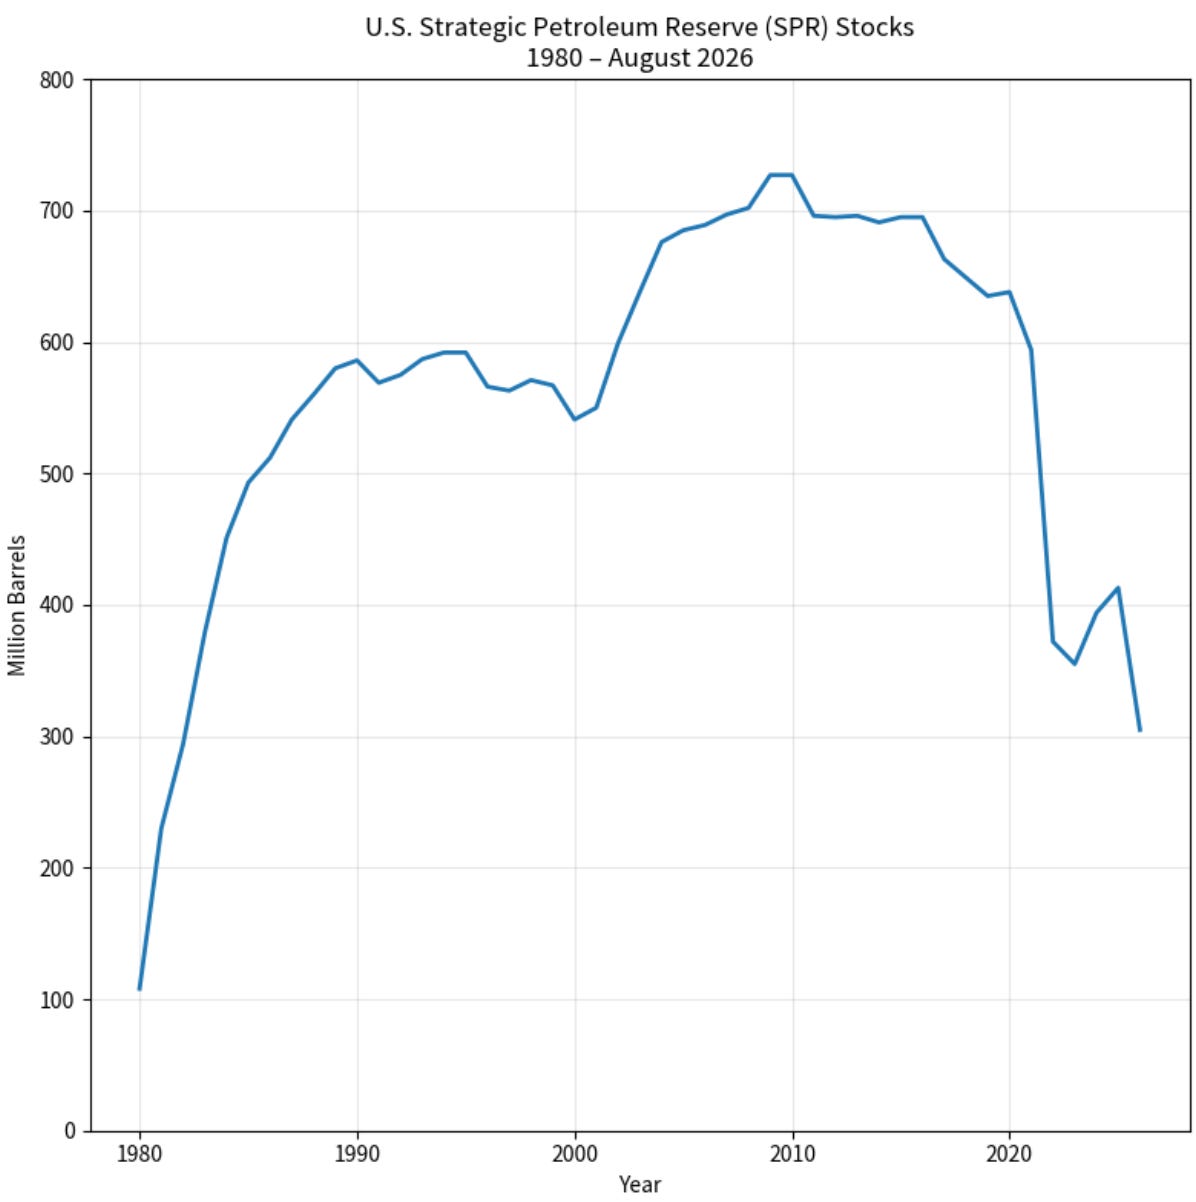
As shown above, U.S. and OECD commercial stocks also declined sharply. And now, after the coordinated IEA release of strategic reserves, the US SPR is down to 305 million barrels – the lowest level since 1983!
That’s especially salient because it was your editor who back then pushed Washington policy into the subsequent huge build-up shown in the graph below – to a peak of 720 million barrels around 2010. This build-up was based on the proposition that the SPR constituted a more efficient and sensible alternative to a high cost policy of domestic petroleum autarky that had been embraced by both parties during the 1970s.
In effect, therefore, the Donald’s pointless war on Iran has caused the remainder of 40 years of investment in efficient petroleum security to be liquidated in a matter of months – on top of the large 2021-2024 liquidation under Sleepy Joe Biden in behalf of his own re-election considerations prior to July 2024.
As also indicated above, the stock levels for refined products, especially middle distillates, have tightened even more severely. Pre-war Middle East exports supplied meaningful shares of seaborne diesel and roughly 20 percent of seaborne jet fuel. Their disruption, combined with reduced Chinese product exports and later Russian refining constraints, produced acute imbalances.
Jet-fuel prices in major hubs roughly doubled in the March-May window relative to early-2026 levels; crack spreads widened dramatically. Diesel prices rose sharply as well, at times overtaking jet fuel prices in European markets amid competing demand for scarce barrels.
Accordingly, excess inventories of both products have experienced the aforementioned 50% draw-downs already, and in some regions diesel stocks have approached multi-decade lows. By August 2026 the IEA was revising global demand and supply forecasts downward again, noting that previously available inventory buffers were rapidly depleting and that the continued Hormuz constraints were sharply curtailing product availability.
In short, the pre-February global petroleum stock cushion is largely gone. What remains is a far thinner global inventory position, elevated and volatile refined-product prices, and heightened sensitivity to any further interruption. Diesel powers freight, agriculture, construction and industry; jet fuel underpins aviation and military logistics. Both, obviously, are the lifelines of modern economies.
Further sustained restriction of Middle East product and crude flows, or renewed Iranian attacks on non-Iranian tankers attempting to exit the strait, would press these already fragile markets even harder precisely when buffers are lowest.
Again, it needs be recalled that the interaction of global stocks and market prices is not linear: When draw-downs reach critical thresholds relative to working minimums the distributor and end user demands for precautionary stocks can rise abruptly and dramatically. That, in turn, precipitously drains apparent above ground stock levels, sending prices in prompt and spot markets soaring skyward.
So if Secy Bessent thinks he has another six months of minimal flows through the SOH like that since February 28th, he surely has another think coming.
The Race and Bessent’s Overconfidence
The strategic picture is therefore a race. Iran’s blockaded economy can draw on self-sufficiency, residual oil monetization, and experience with isolation. The global economy – and the United States within it – must operate with sharply depleted commercial and strategic stocks, tight diesel and jet-fuel balances, and the constant risk that Iran will resume or intensify strikes on even the minimal levels of petroleum tanker traffic seeking to leave the Gulf.
Bessent’s forthcoming “never seen” measures and the continued naval blockade are presented as the financial equivalent of kinetic pressure—tools capable of bringing Iran to its knees before the global system feels unbearable strain. That framing, however, replicates the same analytical error that marked Epic Fury: to wit, an exaggerated estimate of American coercive leverage and an under-estimate of the target’s adaptive capacity and of collateral damage to the initiator’s own interests.
Iran’s oil trade has already migrated heavily to China and the shadow fleet; secondary sanctions on facilitators will raise costs and friction but will not instantaneously eliminate Iran’s oil revenue or force political surrender.
To the contrary, what Trumpy and Bessent are fixing to launch is an all-out Washington war on global commerce. American and third-country firms in shipping, insurance, brokerage and trade finance will absorb compliance burdens and lost business. That is to say, American business is being heavily taxed by Operation Economic Fury, and without representation or Congressional authorization to boot.
In any event, crude oil and product prices will remain elevated or spike further, feeding inflation and growth headwinds precisely when domestic political calendars are sensitive.
History offers little support for the belief that additional layers of isolation will succeed where decades of prior sanctions and six months of military pressure have not. The more probable outcome is prolonged mutual attrition in which the global diesel and jet-fuel markets, already operating with minimal buffers, reach critical stress before Iran’s domestic survival economy does.
In that contest the United States and its partners have more to lose from systemic disruption than a regime long practiced in enduring isolation has to lose from further hardship.
Epic Fury demonstrated the limits of kinetic force against a resilient adversary in a complex theater. Now, Secy Bessent’s unhinged Operation Economic Fury, launched from a position of depleted inventories and over-stretched munitions, risks demonstrating the same limits with higher systemic stakes.
The prospective announcement of “unprecedented measures” later this week will not alter the underlying arithmetic: Time favors the side that can live longer with less, and on present evidence that side is not the one whose refined-product lifelines are already stretched to the breaking point.
David Stockman was a two-term Congressman from Michigan. He was also the Director of the Office of Management and Budget under President Ronald Reagan. After leaving the White House, Stockman had a 20-year career on Wall Street. He’s the author of three books, The Triumph of Politics: Why the Reagan Revolution Failed, The Great Deformation: The Corruption of Capitalism in America, TRUMPED! A Nation on the Brink of Ruin… And How to Bring It Back, and the recently released Great Money Bubble: Protect Yourself From The Coming Inflation Storm. He also is founder of David Stockman’s Contra Corner and David Stockman’s Bubble Finance Trader.

