Showing posts sorted by date for query trump. Sort by relevance Show all posts

Thursday, October 15, 2026


Forecasters predict Democrats to take House but race for Senate hard to call


Cambridge University Press


In a forecasting special issue of PS: Political Science & Politics for the US midterm elections, all forecasters predict that the Democrats will capture the House of Representatives, but are split on who will emerge victorious in the Senate.

Published by Cambridge University Press on behalf of the American Political Science Association (APSA), the special issue includes 17 studies showcasing a range of forecasting approaches and methodologies, from traditional political economy models to controversial betting markets and AI ‘synthetic personas’.

The US Congressional Midterm elections take place on 3 November 2026. They will see all 435 seats in the House of Representatives and 35 Senate seats contested, with control of Congress potentially decided by a handful of highly competitive races.

More broadly, the collection explores how political dynamics are reshaping both elections and the tools used to understand them, and asks whether traditional models can still make accurate predictions in a time of heightened polarisation and political change.

Dr John Kenny, co-Guest Editor of the special issue from the University of Mannheim and University of Southampton, said: “Midterm elections have historically seen the president’s party lose support, driven by economic concerns and falling approval ratings.

“But the political landscape in 2026 is somewhat atypical. Increased polarisation and widespread redistricting have introduced new uncertainties, creating challenges for predicting whether this election will follow established patterns or whether it will mark a significant shift in American politics.”

Predictions for 2026

Many of the studies in the special issue have made predictions on the outcomes of the midterm elections taking place on 3 November 2026.

The verdict was unanimous on a Democrat victory in the House race, with 12 out of 12 predictions in their favour.

Predictions for the Senate race were less clear. Some forecasts are calling it for the Republicans and others are predicting a Democrat victory. All are expecting a close and contentious electoral victory.

Dr Debra Leiter, co-Guest Editor from the University of Missouri-Kansas City, said: “With such a narrow Republican majority, Democrats require only modest gains to retake the House, but the Senate will be harder to flip due to the number of Republican-held seats considered secure. Record breaking spending, open-seat contests created by a wave of retirements, and unexpected candidate choices are expected to increase competitiveness across key battleground states.

“Coupled with the unique circumstances of the 2026 election, it’s a tough one to call. Will we see a return to the fundamentals of American election forecasting, or will it prove a challenge to the widespread beliefs about American electoral behaviour?”

Highlighted papers

Roberto Cerina. ‘Polling Without People: Can Silicon Samples of CASM-Inspired LLM Personae Mimic Human Respondents in Pre-Election Polling?’

Contact: Dr Robert Cerina, University of Amsterdam
r.cerina@uva.nl

Roberto Cerina explores whether AI-generated ‘synthetic personas’ can replicate human responses in pre-election polling. Cerina created detailed large language model personas based on factors such as age, gender, education and political identity.

The model’s key innovation is its ability to simulate media consumption. Using up-to-date news feeds, personas were exposed to current events and asked how those developments influenced their political preferences. This helps to overcome a limitation of conventional AI models, whose knowledge is restricted by training cut-off dates.

The model forecasts a Democratic victory in the House, with 58.4% of the national vote and around 292 seats. Though the forecast may overestimate Democratic support, the approach offers a transparent way to understand why voters change their preferences. The paper argues AI polling could be a complement to traditional surveys, offering more frequent, granular insights into public opinion.

Thomas Gruca and Thomas Rietz. ‘Forecasting 2026 Congressional Control: A Comparison of IEM and Kalshi Prediction Markets’

Contact: Professor Thomas Rietz, University of Iowa
thomas-rietz@uiowa.edu

Thomas Gruca and Thomas Rietz examine the Iowa Electronic Market (IEM), a classic futures election market, alongside Kalshi, one of the fastest growing online betting markets. They demonstrate the stability of IEM forecasts, in contrast to the greater instability of the Kalshi markets.

In separate markets, the IEM predicts that the most likely outcomes are a Democratic House victory and a Republican Senate majority. Kalshi markets predict the most likely outcomes are a Democratic House and Senate majority, but less consistently. In combined control markets, both indicate the most likely joint outcome is a Democratic sweep. While both produce similar predictions, the IEM markets have an established history of effective and reliable forecasts that may be less prone to certain kinds of market manipulation.

The most recent IEM prediction gave a 60 per cent chance that Democrats would take the House.

Kalshi predicted similar outcomes, but the chance of the Democrats taking the House was significantly higher at close to 90 per cent.

Both markets predict a Democratic Senate.

Peter Enns, Leigh Farah, Claudia Miner, Thomas Gareau-Paquette. ‘A District-Level Forecast of the 2026 U.S. House of Representatives Midterm Elections’

Contact: Professor Peter Enns, Cornell University
pe52@cornell.edu

Peter Enns et al. recognise that observers of the US midterm elections are likely focused on who will win the majority, yet 435 separate district contests will determine political authority in the House. Their model takes key election factors in each of these districts, including this year’s unique mid-decade redistricting, candidate success measures such as fundraising, and both national level and state level vote intention, to produce a forecast model that mixes national and localised information together in a new and effective way.

Based on 10,000 simulations using data from 100 days before the election, the forecast gives Democrats a 90 per cent chance of taking the House, with an expected total of 235 seats.

Charles Tien and Michael Lewis-Beck. ‘Political economy forecasts: the 2026 midterms’

Contact: Professor Charles Tien, Hunter College, CUNY
ctien@hunter.cuny.edu

Professor Michael Lewis-Beck, University of Iowa
michael-lewis-beck@uiowa.edu

Charles Tien and Mike Lewis-Beck unveil a new forecast of the 2026 elections based on the long-running Political Economy Model. The model draws on three key predictors: economic performance, presidential approval ratings and the historical impact of midterm elections. The paper argues that voters reward governing parties when conditions are favourable, and punish them when they are not.

With President Donald Trump’s approval rating at around 35%, the model predicts Republicans will lose 33 House seats and lose their narrow majority. It also predicts the Democrats will pick up enough seats to retake the Senate. The forecast reflects the powerful historical tendency for presidents’ parties to suffer losses at midterms.

Stephen Quinlan and Michael Lewis-Beck: ‘Demslide or Republican resilience? A political history forecast of the 2026 US congressional elections’

Contact: Stephen Quinlan  
stephenpfquinlanwork@gmail.com

Professor Michael Lewis-Beck, University of Iowa
michael-lewis-beck@uiowa.edu

Drawing on decades of US political history, Stephen Quinlan and Mike Lewis-Beck have developed a forecasting model that examines the structural and historical conditions that have consistently influenced election outcomes over time. When one party controls the presidency, Senate and House simultaneously, voters have tended to impose an electoral penalty on the governing party.

With Republicans currently controlling all three branches, the model suggests conditions are favourable for Democratic gains. However, increasing political polarisation and a declining number of competitive House districts may limit gains. The researchers' central forecast projects Democrats winning 231 House seats and 50 Senate seats, giving them a 78% chance of recapturing the House and a 66% chance of winning control of the Senate.

Jack Rametta and Christopher Hare: ‘How Model Choice Obscures Forecast Uncertainty: The Rashomon Effect and the 2026 Senate’

Contact: Dr Christopher Hare, UC Davis
cdhare@ucdavis.edu

Jack Rametta and Christopher Hare have developed a forecasting model to predict US Senate election outcomes that reflects the growing nationalisation of congressional elections, where local candidate appeal and the incumbency advantage are increasingly outweighed by broader political forces such as presidential approval, partisanship and economic conditions.

The researchers argue that elections that were once shaped more heavily by state-level dynamics are now closely tied to voters’ perceptions of national political performance. As a result, even well-regarded incumbents can struggle to withstand unfavourable national trends.

As of late September, the forecast predicts Democrats will take 50 seats in the Senate, but given the high uncertainty, the forecast ranges from 45 to 56 seats.  Democrats are slightly more likely than not to secure a Senate majority, though the race remains highly competitive.

Olivia Quinn, Amanda Brush and Eric R. A. N. Smith: ‘Updating the Fundamentals: Forecasting the 2026 Midterm Election Post Gallup’

Contact: Dr Olivia Quinn, UC Santa Barbara
oquinn@ucsb.edu

The recent discontinuation of Gallup’s Presidential Approval polls, an 88-year tradition, poses a problem for many election forecasting models. Olivia Quinn, Amanda Brush and Eric R. A. N Smith show that these models can continue without it. They develop a proxy measure from RealClearPolitics’ poll average and use it to predict what will happen on election night.

As of the most recent quarter, their Congressional seat change forecast predicts sizable Democratic gains in both chambers, with Republicans predicted to lose nine seats in the Senate and 42 seats in the House.

Notes to Editors:

For general enquiries about the issue, please contact:

Dr Matt Midgley, Cambridge University Press & Assessment

+44 (0)1223 342979

matthew.midgley@cambridge.org


To speak to the guest editors, please contact:


Dr Debra Leiter, University of Missouri-Kansas City
leiterd@umkc.edu


Dr John Kenny, University of Mannheim/University of Southampton
J.P.Kenny@soton.ac.uk


Publication:

The Special Issue Forecasting the 2026 US Midterm Elections of PS: Political Science & Politics is published on behalf of the American Political Science Association by Cambridge University Press.

All papers in the special issue will be available here when published: https://www.cambridge.org/core/journals/ps-political-science-and-politics/accepted-manuscripts

Studies listed below and highlighted in this press release are strictly embargoed until Thursday 15 October 2026 at 00:01 UK time / 14 October at 19:01 US Eastern Time.

About Cambridge University Press  
Cambridge University Press is the academic and Bibles publisher of Cambridge University Press & Assessment. It publishes books and journals, serving customers in higher education through research, education products and services. It is part of the University of Cambridge, delivering trusted research and learning materials that spread knowledge, spark curiosity and aid understanding of the world we live in.  
cambridge.org/universitypress   

About American Political Science Association (APSA)
Founded in 1903, the American Political Science Association is the leading professional organization for the study of political science and serves more than 11,000 members in more than 80 countries. With a range of programs and services for individuals, departments, and institutions, APSA brings together political scientists from all fields of inquiry, regions, and occupational endeavors within and outside academe to deepen our understanding of politics, democracy, and citizenship throughout the world.


 

Ukraine to Resume Russian Oil Refinery Strikes After Failed Energy Ceasefire


Ukraine will resume drone strikes on Russian refineries after Russia kept hitting energy infrastructure and killing civilians in Ukraine despite U.S. President Trump’s claim of an “energy ceasefire”, Ukrainian President Volodymyr Zelenskyy told the Financial Times.

In the interview in London, the Ukrainian President told FT he had ordered a pause in strikes on Russian refineries for three days to comply with the U.S. wishes. Meanwhile, Russia continued to strike Ukraine’s energy infrastructure and kill civilians, Zelenskyy said.

“The block [on attacking refineries] is out. We’re done,” the Ukrainian President told FT, while also criticizing the U.S. eagerness to agree business deals with Russia, including in the energy sector.  

Zelenskyy has for days insisted that Russia isn’t sticking to any “energy truce” and continues to target with ballistic missiles energy infrastructure—“the very infrastructure covered by the ceasefire announced by the American President.”

A strike early on Wednesday on Ukraine’s energy and critical infrastructure in Kyiv, the Kyiv region, and Kharkiv “was entirely deliberate and demonstrative in its scale – Russia has never before shown such ostentatious disrespect toward the United States,” Zelenskyy posted on X yesterday.

In the interview with FT, the Ukrainian President also expressed his frustration with the “dangerous” withdrawal of U.S. intelligence and the simultaneous weakening of Elon Musk’s Starlink satellite communications across Ukraine.

President Trump has pressured Zelenskyy to stop hitting Russian oil refineries, because part of the global diesel crunch is the lack of Russian exports. The other major driver of record-high diesel prices and the highest-ever October gasoline prices in the U.S. is, of course, the war in Iran President Trump chose to engage in early this year.

Early on Thursday, crude oil prices fell by about 1% in Asian trading as reports emerged that President Trump was considering lifting sanctions on tankers used to transport oil and fuels from Venezuela, Russia, and Iran in a bid to ease a deepening tanker crunch.

By Tsvetana Paraskova for Oilprice.com

Trump Announces $80 Billion Taiwan - Alaska LNG Deal

  • Trump announces a potential $70–80 billion Taiwan LNG deal, covering 30% of Alaska LNG's planned output over 20 years.

  • South Korea disputes its proposed $50–54 billion investment, insisting participation depends on commercial viability.

  • Alaska LNG offers a route around Hormuz, but enormous development costs and unfinalized agreements threaten the project's future.

President Donald Trump has announced a massive new energy agreement with Taiwan, claiming the island will purchase between $70 billion and $80 billion worth of liquefied natural gas from Alaska over the next two decades, as Asian importers scramble to secure supplies beyond the increasingly dangerous Strait of Hormuz.

In a Truth Social post on Wednesday, Trump said Taiwan had committed to purchasing 30% of the planned Alaska LNG project's output for 20 years, alongside a $4.4 billion equity investment.

The president described the arrangement as the largest LNG offtake agreement in history, arguing that the commitments would guarantee the project's success.

Taiwan's Ministry of Economic Affairs subsequently confirmed plans to purchase approximately 6 million metric tons of LNG annually and invest up to $4.4 billion in the development.

However, Taipei stopped short of confirming a binding agreement, emphasizing that investment arrangements, ownership stakes and commercial terms remain subject to further negotiations.

Deliveries could begin as early as 2032, provided construction proceeds as planned.

The proposed Alaska LNG project, led by Glenfarne Group, would transport natural gas from Alaska's North Slope through an approximately 800-mile pipeline to a liquefaction terminal on the state's southern coast, with planned export capacity of 20 million metric tons annually.

Its geographical advantage has become increasingly attractive following the Iran war, which has severely disrupted LNG shipments through the Strait of Hormuz. Alaska offers Asian buyers a direct Pacific shipping route that avoids the Middle Eastern chokepoint entirely.

As Oilprice.com previously reported, the conflict has revived interest in the long-delayed project, with Asian importers increasingly prioritizing supply security over cost.

However, Alaska’s costly pipeline and difficult terrain threaten to outweigh its shipping advantage, with capital costs approaching $2.7 billion per million tonnes of annual LNG capacity. An October 7 article from Oilprice.com's Natalia Katona concludes that geographical challenges may erode the project's competitiveness in a world where LNG supply is expected to grow throughout the late 2020s and early 2030s.

Earlier this month, Trump announced that South Korea would invest approximately $50 billion to $54 billion in Alaska LNG as part of a broader bilateral investment agreement.

Seoul has since challenged that characterization.

South Korea's industry minister, Kim Jung-kwan, said the country had not committed to the investment, stressing that participation would depend on commercial viability and compliance with domestic procedures, according to Reuters.

The uncertainty is significant given the project's estimated $44 billion to $55 billion price tag.

Oilprice.com Tsvetana Paraskova highlighted earlier this month that Alaska LNG's development costs could exceed those of competing U.S. Gulf Coast projects by more than twofold on a capacity-adjusted basis.

For Taiwan and South Korea, the attraction of bypassing Hormuz is undeniable. Whether that geopolitical advantage justifies tens of billions in additional investment remains the central question.

For now, Trump's ambitious Alaska LNG vision has growing political momentum, but its commercial future still hinges on binding supply agreements, committed financing and final investment decisions.

By Tom Kool for Oilprice.com


Taiwan Plans to Invest $4.4B in Alaska LNG, Subject to Negotiations

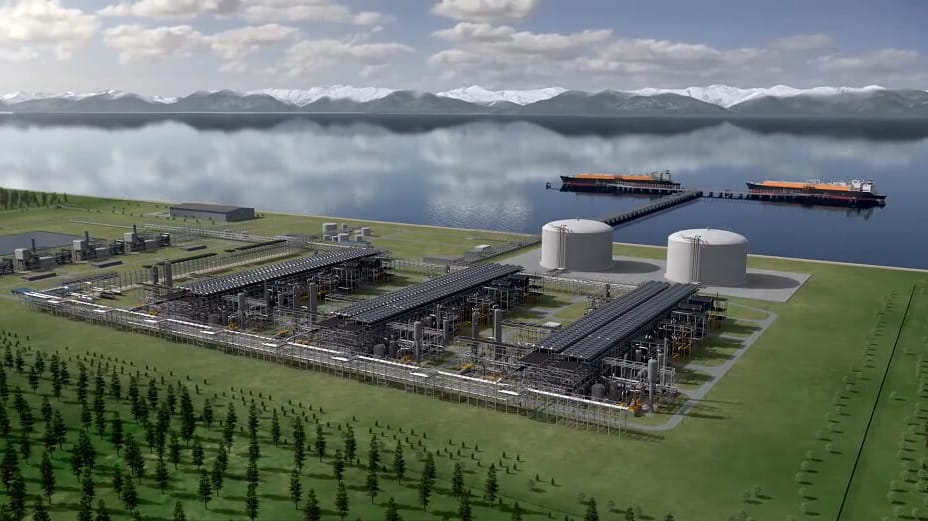
The proposed Alaska LNG liquefaction plant on Cook Inlet (Alaska LNG)

On Wednesday, Taiwan's government confirmed that it currently plans to buy six million tonnes per annum of LNG from the Alaska LNG megaproject, and it intends to make a $4.4 billion investment in the construction of the system, subject to further negotiations. 

In a statement on his social media platform on Wednesday, President Donald Trump confirmed that Taiwan had agreed to an "offtake commitment" equaling 30 percent of the plant's output "because this is now a U.S. federal government project." New York-based investment company Glenfarne Group and the state-owned Alaska Gasline Development Corporation are the project's sole owners, holding equity stakes of 75 percent and 25 percent respectively.

Taiwan's energy ministry couched its commitment in terms of an ongoing negotiating process, pledging "an estimated maximum" investment amount only after further study and budgeting. "Specific investment arrangements, shareholding ratios, and related conditions will be handled according to subsequent negotiations and commercial contract procedures," the ministry said. 

Alaska LNG is a longstanding proposal for an infrastructure network to pipe abundant North Slope gas resources across the state to Cook Inlet for liquefaction and export. It would require construction of an 800-mile line connecting gas fields on the Artic tundra to an LNG plant rated at 20 million tonnes per annum. 

At one time, Alaska LNG had support from BP, ExxonMobil and ConocoPhillips and was advancing steadily as a private-sector venture. All three oil majors backed out in 2016 following an independent assessment of the project's economics. At present, a New York-based investment company and the state-owned Alaska Gasline Development Corporation own the equity in Alaska LNG.

With the need to construct a $9 billion gas treatment plant at the Arctic northern side, then build an 800-mile overland supply pipeline through rugged wilderness, the megaproject is expected to cost $45-55 billion for 20 mtpa of capacity. This works out to as much as $2.7 billion per mtpa, much higher than the $1.6 billion per mtpa capex cost for the LNG Canada Phase 2 project in Kitimat, British Columbia. About 900 nautical miles apart, the two sites are natural competitors: they target the same East Asian market, and at similar scale. Two weeks ago, LNG Canada got the green light from private investors for its $23 billion Phase 2 expansion, which will double its capacity to 28 mtpa. 

The Trump administration has been asking Asian allies to make comparable investments in Alaska LNG, and President Donald Trump announced a $50 billion South Korean commitment to the project last week. South Korea's energy ministry responded that a complete commercial feasibility study would have to be done before any final investment decision. 

STATE CAPITALI$M

White House Turns to Korean War-Era Law as Diesel Prices Stay Above $6


  • Trump invokes the Defense Production Act to expand Delek’s 74,000-bpd Texas refinery amid record-high U.S. fuel prices.

  • Gasoline remains above $4.30 per gallon and diesel near $6.30, with refinery expansion unlikely to provide relief before the midterms.

  • The U.S.-Russia diesel deal fails to calm markets, as global supply shortages push wholesale diesel prices toward $200 per barrel.

The United States has used a 1950 authority to help boost fuel production at a small Texas refinery, Vice President JD Vance said on Tuesday, as the Trump Administration is running out of levers to lower record-high fuel prices.

“I am pleased to announce that the Trump administration, working with the refinery at Delek, has used the Defense Production Act and we’re going to expand the refinery right here in Tyler, Texas,” Vance said at a political rally in Texas.

“We want millions of gallons of commercial-grade and military-spec fuel to come out of this refinery, in addition to what it’s already producing,” the Vice President said.

The Defense Production Act, originally enacted in 1950 in response to the start of the Korean War, is a federal law granting broad authority to the President to direct private businesses to produce critical materials and services for national defense and emergency preparedness.

With the midterm elections looming, the Trump Administration has entertained in recent weeks various ideas to increase fuel availability in the United States. From a ban on diesel exports (now ruled out) to a deal with Vladimir Putin for Russian diesel deliveries (actually announced), no option has been off limits for the Administration facing record-high diesel prices and gasoline prices at their highest level for autumn ever.

At the Texas rally, VP Vance did not provide any timelines or volumes for the “millions of gallons” of additional fuel Delek’s 74,000-barrel-per-day refinery would produce. It is uncertain how much time the refinery expansion would take or if the Defense Production Act would be extended to other refineries in the United States.

It’s certain that additional output is unlikely to hit the market within three weeks and lower fuel prices ahead of the midterm elections on November 3.

Despite slight declines in recent days, gasoline and diesel prices remain elevated. The U.S. national average price of a gallon of regular gasoline set a record for October, and this has been the first October ever to see the national average above $4 per gallon. As of Tuesday, the national average was $4.34 per gallon.

The national diesel average was at $6.28 a gallon, lower than $6.31 a week ago, but so much more than $3.65 at this time last year.

Diesel prices will remain high and above $6 per gallon for quite some time, analysts say, noting that the deal with Russia for diesel supply wouldn’t make much (or any) difference.

The global diesel market is exceptionally tight because of the Middle East conflict, with too little fuel making it out of the Strait of Hormuz, as well as a lack of supply from Russia, whose refineries are struggling to produce fuel amid Ukrainian drone attacks.

The U.S.-Russia “diesel deal” – if it is executed at all – is for 35.76 million barrels in total—volumes equivalent to about 10 days of U.S. domestic diesel demand or just over one single day of global demand, analysts say.

After an initial decline in wholesale diesel prices on Friday, diesel futures prices spiked again this week, with ULSD in New York and gasoil in London both rising to trade around $200 per barrel on Tuesday, Ole Hansen, Head of Commodity Strategy at Saxo Bank, said.

Tom Kloza, chief energy advisor at Gulf Oil, noted on Tuesday, “Absolutely stunning price spikes in wholesale diesel today…Market clearly not believing that Russian oil is on the way.”

The U.S. retail diesel price record of $6.53 per gallon could be topped by the midterms, according to Kloza.

Patrick De Haan, head of petroleum analysis at GasBuddy, said on Tuesday, “wholesale diesel prices not blinking over Russia/US ‘deal’”, and that “$6/gal diesel may be here to stay for now- truckers and farmers not going to see any relief anytime soon.”

By Tsvetana Paraskova for Oilprice.com


Trump says ‘massive’ oil, gas, mineral exploration set to begin in Greenland


Credit: Gage Skidmore | Flickr, under licence CC BY-SA 2.0.

US President Donald Trump said on Wednesday that “massive oil, gas and mineral exploration”was set to begin on Greenland, a contentious statement on a territory that has resisted his efforts to control it and has banned new drilling for crude.

Trump described the Danish Arctic island which is run by a semi-autonomous government as “our new and beautiful Greenland” in a social media post that hailed what he said were US gains from a security deal signed in September.

The Greenlandic prime minister’s office declined to comment on Trump’s statement.

The Danish foreign ministry and Greenland’s ministry of mineral resources did not immediately respond to requests for comment.

Trump hails US security gains

Greenland has been caught up in a confrontation with Trump who has been saying since 2019 the US should buy or take the strategically located and mineral-rich island for security reasons. On several occasions, he refused to rule out force.

Along with Denmark, the US and Greenland reached an agreement last month to allow the US to boost its military presence on the island – a deal that had appeared to settle the standoff.

The agreement did not allocate any rights for mining or drilling.

“Massive Oil, Gas, and Mineral Exploration is getting ready to begin,” Trump wrote in a post on his Truth Social platform.

“There are Experts that are saying that the amount of easily available Oil is far greater than that of almost any land, anywhere in the World,” he added without naming any specific deals or specific development.

Greenland banned uranium mining in its territory along with all future exploration of oil in 2021.

The government has said it is reviewing whether a Texas firm, Greenland Energy, can use permits predating that prohibition.

The company said in August this year it had plans to drill for oil in 2027 at an untested basin on Greenland’s east coast, although it lacked its own permit to do so. The previous owner, ARCO, spent heavily on seismic work in the 1970s but never drilled.

Independent Danish security policy advisor Jacob Kaarsbo said Trump’s comments could be seen as a sign that his desire to control Greenland remained unchanged.

“It is extremely dangerous to view this agreement between the Trump administration and Denmark as something that has altered Trump’s intentions,” he said.

The 10-page deal between the US, Denmark and Greenland paved the way for two new military bases and Trump’s “Golden Dome” missile defence system, while reaffirming Danish sovereignty and Greenlanders’ right to self-determination.

“Any future attack on the United States will have to come across Greenland, where our Defense will routinely knock down drones, missiles, or any other form of weapon not yet even conceived,” Trump said in his post on Wednesday.

“It gives us time, location, and sightline, like nowhere else in the World!” he added.

(Reporting by Louise Rasmussen in Copenhagen and Rhea Rose Abraham in Bengaluru; Editing by Christian Schmollinger and Andrew Heavens)


Op-Ed: Aluminum’s calm belies lingering supply-chain stress


Emirates Global Aluminium is the world’s largest ‘premium aluminum’ producer. Credit: Emirates Global Aluminium | LinkedIn

 (The opinions expressed here are those of Andy Home, a columnist for Reuters)

 Iranian missile attacks on Gulf smelters and the blocking of the Strait of Hormuz have knocked out almost 3 million metric tons of aluminium production capacity. Yet, eight months on, the market is seemingly unconcerned.

Indeed, London Metal Exchange (LME) three-month aluminium CMAL3 is now trading just above $3,000 per ton, which is where it was in early February before the US and Israel unleashed Operation Epic Fury against Iran.

Traders are betting that a combination of rising output in Indonesia and higher product exports from China can tide things over until the Gulf smelters are repaired and shipping fully resumes in the Strait of Hormuz.

The surface calm, however, masks lingering stress in a physical supply chain that is still reeling from the unprecedented disruption.

Plugging the gaps

Gulf production of primary aluminium slumped by an annualized 2.8 million tons between February and May, according to the International Aluminium Institute.

The collapse reflected the forced shutdown of Emirates Global Aluminium’s Al-Taweelah smelter and damage to Aluminium Bahrain’s facility, as well as logistics problems at other Gulf operators.

Regional production has since been creeping higher as both plants undergo repairs and ramp production back up, but the August run-rate of 3.5 million tons annualised was still 2.6 million tons below pre-hostility levels.

China and Indonesia have stepped in to plug the gap.

China’s exports of primary metal are constrained by a hefty 30% export duty, but outbound volumes of alloy doubled year-on-year to 349,000 tons in the January to August period.

Exports of semi-finished products such as aluminium plate, sheet and strip surged by 774,000 tons to 4.46 million tons over the same period.

Indonesia’s new Chinese-owned smelters are also ramping up at speed. The country exported 114,000 tons of primary metal in July, a fresh monthly record.

Around half of last year’s Indonesian aluminium exports went to China but shipments since the Iran war have been dispersed across Asia, Europe and even the US.

Physical stress

Improved availability in Asia has caused physical premiums to ease from their June highs.

Japanese buyers have negotiated a fourth-quarter delivery premium of $255 per ton over the LME cash price, which marks a 35% decline from the previous quarter.

However, that’s still higher than the $200-per-ton premium that was trading at the start of the Iran war, attesting to continued tension even in this relatively well-supplied part of the market.

European buyers are paying significantly more for their physical metal.

The CME European duty-paid premium EPDc1 is trading at $559 per ton over LME cash, double the level at the end of February.

US buyers, of course, are paying more than anyone else for their aluminium with the US Midwest premium trading at an elevated $2,312 per ton over LME cash, though this is as much about President Donald Trump’s 50% import tariffs as anything else.

Low inventory

Elevated premiums are sucking available metal into the physical supply chain, leaving LME stocks at multi-year lows.

Registered inventory of 238,625 tons is the lowest level this century. Most of what remains is Russian metal, which reduces its appeal to most Western buyers.

LME off-warrant inventory has also been steadily shrinking since February and now totals just 73,509 tons, which is the lowest reading since the LME introduced this category of stocks reporting in 2020.

Time-spreads have eased considerably since June, when the cash premium over three-month metal CMAL0-3 jumped to over $100 per ton.

But there is lingering tightness in the front part of the curve. After a period of mild contango, cash has just returned to a small premium over three-month metal again.

Time-spread tension is likely to remain a feature of the London market as long as physical premiums remain so high.

The aluminium market has proved highly resilient to the sudden loss of so much production, but the stress lines are still there beneath the calm surface.

(Writing by Andy Home; Editing by Marguerita Choy)


Russian aluminium’s share of available LME stocks almost 100% in September

Aluminum factory in Russia. (Reference image by uc_rusal_photo_gallery, Wikimedia Commons.)

The share of available Russian-origin aluminium stocks in London Metal Exchange warehouses rose to almost 100% in September from 95% in August, exchange data showed on Wednesday, leaving only a tiny amount of Indian metal as an alternative.

Total available, or on-warrant, aluminium inventories 6.5% to 226,675 metric tons at the end of last month, the lowest since March 2025, as conflict in the Middle East tightens global supply.

Available Russian aluminium stocks fell by 3,425 tons to 226,625 tons last month, but their share of total rose to 99.98% as Indian stocks, the only other origin material available, dropped by 12,400 tons to just 50 tons.

Many traders have shunned Russian metal even though material produced before April 13, 2024, remains eligible for trading. Aluminium made in Russia after that date was barred from the LME warehousing system to comply with Western sanctions.

“We’ve got to a place where I think the market has accepted that the (aluminium) stocks are where they are at this very low level and the quantity that is in there isn’t really wanted,” StoneX senior metals analyst Natalie Scott-Gray said on a webinar on Wednesday.

“It’s going to take time for these stocks actually to start to increase. If we look at even the queues for materials or cancelled warrants, there’s not a lot of orders for it.”

Meanwhile, the share of Chinese-made copper in available LME copper stocks fell to 28% at the end of September from 44% the previous month.

Total available copper stocks rose to 131,450 tons from 111,175 tons at the end of August as a drop in the arbitrage to ship metal to the US COMEX exchange incentivised more deliveries on to the LME.

The volume of available Chinese copper fell by 12,125 tons to 37,275 tons, while volumes from Chile and Democratic Republic of Congo increased.

The share of Chinese-origin nickel edged down to 69% of available LME stocks at the end of September from 70% the prior month.

(Reporting by Tom Daly; Editing by Alexander Smith)