Showing posts sorted by date for query PEAK OIL. Sort by relevance Show all posts

Saturday, September 19, 2026


India's clean-energy surge holds power-sector emissions flat for two years

India's clean-energy surge holds power-sector emissions flat for two years
Coal-fired generation has not grown over a two-year stretch for the first time in half a century, and clean power has covered the whole of India's demand growth. / bne IntelliNewsFacebook
By Ben Aris in Berlin September 18, 2026

Carbon dioxide emissions from India's power sector were no higher in the first half of 2026 than they were two years earlier, as a record expansion of solar and wind absorbed the entire increase in electricity demand, according to analysis for Carbon Brief published on September 17.

It is the first time in more than 50 years that India's coal-fired power generation has failed to grow over a two-year period while electricity demand was still rising, wrote Lauri Myllyvirta, lead analyst at the Centre for Research on Energy and Clean Air (CREA), and Anubha Aggarwal, the think-tank's India analyst.

The flat line hides a split. Power-sector emissions fell 2.2% year on year in the first half of 2025 and then rose 2.3% in the same period of 2026, leaving the two-year change at zero. Emissions from oil and gas consumption fell 7% year on year, extending a decline that began last year. But steel and cement emissions grew 8% and now account for 23% of all of India's CO2.

The net result is that India's total emissions still rose, by 3.7% year on year in the first half of 2026 - the clean-energy build-out has neutralised the power sector without yet touching heavy industry.

The finding extends a trend bne IntelliNews reported in January, when CREA's previous assessment found coal-fired generation falling in India for the first time in five decades.

Clean power covers all the growth

India's total power generation rose 7% between the first half of 2024 and the first half of 2026, an increase of 63 terawatt hours (TWh) - roughly the entire annual electricity consumption of Switzerland or Singapore.

Every unit of that was covered by non-fossil sources, and then some. Solar generation grew by 44TWh over the two years, wind by 13TWh, hydro by 8TWh and nuclear by 7TWh, a combined 70TWh - more than the net increase in demand.

Behind the output came the capacity: 77GW of new solar, 11GW of wind, 5GW of hydro and 0.6GW of nuclear in two years. Solar dominates, but the other non-fossil sources together still delivered 40% of the overall rise in generation. For scale, China's combined nuclear, wind and solar output rose by 485TWh in 2025 alone.

India added a record 52,537 MW of generating capacity in FY26, with renewables leading the expansion, and analysts have argued since the spring that the country's renewable surge has hit critical mass.

CREA's figures suggest the trend has further to run: output from newly commissioned clean capacity has run ahead of average demand growth for 18 months.

Fossil-fuel generators, meanwhile, added 8.5GW of new coal capacity into a market that was not growing, cutting running hours across the fleet and pushing costs onto electricity consumers.

One reason demand rose at all this year was weather. El Nino delayed the monsoon and intensified heatwaves, driving up cooling load - the same dynamic that saw India lean harder on coal in May.

Gujarat leads, the states diverge

The decline in fossil-fuel generation was concentrated in a handful of states rather than spread across the country.

Gujarat recorded both the largest fall in fossil generation and the largest expansion of clean power. Rajasthan and Tamil Nadu came next on clean-power growth and also cut fossil output.

Several other states - Madhya Pradesh, West Bengal and Punjab - burned less coal only because they imported more power from elsewhere, not because they built clean capacity.

Karnataka and Andhra Pradesh added clean generation faster than their own demand grew, which is what kept national fossil generation flat, but exported much of the surplus and saw their own fossil output rise. Maharashtra and Telangana, the two states with the biggest increases in demand, came close to matching that growth with clean power.

Oil and gas fall for a second year

India's oil consumption fell 1.3% year on year in the first half of 2026, a slight acceleration on the 0.7% decline of a year earlier, and the second consecutive annual fall after half a century of near-continuous growth interrupted only by Covid-19.

Transport fuels are not the reason. Diesel consumption growth accelerated to 4.1% from 1.8%, helped by heavier freight movements and diesel irrigation during the delayed monsoon, while petrol returned to growth at 6.9% after a flat 2025. A jump in ethanol blending took a full percentage point off petrol demand growth; India hit its 20% blending target in 2025-26, five years early.

The decline came from everything else. Liquefied petroleum gas (LPG) consumption contracted 7% after growing 5.7% a year earlier, amid the disruption to global LPG markets that followed the Hormuz crisis. Petcoke fell 9.9%, more than reversing a 9.3% rise, as higher prices pushed cement makers back to coal. Naphtha demand shrank as import prices nearly doubled and domestic prices rose about 60%, forcing petrochemical plants to cut operating rates. Bitumen stayed weak on slow road construction.

Aviation fuel growth slowed to 2% from 5%, coinciding with the airspace closures, cancellations and higher fuel prices that followed the closure of the Strait of Hormuz, a shock that exposed the vulnerability of global trade far beyond the oil price.

Some of the substitution went the wrong way for air quality. Higher light diesel oil prices and the LPG shortage pushed industrial users back to furnace oil in boilers and heaters, and state governments including Delhi NCR, Rajasthan, Tamil Nadu, Gujarat and Maharashtra temporarily lifted bans on dirtier fuels. The government authorised the hospitality industry to burn coal, refuse-derived pellets, biomass and kerosene for a month when gas ran short in March and April.

Flat oil and gas demand did have one benefit: it blunted the impact of the Hormuz crisis on India's trade balance. Imported coal use for power fell 38% over the two years and gas use 35%, cutting the country's exposure just as prices spiked.

Steel and cement pull the other way

Steel output grew 8% year on year in the first half of 2026 and cement 9%, supported by investment in real estate, particularly in the second quarter. Steel consumption grew faster than production, implying that inventories built up last year were run down.

Margins were squeezed throughout by expensive imported coking coal and the higher freight costs left by the Hormuz crisis. Cement prices are expected to return to levels last seen in the 2021-22 financial year, when Russia's gas cuts to Europe drove fossil-fuel prices sharply higher.

Outside power, steel and cement, coal consumption growth accelerated to 14% in the first half of 2026 from 3% a year earlier, as the LPG shortage prompted a switch to coal.

The underlying problem, CREA argues, is that Indian industry barely uses electricity. Electricity accounted for 17% of industrial energy consumption in 2023, the second-lowest share in the G20, below the world average on both level and rate of improvement. Until that changes, every increase in industrial output translates directly into more fossil-fuel burning.

Coal investment carries on regardless

None of this has slowed capital spending across the coal supply chain. Some 43GW of coal-fired capacity was under construction at the end of June, justified by the need to meet rising peak loads even as solar covers daytime peaks and storage begins to cover the evening.

Outside the power sector, the government wants capacity to process 100mn tonnes of coal a year through gasification within four years, to make fertiliser and plastics feedstock domestically. The technology is barely established in India: the only operational use is at Jindal Steel, which is reported to be using syngas in steelmaking.

In January the government designated domestic coking coal a "critical and strategic mineral", and miners and steelmakers are reported to be planning new washeries so it can be blended with imported coal. New coal mines are also planned.

Taken together, CREA warns, coal gasification, domestic coking coal and new mining capacity could lock coal into Indian industry for decades - even as India separately targets a 25% cut in CO2 per tonne of steel by 2025-26, mainly by reducing coal-based steelmaking.

What has to happen next

Keeping the clean-energy expansion going will require more than turbines and panels.

Transmission is the immediate bottleneck. Renewable projects totalling 5.3GW missed completion deadlines and are paying penalties to the grid operator to hold onto network access. Curtailment - clean power generated but wasted because the network cannot take it - has become a live issue, particularly for projects that depend on interstate transmission.

Coal plants also need to become more flexible so they can ramp down when renewable output is high. A flexibility plan for the coal fleet has been stuck for more than a year in regulatory bottlenecks, which is itself contributing to curtailment.

Storage is the other half of the answer. The National Electricity Plan calls for 82 gigawatt hours (GWh) of storage by 2026-27 and 411GWh by 2031-32. As of May 2026 the government had tendered around 272GWh, including 142GWh of pumped hydro and 133GWh of batteries, against installed capacity of just 7.5GWh of batteries and around 60GWh of pumped hydro. India is not alone in the turn to water batteries: global pumped storage passed 200GW last year.

The Central Electricity Authority has proposed that from June 2027 all new government-owned solar and wind projects carry mandatory two-hour battery storage - a policy China ran until early 2025 before scrapping it in favour of market-based approaches.

The direction of travel in the power sector is now clear enough. What CREA's numbers show is that India's emissions problem has moved: it is no longer mainly about electricity, and increasingly about a heavy industry that still runs on coa

Wednesday, September 16, 2026


OOCL Sends First Ship Through Suez as Canal Highlights Growth

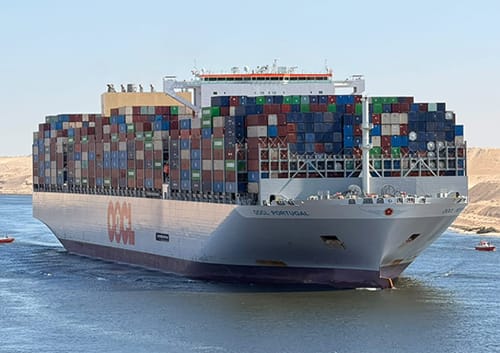
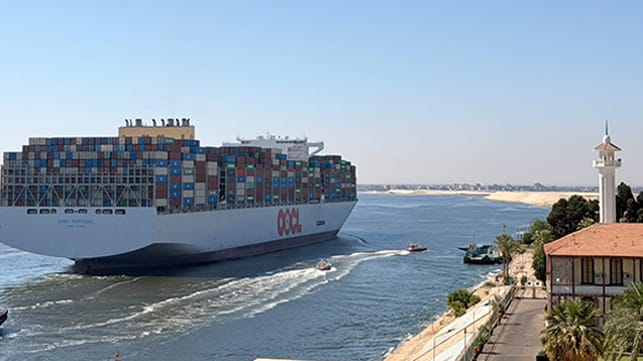
OOCL Portugal container vessel in the Suez Canal
OOCL Portugal marked the return of OOCL and Cosco to the Suez Canal (SCA)

Published Sep 16, 2026 4:22 PM by The Maritime Executive


Orient Overseas Container Line (OOCL) joined the growing number of container lines returning to the Suez Canal, sending its first ultra-large vessel through the canal as part of Cosco’s strategy to resume some of its normal routes for Cosco and OOCL vessels. It comes as the Suez Canal Authority highlights continued growth despite the latest military moves by the Houthis at the southern terminus of the Red Sea.

The OOCL Portugal (225,000 dwt) made the transit on Wednesday, September 16, coming from Belgium and the Mediterranean on its way to China. The vessel, which has a capacity of 24,188 TEU, was in the convoy from the north, representing OOCL’s first return to the Suez Canal and the first for a Cosco-controlled ship since "the tensions in the Red Sea and Bab al-Mandeb," the Suez Canal Authority emphasized.

The OOCL Portugal was one of 39 ships making the transit on Wednesday, which remains at levels still well below the Suez Canal’s peak before the start of the attacks by the Houthis. A day earlier, on September 15, the Suez Canal Authority reported that 45 ships transited the canal. 


OOCL's ultra-large vessel was in the convoy coming from the north toward the Red Sea (SCA)


Wednesday’s transits, however, also appear to have included vessels from MSC Mediterranean Shipping Company and CMA CGM. The Suez Canal Authority highlights that both carriers, along with Maersk and Hapag-Lloyd, have restored services. While not mentioned by name, pictures also showed a Wan Hai container vessel in the Suez Canal.

Cosco is reported to be restoring several routes to the Suez Canal, including shared services with CMA CGM. Well-known industry commentator Lars Jensen, however, points out that the first are mostly on the backhaul and notes that Evergreen, which is also part of the alliance, is not yet returning to the Suez Canal.

Maersk and Hapag-Lloyd also reported at the beginning of the week that four more routes that they share in the Gemini Cooperation would be restored to the Suez Canal - Red Sea corridor. The lines had already moved two routes back and plan to continue restoring routes as long as the region remains stable. 

The restorations are continuing despite the Houthis seizing the port of Mocha at the end of last week and an island in the Red Sea, to gain greater control near the Bab el-Mandeb. The Houthis, however, continue to say they are only banning shipping linked to Saudi Arabia.

The Suez Canal Authority further highlights that volume in the canal in the first eight months of 2026 surpassed 72 million tons, a 54 percent increase from 46.7 million tons in the same period of 2025. 

The recent restoration is reversing the declines the canal experienced in 2025. For the full year, it reported that 12,758 vessels made the transit, which was down 3.4 percent from 2024. Tonnage also declined by 0.5 percent, but cargo tonnage rose 1.4 percent. The canal said the lowest month was February, with the strongest in November. Oil tankers comprised the largest portion of the vessels using the Suez Canal, followed by bulkers. Natural gas carriers showed the largest percent increase, while 1,840 containerships made the transit in 2025.

The Suez Canal Authority continues its marketing and highlights further improvements in its operations as it seeks to encourage the return of more vessels to their pre-war routes.

U.S. Diesel Prices on Track for Record Year

  • U.S. diesel reached $5.967 per gallon on September 7, topping the previous weekly record of $5.810 set in June 2022.

  • Diesel needs to average only about $5.20 for the remaining 16 weekly observations to exceed its 2022 annual record of $4.989.

  • Gasoline faces a much steeper climb, needing to average roughly $4.35 through year-end while entering a season when prices typically weaken.


Diesel prices in the U.S. just climbed above the previous weekly record set in 2022, and the 2026 annual-average record is now within striking distance. Gasoline prices, while still elevated, are unlikely at this point to set a new annual record.

The latest EIA data sharpen that divergence. For September 7, on-highway diesel jumped 36.8 cents to $5.967 per gallon nationally, surpassing the previous nominal weekly high of $5.810 set in June 2022. Regular gasoline rose 8.6 cents to $4.157, still well below its $5.006 weekly peak in June 2022. That could leave 2026 with a new record annual average for diesel, while gasoline remains below the record it set in 2022.

Gasoline usually dominates the public discussion because it is the price most drivers see every week. Diesel is less visible to consumers, but it is embedded throughout the economy in trucking, agriculture, construction, rail, and other commercial activity. When diesel prices remain unusually high, the effects can extend well beyond the filling station.

The Math Behind The Record

According to the U.S. Energy Information Administration, on-highway diesel set its nominal annual-average record in 2022 at $4.989 per gallon. Regular gasoline also set its record that year, averaging $3.951 per gallon.

Using EIA’s 36 weekly price observations through September 7, I calculate a 2026 year-to-date average of about $4.895 per gallon for diesel and $3.772 for regular gasoline. That leaves 16 weekly observations for the rest of the year. To exceed the 2022 record, diesel would need to average about $5.20 per gallon over those remaining weeks. Gasoline would need to average about $4.35.

Fuel

2022 annual record

2026 avg. through Sept. 7

Needed final 16 weeks

Sept. 7 price

Diesel

$4.989

$4.895

$5.20

$5.967

Regular gasoline

$3.951

$3.772

$4.35

$4.157

Source: EIA; author calculations using weekly national retail prices through Sept. 7, 2026.

The latest EIA reading makes the annual-record math more favorable for diesel. If the September 7 prices simply remained unchanged through year-end, diesel would finish 2026 at roughly $5.22 per gallon, comfortably above the 2022 record. Gasoline would finish around $3.89, still below its record.

That means diesel could fall by roughly 77 cents from the September 7 reading and still average enough over the remaining weeks to set a record. Gasoline would need to rise by about 20 cents from its latest reading and then maintain that higher level through a part of the year when prices normally face downward seasonal pressure.

Why 2022 Was So Expensive

The 2022 records were not caused by a single event. The petroleum market was already tight before Russia’s full-scale invasion of Ukraine. The pandemic had disrupted oil production and refining around the world, some capacity permanently closed, inventories were low, and demand was recovering as economies reopened. EIA documented the tightening diesel market before the invasion.

Russia’s invasion then hit a market with very little spare room. Crude oil prices surged amid uncertainty over Russian supply, sanctions, and private-sector decisions to reduce purchases of Russian energy. Gasoline demand strengthened into the spring and summer, while refinery output and inventories struggled to keep pace. Regular gasoline ultimately moved above $5 per gallon nationally for a time in June, as EIA later documented.

Diesel faced an even tighter situation. Russia was a major supplier of diesel and other distillates to the global market, particularly Europe. The loss and redirection of those barrels tightened an already constrained market, while U.S. distillate inventories remained below normal. By October 2022, EIA reported only about 25 days of distillate supply in U.S. inventories, compared with a 2017-2021 average of 34 days. High crude prices were only part of the diesel story. The world was also short of refining capacity and distillate inventories.

Why Diesel Is So Expensive In 2026

There are similarities between 2022 and 2026. Once again, a geopolitical shock has pushed crude oil and refined-product prices higher. This time, the pressure has centered on the conflict involving Iran and constraints on energy flows through the Strait of Hormuz, one of the world’s most important oil transit points. EIA has cited reduced shipments through the strait as a major source of pressure on global oil inventories and prices.

But diesel has also been hit by product-specific problems. Ukrainian attacks have damaged Russian refineries and constrained Russian fuel exports, while Middle Eastern refinery and product flows have also been disrupted. In August, Reuters reported that the U.S. diesel crack spread, the difference between diesel futures and crude oil futures, exceeded $100 per barrel for the first time. That is an extraordinary signal of how tight the refined-product market had become.

This is not primarily a story of U.S. refiners failing to run. Reuters reported refinery utilization at 98% in the week ending August 28, the highest level since 2018. Yet EIA showed total U.S. distillate inventories at only about 104.2 million barrels, while East Coast stocks fell to 19.3 million barrels. Refiners are running hard, but the global market is still pulling strongly on available U.S. distillate supplies.

Gasoline Is Entering Its Slow Season

Gasoline has also been expensive in 2026, but it now faces a seasonal pattern that makes a new annual record less likely. Prices typically rise during the spring and summer as driving increases and refiners switch to more expensive summer-grade fuel. After the summer driving season, demand generally declines and refiners can return to less expensive winter-grade gasoline. EIA notes that gasoline refining margins normally ease in the fall.

Diesel tends to receive more seasonal support in the fall. Diesel powers much of the equipment used for the agricultural harvest and the trucks that move those crops. EIA has found that U.S. distillate consumption increased by an average of about 4% from September to October over the five years from 2019 through 2023. Winter then adds heating-oil demand, particularly in the Northeast.

That seasonal divergence is important to the record calculation. Gasoline needs to average roughly $4.35 per gallon for the rest of the year, above the September 7 price of $4.157, during a period when prices normally ease. Diesel needs about $5.20, nearly 77 cents below the latest EIA price of $5.967, while entering a season that typically provides additional demand support.

The Record Is Not Guaranteed

None of this makes a diesel record inevitable. A ceasefire or meaningful restoration of energy flows through the Strait of Hormuz could bring crude and refined-product prices down quickly. Restored refinery operations in Russia or the Middle East could ease the distillate squeeze, and a sharp economic slowdown could weaken freight and industrial diesel demand.

August STEO projected a 2026 annual average retail diesel price of $4.85 per gallon and regular gasoline at $3.78, leaving both below their 2022 records. But that forecast was completed on August 6, before the late-August surge in diesel prices and before the September 7 reading set a new nominal weekly high at $5.967. I would not call a diesel annual-average record a certainty, but the current arithmetic puts it clearly within reach.

The Big Picture

The comparison between 2022 and 2026 is a useful reminder that there is no single “fuel price.” Crude oil is the largest common input, so a geopolitical shock can push gasoline and diesel higher at the same time. But refinery capacity, inventories, trade flows, product demand, and seasonality can cause the two fuels to behave very differently after that initial shock.

In 2022, rebounding demand, constrained refining capacity, low inventories, and Russia’s invasion of Ukraine drove both gasoline and diesel to record annual averages. In 2026, another geopolitical disruption has again pushed crude prices higher, but the more acute shortage is in distillates. Based on the September 7 reading and the seasonal path ahead, diesel has already set a weekly record and now has a credible path to a record annual average as well.

By Robert Rapier


Canada courts C$1 trillion with mining at centre of pitch


PM Mark Carney emphasizes mining in Canada’s C$1 trillion global investment bid. (Photo by Lars Hagberg | PM Office.)

Prime Minister Mark Carney is putting mining at the centre of Canada’s bid for C$1 trillion ($721 billion) in global investment as Ottawa seeks capital to build mines, processing plants and the infrastructure needed to get more of the country’s resources to market.

More than a third of the 167 projects being pitched at the first Canada Investment Summit in Toronto this week involve minerals and mining. The broader portfolio spans energy, infrastructure, manufacturing and technology as the government brings Canadian businesses face-to-face with some of the world’s largest investors.

The mining-heavy pitch comes as escalating trade tensions with the US increase pressure on Canada to diversify its economic relationships and find new markets for its resources. But attracting investors is only part of the challenge: Canada must also show it can permit, finance and build major projects quickly enough to compete for global capital.

Mining capital

Carney invited 100 of the world’s biggest investors, collectively overseeing more than $70 trillion in assets, to the summit.

Expected attendees include BlackRock chairman Larry Fink and Temasek CEO Dilhan Pillay, along with managers of Norway’s government pension fund and representatives of state-owned companies such as Abu Dhabi National Oil Co.

Among the mining companies seeking capital is Troilus Mining (TSX: TLG), which needs $1.43 billion to develop its gold-copper project in Quebec. The prospectus also includes a nuclear-fuel services project described as Canada’s first uranium refining and conversion facility in more than 40 years.

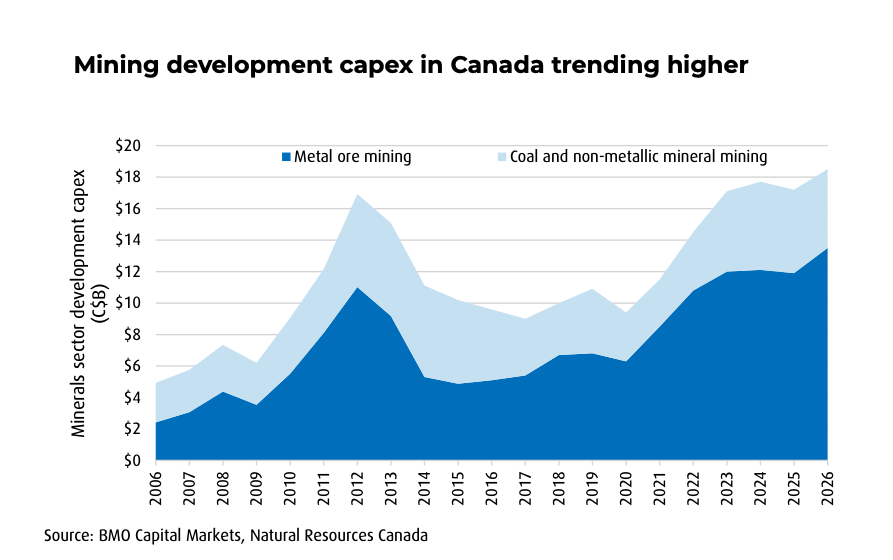
The investment gap leaves substantial room for growth. BMO Equity Research forecasts annual Canadian development capital expenditures will increase more than 11% over the next two years. 

Mining companies covered by BMO are expected to spend about C$350 billion on operating costs, sustaining capital and growth projects to produce Canadian metals and minerals over the next five years.

Beyond commodities

Canada’s opportunity extends beyond extracting commodities, BMO Global Metals & Mining analyst Matthew Murphy said in an investment report. Additional capital is needed for copper smelting and refining, by-product recovery, battery precursor materials, rare earth separation, magnets, graphite processing and recycling.

Building those capabilities could allow Canada to capture more value from its mineral wealth instead of relying primarily on upstream production.

The country has already produced major mining companies and attracted some of the world’s largest operators, giving investors exposure across commodities and market capitalizations. They range from Canada’s Agnico Eagle Mines (TSX: AEM; NYSE: AEM) to global miners Glencore (LSE: GLEN) and BHP (NYSE: BHP; LSE: BHP).

For investors gathering in Toronto, BMO’s analysis suggests the opportunity is therefore broader than financing individual mines. Reaching Canada’s investment ambitions will require capital for infrastructure, mineral production, processing and downstream industries that can turn its resource base into more complete domestic supply chains.

Carney’s push for investment also extends beyond Canada’s borders. After the summit, he is scheduled to travel to Saint-Pierre-et-Miquelon, France, on Sept. 20 to meet French President Emmanuel Macron.

The two leaders are expected to discuss deeper cooperation in strategic sectors including energy and critical minerals, along with aerospace and advanced technologies such as quantum computing, satellites and supercomputing. The talks come as Canada pursues closer economic and security relationships with France and the European Union.

Carney has also put figures with deep business and investment experience in key government positions. He appointed Dominic Barton, chair of Rio Tinto (ASX, LON: RIO) and a former Canadian ambassador to China, as chair of Invest in Canada, the federal agency responsible for attracting foreign direct investment.

Building challenge

For miners, access to capital solves only one part of the development equation.

Carney has moved to streamline project approvals and accelerate major developments, but Canada’s lengthy permitting processes and history of delays remain potential obstacles to converting investment commitments into producing mines and processing facilities.

The issue is particularly acute in mining because deposits cannot be moved to jurisdictions offering faster approvals. Developing a mine can require billions of dollars in upfront investment alongside roads, power, processing plants and transportation infrastructure before its commodities reach customers.

Energy investors have faced similar problems. Carney has reversed some climate policies introduced under former prime minister Justin Trudeau and supported the prospect of another oil pipeline, yet some executives remain wary after previous projects failed to advance.

Enbridge Inc.’s (TSX: ENB) proposed Northern Gateway pipeline had its federal approval overturned by a court, while TC Energy (TSX: TRP) abandoned its C$15.7-billion Energy East project to carry crude to Eastern Canada.

Canada could encourage reluctant investors to move off the sidelines by putting government capital behind projects, according to TD deputy chief economist Derek Burleton.

The summit’s success could ultimately hinge on whether Canada can move beyond supplying raw materials and attract the investment needed to build domestic refining, processing and manufacturing capacity that captures more of their value.

(With files from Bloomberg)


Investment in Canada’s mining sector to grow with global demand: BMO


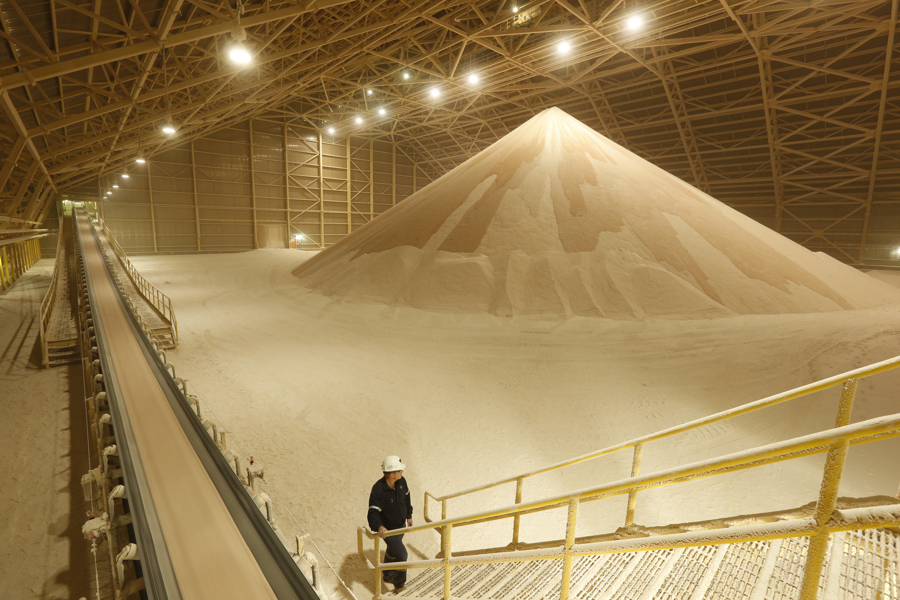
Saskatchewan, the heart of Canada’s potash industry, is a top destination for mining investments. (Image courtesy of Potash Corp.)

Canada’s mining sector could capture a larger share of global capital as rising critical-mineral demand, expanding development spending and government support create opportunities from mines to processing, according to BMO Global Metals & Mining. 

The outlook comes ahead of the Canada Investment Summit on Sept. 14-15, which aims to bring together major global investors and business leaders to help catalyze C$1 trillion ($721 billion) in total investment in Canada over the next five years, according to Matthew Murphy, BMO’s managing director, Equity Research. The federal government has identified critical minerals as one of the key areas for attracting that capital. 

Canada already ranks as the world’s largest potash producer, second-largest uranium producer, and fourth-largest gold producer and aluminum refiner. Global mining expertise and leadership as well as government regulators that aim to develop the industry domestically, give the country an established base from which to expand. 

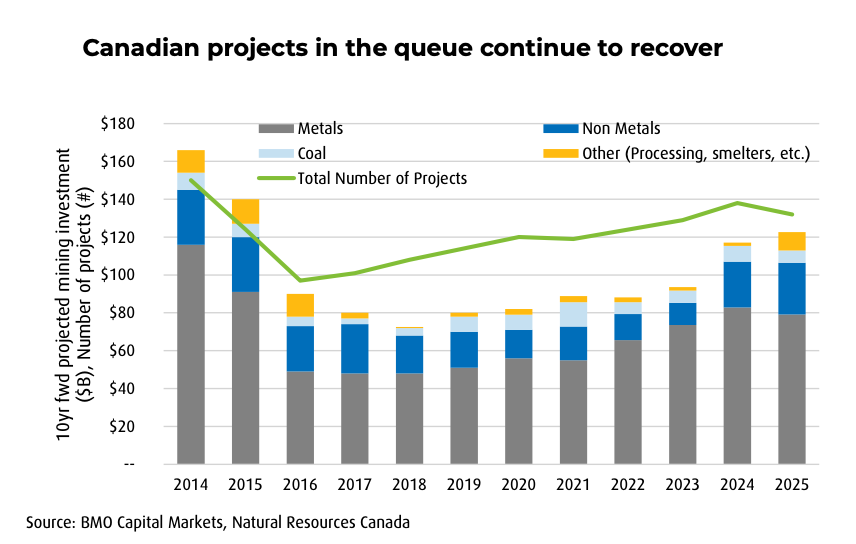
Development spending is also returning to corporate capital allocation plans. As of 2025, companies planned about C$120 billion of spending on projects included in Natural Resources Canada’s 10-year Major Projects Inventory outlook, Murphy said. That is C$50 billion more than in the 2018 outlook, though still well below the previous cycle’s peak of about C$220 billion in real 2026 dollars. 

The investment gap leaves substantial room for growth. BMO Equity Research forecasts annual Canadian development capital expenditures will rise more than 11% over the next two years. Mining companies covered by BMO are expected to spend C$350B on operating costs, sustaining capital, and growth projects to produce metals and minerals in Canada over the next five years.  

Investment in key areas 

BMO’s study asks investors to shift from upstream towards downstream investment to make end-to-end production in Canada a reality. That spending could reinforce Canada’s position as governments seek more secure supplies of commodities essential to energy, defence and advanced manufacturing, while miners increasingly consider the country for new development capital, the bank says. 

For that shift to happen, the next mining investments need to focus on domestic copper smelting and refining, by-product capture, battery precursor materials, rare earth separation and other specific materials smelting and production, BMO recommends. 

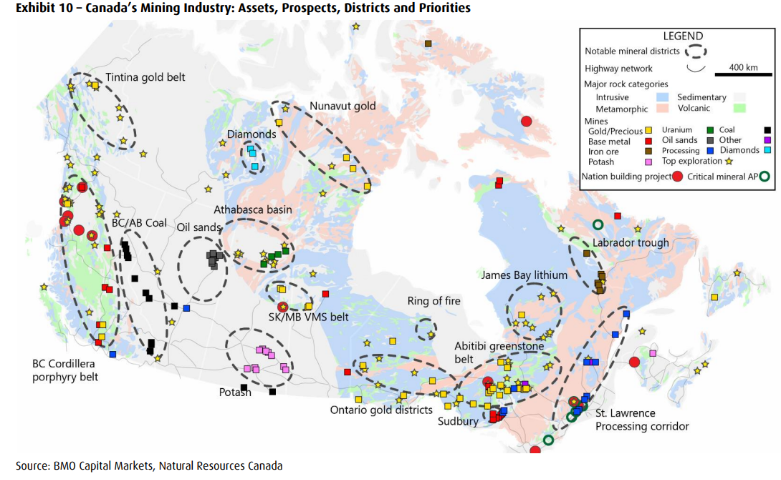
Infrastructure has always been a key area for investing in mining, but it now can unlock new mining districts and generate new opportunities across the country, from British Columbia to Ontario’s Ring of Fire to Nunavut in projects ranging from gold, nickel and lithium.  

Considering the importance of critical minerals in the global market, BMO recommends developing niche critical-mineral supply chains, which may require government intervention where market economics alone are insufficient. 

Targeted price supports could be needed for some commodities, while capital and regulatory backing for vertical integration could help companies develop more profitable downstream portions of the critical-mineral supply chain, Murphy said. 

Those measures could address some of the challenges facing critical-mineral projects, including volatile prices, limited domestic processing capacity and competition for investment capital.  

Infrastructure financing may provide another route to expanding the industry. Separating infrastructure investment from mine development could attract specialized infrastructure funds, reduce the cost of capital and free miners to direct more money toward production capacity and downstream facilities, according to Murphy. 

Funding gap 

Improving mining profitability and advancing new projects will require not only greater investment in the sector, but also careful decisions about where that capital is allocated.  

Separating infrastructure and mine operations investments could attract more infrastructure funds, lower the cost of capital and bring more capital for mining capacity and downstream industry.  

While Canadians are investing in mining, BMO finds it could be invested more domestically. It suggests that there’s an opportunity for mining infrastructure investment, especially through the Canadian pension fund that manages C$4.5 trillion ($3.2 trillion) in assets that are under-allocated domestically.  

Murphy said that alignment could allow Canadian pension funds to generate more competitive risk-adjusted returns domestically, while helping finance infrastructure and mining capacity needed to unlock new districts. 

For investors gathering at the Canada Investment Summit, BMO’s analysis suggests the opportunity is therefore broader than financing individual mines. Reaching Canada’s investment ambitions will require capital across infrastructure, mineral production, processing and other downstream industries that can turn the country’s resource base into more complete domestic supply chains. 

With the increasing alignment of government, regulators, and citizens, the Canadian mining sector can offer highly competitive risk-adjusted returns and enable funds to invest in the country, BMO concluded.