It’s possible that I shall make an ass of myself. But in that case one can always get out of it with a little dialectic. I have, of course, so worded my proposition as to be right either way (K.Marx, Letter to F.Engels on the Indian Mutiny)
About 300 Chinese nationals working in the Democratic Republic of Congo’s copper belt were detained earlier this week as part of a crackdown on illegal mining, according to people familiar with the matter.
The arrests took place mostly in the mining hub of Kolwezi, the people said, asking not to be named describing a sensitive issue. Chinese companies dominate copper output in Congo, and workers were arrested for their alleged involvement in illicit mining on concessions belonging to other firms, according to some of the people.
The officials carrying out the arrests included agents from Congo’s National Security Council and immigration authority, some of the people said. The Chinese embassy in Kinshasa intervened and some of the workers have since been released, they said.
The Chinese embassy, and Congo’s mining ministry, immigration authority and presidency didn’t respond to requests for comment.
A wave of mainly Chinese investment has fueled Congo’s copper expansion in recent years, helping the nation triple output since 2015 and surpass Peru as the world’s second-largest producer. But the mining boom has also brought disorder.
Artisanal miners, sometimes supported by soldiers, have repeatedly operated without authorization on permits held by international investors.
(By William Clowes and Julian Luk)
Saturday, October 17, 2026
New genetic study reveals surprising origin of Native Hawaiians
Europe was deep in the Middle Ages when halfway around the world, on the remote, windswept shores of tiny Easter Island, a group of skilled seafarers prepared for a long voyage. They stocked their double-hulled catamarans with taro, sweet potato and bananas — food for many weeks at sea, but also, they hoped, to plant on a distant land they would make their new home.
There is no written record of their journey, but Stanford Medicine researchers and collaborators analyzing the genomes of modern-day Polynesians have discovered indelible genetic evidence that ancient sailors from this region did settle a faraway land. To the researcher’s surprise, their new home was Hawaii, some 7,000 kilometers away, among the most distant Polynesian islands from Easter Island.
The findings are reported in a study published Oct. 8 in Science.
“What we uncover in this paper is where the native people of Hawaii had come from,” said Alexander Ioannidis, PhD, assistant professor of genetics and of biomedical data science, and co-senior author of the study. “Hawaii is the only Polynesian island in the Northern Hemisphere, so it’s a long way from everything.”
The other co-senior author is Keolu Fox, PhD, an associate professor of anthropology at the University of California, San Diego, and a Native Hawaiian.
Polynesia consists of more than 1,000 islands spread over an area of the Pacific Ocean roughly equivalent to the areas of North and South America combined. Tropical, lush Hawaii is about as far away from temperate Easter Island in the far south Pacific as San Francisco is from Lima, Peru.
But the new findings do more than help reconstruct the settlement of Polynesia and add to evidence of an ancient ultravoyaging culture — they also identify genetic bottlenecks that have profound implications for precision medicine and disease risks among modern Polynesians.
Founder effects
These genetic bottlenecks are known as founder effects when they result from a small portion of a population separating and founding a new population. This narrowing of the gene pool can amplify the frequency of otherwise rare genetic variants, sometimes linked to disease. Founder effects have been well studied in groups of European descent like the Amish, the Ashkenazi Jews and the Finns, resulting in standard screenings for certain genetic conditions in these groups.
The new study reveals that an even stronger founder effect has been overlooked among Native Hawaiians.
“What we discovered is in the Eastern Polynesians, such as Native Hawaiians, the founder effects are more than an order of magnitude, so more than 10 times, larger than what we have in the populations of European descent we’ve studied so well,” Ioannidis said.
That’s because Native Hawaiians sit at the end of a long sequence of genetic bottlenecks as their ancestors sent off small groups, perhaps only a few hundred individuals at a time, to settle new islands over the course of a few centuries.
An earlier genetic study by the researchers had traced the settlement of Polynesia from Samoa to Fiji and Tonga, then gradually eastward to the Cook Islands, the Society Islands (including Tahiti), Mangareva and ultimately Easter Island around the year 1210. But the longest journey was still to come.
“We thought Easter Island was the end when we were first doing that study, but now it looks like it was part of this path to Hawaii, which is really incredible,” Ioannidis said. “By the time you’ve gotten all the way to Hawaii, you’re at the end of a series of founder effects, so it’s really intense.”
Encoded genealogy
The researchers made their latest discovery by analyzing the genomes of over 1,000 individuals throughout Polynesia.
“People on the islands today have encoded in their genomes essentially the genealogy of all of their ancestors,” Ioannidis said.
They focused on genome segments of Polynesian ancestry, removing more recent additions of European and Asian ancestry, for example. They compared the length of chromosomal segments, known as identity-by-descent segments, shared among people from different islands. The longer the shared segments between two people, the more recently they shared a common ancestor.
They found that Hawaiians share the most Polynesian ancestry with people on Easter Island, followed by people on Mangareva, an island nearly 3,000 kilometers east of Easter Island. Though no one had connected these distant dots previously, it makes sense that an ultravoyaging culture capable of reaching Easter Island from Mangareva would be the one to then settle Hawaii, Ioannidis said. (An earlier study by the researchers found that members of the same ultravoyaging population also reached South America and came in contact with Native Americans.)
The team also conducted a more detailed genomic analysis of people from Tahiti, the island for which they had the most genomes. By comparing identity-by-descent segments within the population, they could estimate the size and date of the founding generation — a group of approximately 800 people who arrived on the island about 34 generations ago, around the year 1070. (The population estimate is of a single generation of reproductive age and doesn’t include children and elders they may have brought along.)
“Archaeologists and others have long wondered how many people founded these islands. That’s not something that you can determine definitively from archaeology, but we can determine it from genetics,” Ioannidis said.
The genomic analysis also reconstructed the rapid population growth on Tahiti after the initial settlement and a significant population crash in the 1700s following European colonial contact.
The researchers are working on similar reconstructions for Easter Island and Hawaii, which will require more genomes.
Clinical urgency
But more pressing is the need for large-scale genomic studies to identify clinically relevant variants that may be unusually prevalent among Polynesians.
The researchers analyzed three variants that recently have been linked to autosomal recessive conditions (requiring two copies of the gene) among Eastern Polynesians: ADAMTSL4, which can cause dislocated lens in the eyes; PDE6B, which can cause progressive vision loss; and FAN1, which can lead to kidney failure.
These variants are exceedingly rare among the global population and hardly present in international genome databases, but they are carried by 2% to 3% of the Eastern Polynesians studied. That level meets standard thresholds for genetic screening recommendations.
“We should be doing more sequencing and trying to characterize more of these conditions among Native Hawaiians,” said Ioannidis, noting that the Native Hawaiian population is nearly twice the size of the Amish population, yet still lacks genetic testing guidelines. “We don’t have recommendations for genetic testing, and there’s no reimbursement from insurance because these are conditions we don’t even know about.”
“This is a population that should be getting research resources and attention from geneticists even more urgently.”
Researchers from the University of California, Santa Cruz; Variant Bio; Direction de la Santé de Polynésie Française in Tahiti; Hôpital Saint-Philibert in France; the University of Chile; the National Polytechnic Institute in Mexico; and the University of Alabama at Birmingham contributed to the study.
The study received funding from the National Institutes of Health (grants T32HG012344, U01HG007417 and U01HG007419).
# # #
About Stanford Medicine
Stanford Medicine is an integrated academic health system comprising the Stanford School of Medicine and adult and pediatric health care delivery systems. Together, they harness the full potential of biomedicine through collaborative research, education and clinical care for patients. For more information, please visit med.stanford.edu.
Copper pulled back from a three-week high on Wednesday after US inflation data put a Federal Reserve rate hike this month back on the table, and word of a preliminary deal to avert a strike at BHP’s Escondida, the world’s largest copper mine, took some of the supply premium out of the price.
Comex copper for December delivery traded at $6.6695 a pound (about $14,704 a tonne) late morning in New York, down 0.8%, after touching $6.7890 earlier in the session. The most-active contract’s record settlement of $6.89 was set on September 9, the day before a report that the White House tariff plan had stalled knocked more than 5% off the price.
In London, three-month copper climbed as far as $14,700 a tonne, its highest since September 23, before easing to $14,532 by early afternoon. Cash copper settled at a record $14,822 on Monday and $14,741 on Tuesday, and LME inventories have fallen for seven straight sessions to 229,650 tonnes.
US consumer prices accelerated in September on a surge in gasoline costs, and the CME’s FedWatch tool put the odds of a quarter-point hike at the Fed’s late-October meeting at about 44%, double the day before, Reuters reported. New York Fed President John Williams said he still sees one more hike this year.
Two sources told Reuters that Escondida’s supervisors’ union and the company had reached a preliminary agreement, which members were voting on Wednesday morning, and a union leader told Bloomberg a deal was “virtually done”. Unions at Antofagasta’s Centinela returned to talks on Tuesday after a week-long stoppage, while the open pit at Codelco’s El Teniente remains shut after a deadly landslide.
Click on chart for live prices.
Copper’s 2026 advance has forecasters raising their numbers for the second time in three months, and with the metal averaging $13,471 a tonne for the year to date, the 2026 revisions mostly bring the sheet into line with the tape.
Macquarie now has copper averaging $13,573 this year, BMO Capital Markets $13,619 and BMI, a unit of Fitch Solutions, $13,500, up from the $12,700 it moved to in July. The differences open up from next year, and they come down to how much of the 1.5 to 2 million tonnes of copper now sitting in the United States is counted as surplus.
“The great copper gamble”
Macquarie, which in July called the rally “running ahead of reality”, has lifted its 2027 average by 14% to $12,750 and pushed the cycle low to $12,000 in the fourth quarter of next year from $11,000 a quarter earlier, while its long-term price rises to $10,500 a tonne in 2025 dollars.
Prices “have disconnected from the fundamentals and could arguably move higher or lower depending on the outcome of the Section 232,” the bank’s strategists write in a quarterly compendium whose copper chapter is headed “The great copper gamble”, listing the metal among its preferred commodities for the next six to nine months “but very binary”.
The fundamentals as Macquarie counts them are a 223,000-tonne surplus this year after a 531,000-tonne disruption allowance, and surpluses averaging more than 700,000 tonnes a year from 2027 as mine supply grows 4.9% next year and 4.3% in 2028, with Collahuasi, Grasberg, Kamoa-Kakula and Centinela ramping up, Tia Maria starting and Cobre Panama back in full from mid-2027.
Global demand growth slows to 1.5% in 2027 on its numbers, with none at all in China, where construction-related copper use is shrinking 9% a year and air conditioner makers are “again looking at aluminium substitution.”
Visible stocks worldwide are up 300,000 tonnes this year, but that is the US build; everywhere else they are down 168,000 tonnes, and Macquarie says sentiment will not turn until LME and Shanghai inventories start rising again, either quickly on a tariff decision or gradually as its forecast surpluses feed through.
Macquarie’s four tariff scenarios run from a January 1 that passes with no announcement at all, which it rates most likely, to a definitive decision against a duty, which it rates least likely: “the CME price will most likely collapse, taking the LME price with it, and the arb will invert,” with surplus US stocks reappearing in LME warehouses in the US and Asia.
A tariff announced six to eight weeks ahead of implementation would pull a last wave of metal into the US and leave the rest of the world “very tight”, while a formal six-month delay would see the spread fade as it did for platinum and palladium after the critical minerals decision.
Expectations are also growing that a scrap export ban will be folded into any decision; an immediate ban would take about 600,000 tonnes a year of contained copper off the world market.
“Has the market misread US inventory?”
BMO Capital Markets arrives at a very different place from a similar starting point. Its quarterly price deck, published two days before Macquarie’s, raises its long-term copper price by 47% to $16,000 a tonne in real terms, or $18,000 nominal by 2030, with $14,675 for 2027 and $16,000 for 2028, and the bank puts itself 46% above consensus on the long-term number. Its market balance is close to balanced throughout: an 83,000-tonne surplus this year, then small deficits from 2027.
The argument turns on what the US hoard, now close to 2 million tonnes on BMO’s estimate, or about a year of American consumption, actually represents. China’s refined copper imports have run below trend and its exports above trend since the tariff trade began, a cumulative swing of about 1.6 million tonnes on a net basis, which BMO reads as Beijing allowing its strategic reserve to run down while Washington built one.
“Instead of there being a build in above ground inventory over the last 2 years, there has been a geographical redistribution from ‘not visible’ to ‘visible’, meaning today’s price of ~$14,500-15,000/t is fundamentally supported,” the bank writes. Had China bid for metal alongside the US, “copper prices today would in fact be much, much higher,” and at some point China will want to restock.
BMO expects no tariff decision before the US midterms in November, which may see copper “pause for breath” and keep the Comex-LME spread narrow, but says investors it talks to are coming around to the view that the US stockpile “could simply stay in situ for many more years.”
Rising dependence on scrap, with China’s secondary refined output heading for 3.3 million tonnes this year from 2.8 million, is the other leg of its case: scrap is the marginal unit, and it only comes out at higher prices.
BMI sits between the two. It still views the rally “as having extended beyond what fundamentals alone would suggest” and has the market in a 43,000-tonne surplus this year, but has cut its 2026 mine supply growth forecast to 1.1% from 2.4% with Chilean output down 4%, and expects a deficit from 2027 that widens to 1.7 million tonnes by 2035 as demand grows 3% to 4% a year on grids, EVs and data centres.
Its 2027 forecast is $12,900, rising to $15,000 in 2029 and an unchanged $17,000 in 2035. The International Copper Study Group, meeting this week, lifted its 2026 surplus to 104,000 tonnes and kept 2027 at 368,000 tonnes.
The arb has gone, the metal has not
The spread that built the US stockpile has all but disappeared on a spot basis. Comex October copper at $6.62 a pound trades below LME cash, which at Tuesday’s $14,741 works out to $6.69, and John Gross of The Copper Journal calculates the month-to-date average has flipped to an 85-point LME premium from a 17-cent Comex premium in June.
Most of that is London’s doing: the backwardation that put cash $164.50 over three months at Monday’s settlement, since narrowed to $115.50, reflects how little spot metal is left outside the US.
Aurubis, Europe’s largest copper producer, has offered customers a record premium of $347 a tonne for 2027 supply, 10% above this year’s level, Benchmark Minerals reported, and a company spokesperson told Bloomberg that “a lot of material has relocated to the US, leaving warehouses quite empty.”
Further down the curve the premium survives. December Comex at $14,704 a tonne sits about $170 over LME three-month, which Macquarie read at the end of September as the market pricing a 10% chance of a 15% duty (on Wednesday’s prices the same arithmetic gives about 8%).
That is too little to pull fresh shipments across the Atlantic, but enough to keep what is already there in place as long as the Comex curve pays traders to hold it. The tonnes still arriving are cargo booked months ago: Comex stocks rose another 6,500 tonnes last week to 713,000 tonnes, with 100,000 tonnes of African and South American copper due through October.
Deutsche Bank takes the stockpiling argument furthest. Daniel Ghali, the bank’s new head of metals research, told the Wall Street Journal that with China adding to its strategic reserve for decades and the tariff threat pulling metal into American sheds, the two countries could be sitting on 71% of the world’s supply by the end of the year. On that trajectory copper “simply won’t be available” to users elsewhere by the end of 2028, an outcome averted only by prices high enough to force substitution into aluminium.
He sees $10 a pound, or $22,050 a tonne, in the second quarter of 2027, almost 50% above current levels. Even a decision against tariffs may not free the metal, he told the paper, since the LME has warehouses in the US and copper may simply be shuffled between American sites rather than leave the country.
Gross points to copper’s premium over aluminium, which hit a record $5.08 a pound in September, more than double its July 2022 low. “Clearly, this rising premium cannot continue indefinitely, but who among us will step forward to say it’s at the top?” he writes. His September monthly report makes the longer point: China consumed 58.9% of the world’s refined copper last year, up from 12.4% in 2000. “There are too many copper eggs in China’s basket.”
Miners still pricing $5 copper
Copper producers fell with the metal on Wednesday, Lundin Mining down 3.9%, Freeport-McMoRan 3.7%, Southern Copper 3.3% and Teck Resources 2.9%, but the year has been kind. Southern Copper is up 44.1% in 2026, taking its market value to $169 billion, with Glencore ahead 38.6%, BHP 38.0% and Freeport 37.4% at a $100 billion valuation. Teck has gained 36.1% and Anglo American 29.2%. Lundin has managed 13.0%, Antofagasta 7.5% with Centinela on strike, and First Quantum 3.0%.
RBC Capital Markets calculates that North American copper producers at 1.0 times net asset value imply a copper price of $5.03 a pound, from $5.98 for Freeport down to $3.96 for Ivanhoe Mines, against a futures price near $6.70. The group trades at 0.9 times net asset value, in line with its 10-year average.
Escondida supervisors, about 1,020 workers at the world’s largest copper mine, said they would strike at 8 a.m. local time Wednesday, a week after workers walked out at Centinela.
Chile’s August copper output fell 12.8% to 369,500 tons, the lowest monthly total since February 2011, and a fatal landslide hit Codelco’s El Teniente on Sunday.
The IEA still sees primary copper supply about 25% short of requirements by 2035, while Peru targets $33 billion in mining investment and Argentina’s Vicuña aims for a final investment decision by year-end.
Supervisors at BHP’s Escondida, the world’s largest copper mine, said they would strike at 8 a.m. local time Wednesday after government-led mediation failed to produce a contract. The union represents about 1,020 workers at a mine that supplies roughly a quarter of Chile’s copper, and the stoppage follows a walkout at Antofagasta’s Centinela that began Oct. 7. Both land as governments across the Andes ask miners for far more copper, not less.
Demand will not wait
S&P Global projects that copper demand will climb from 28 million metric tons in 2025 to 42 million tons by 2040, with AI data centers and defense each roughly tripling their consumption, and it warns that supply could fall 10 million tons short. The IEA still sees primary supply about 25% short of requirements in 2035, down from a 30% gap in last year’s edition.
Copper runs through grids, electric vehicles, wind and solar farms and the AI data center buildout, which S&P says could account for 14% of U.S. power demand by 2030, so a shortfall in the metal reaches well beyond mining. BloombergNEF has warned that a tight market could bring cost inflation or delays for electrification projects. Peru is targeting at least $33 billion in mining investment over five years, and Chile’s pipeline tops $100 billion over the decade.
Chile keeps losing output
Chile’s copper output fell 12.8% in August from a year earlier to 369,500 tons, the lowest monthly figure since February 2011, according to national statistics data reported by Bloomberg. On Sunday, heavy rain triggered a landslide at Codelco’s El Teniente mine that killed two contractors and led the company to partially suspend operations, and El Niño could bring more rain to Chile and Peru in the months ahead.
Cochilco expects national production to fall 2.6% this year to 5.27 million tons before recovering to 5.55 million in 2027. TD Securities analysts said strike votes, worker fatalities and operational disruptions have helped “maintain a supply-risk premium,” and copper has held close to its September record high.
China’s acid squeeze
Morgan Stanley estimated in April that 1.1 million tons of Chile’s annual leached copper output, more than half its refined production, could be exposed to a Chinese ban on sulphuric acid exports. Miners use the acid to leach metal from ore, and Chinese customs data showed shipments to Chile fell to zero in March, with Beijing reportedly planning a full halt from May.
Permits and protests
Permitting in Chile can take as long as 12 years in some cases, according to GlobalData, and President José Antonio Kast ordered ministers in March to clear 50 pending claims tied to about $16 billion in projects. In Peru, President Keiko Fujimori’s government wants to authorize 240 exploration and extraction projects this year, yet the Observatory of Mining Conflicts counts nearly 200 social conflicts nationwide, 64 of them tied to mining and other environmental disputes, and says most of the main mining regions voted against her.
Argentina starts from zero
Argentina has not produced copper since the Alumbrera mine closed in 2018, which makes Vicuña, the BHP and Lundin Mining venture, its biggest test. The project received the top tier of RIGI benefits this year, and its backers are targeting a final investment decision on a $7.1 billion first phase before year-end, with first copper planned for 2030.
In April, a judge in neighboring La Rioja ordered a 30-day suspension and blocked machinery from using an access road through the province, saying the province had been left out of the environmental assessment. A San Juan court allowed work to continue days later.
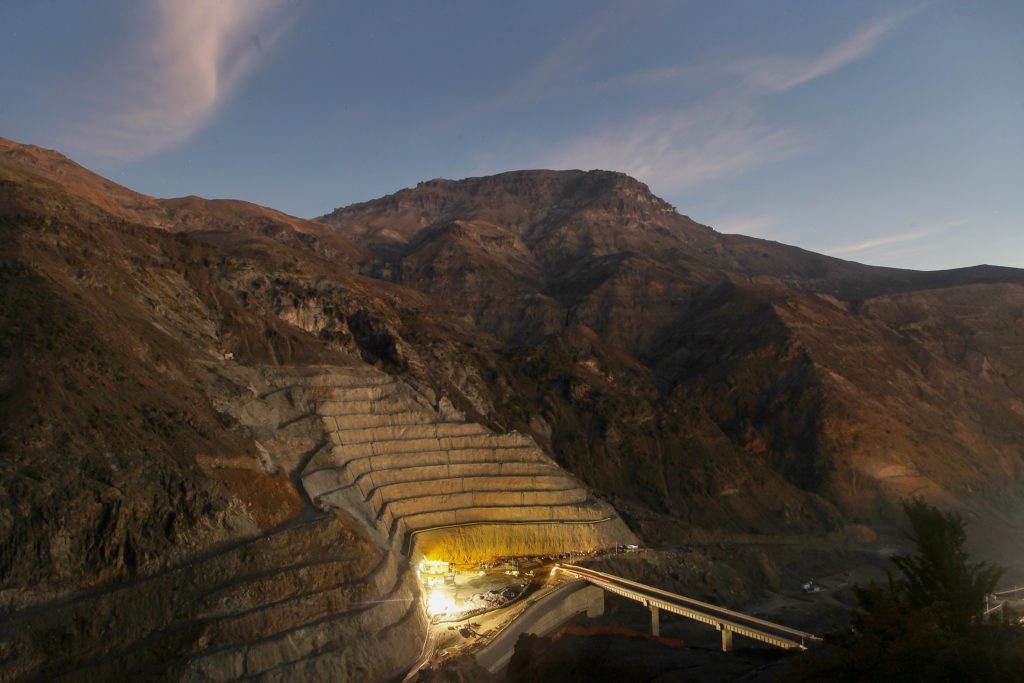
Two workers died after a snow avalanche struck Codelco’s giant El Teniente mine, as wild weather continues to batter Chile and compound setbacks for the biggest copper-producing country.
The two subcontractor employees, who had been carrying out inspections in the mine’s open-pit area, were found dead Sunday after initially being reported missing, the state-owned company said in a statement.
The open pit remained halted Monday, while other parts of El Teniente, including its sprawling underground operations and processing plants, were running normally, according to Amador Pantoja, head of a workers’ union at the mine. The open pit accounts for less than 10% of the mine’s total production.
The fatalities are the latest consequence of bouts of severe weather that have hit Chile in recent months, disrupting mines and infrastructure. Heavy rain and storms have contributed to a drop in copper output, while flooding and debris flows have also caused damage in the capital Santiago.
Open-pit operations at El Teniente had already been halted because of bad weather when the avalanche of snow, rock and mud struck. Investigative police and prosecutors were at the site carrying out inquiries into the circumstances surrounding the accident.
“The life and physical safety of our workers are non-negotiable values that must take precedence over any production target or operational continuity,” Economy and Mining Minister Daniel Mas said in a statement.
Weather-related disruptions are adding to operational setbacks, accidents and declining ore quality that have weighed on copper production in Chile. Labor tensions are also adding to supply risks, with workers on strike at Antofagasta Plc’s Centinela mine and a separate wage dispute at BHP Group’s Escondida.
The blows come as the copper market grapples with constrained mine supply, trade dislocations and growing demand. Copper surged to a record near $15,000 a metric ton last month, with some analysts forecasting further gains. Futures rose as much as 1% Monday.
El Teniente, Codelco’s largest operation, was the site of a rock burst in July 2025 that killed six workers and disrupted production. Earlier this month, a worker died at the Santiago-based miner’s Radomiro Tomic mine, just over a week after a separate fatal accident at Escondida.
The latest fatalities come as Codelco grapples with a prolonged slump in output that’s contributed to a broader decline in Chilean copper production. While the previous administration sought to restore production, the new leadership under Chairman Bernardo Fontaine is looking to consolidate output around current levels while prioritizing value over volume.
The recent disruptions also offer a glimpse of the risks facing South American copper mines in the months ahead as El Niño develops, potentially bringing heavier rainfall and flooding to key producing regions in Chile and Peru.
(By James Attwood)
Investigating the Hidden Costs of World’s Farmed Seafood
For nearly a decade, the Outlaw Ocean Project, the non-profit journalistic organization that I founded, has produced high-impact investigative stories about lawlessness at sea and the variety of threats posed to the people and biodiversity of a space that covers two thirds of our planet.
The oceans bear a heavy and largely invisible burden. The public usually takes it for granted, a forever self-replenishing resource that we use to fill our stomachs or line our wallets. Our journalism intends to stoke urgency and to help the public reimagine the oceans, less a grocery store than a library or a cathedral, a protected common.
Aquaculture was meant to ease pressure on the oceans. By raising fish, fewer would need to be taken from the wild—or so the logic went. In practice, the opposite has occurred. More than a fifth of all marine life removed from the oceans is used for feed, primarily for farmed fish. And demand for farm-raised fish is increasing. More than half of the seafood eaten globally comes from aquaculture, which is a $313-billion industry and the fastest-growing segment of global food production.
Over the past 5 years, an international team of journalists at The Outlaw Ocean Project examined the largely unaccounted-for toll of using food for feed. We focused on one of the world’s most important feed ingredients: fishmeal.
Consisting of two dozen stories and documentary films, the Food for Feed investigation offers a sobering picture of what fish-farming really entails, including forced labor, avoidable worker deaths, rampant stench, lost livelihoods, civil unrest, illegal fishing, food insecurity and species disappearance. Obscured behind aquaculture’s well-marketed reputation for sustainability and clever, eco-friendly adaptation, most of these ills have remained invisible to the consumers of farmed fish. Until now.
What We Did
The reporting began by identifying the locations of more than 1,400 fishmeal factories across 64 countries—facilities responsible for nearly the entire global supply of this lucrative, protein-rich, dark-yellow powder and its oil counterpart. We assessed more than 2,400 ships tied to fishmeal production, operating in the waters of at least 30 countries.
To do that, we assembled a global network of more than two dozen journalists operating in as many countries. The team included coders who scraped and structured data from government databases and researchers who monitored local reporting, court records, and social media for evidence of labor abuses, environmental violations, community complaints, and other issues linked to fishmeal production.
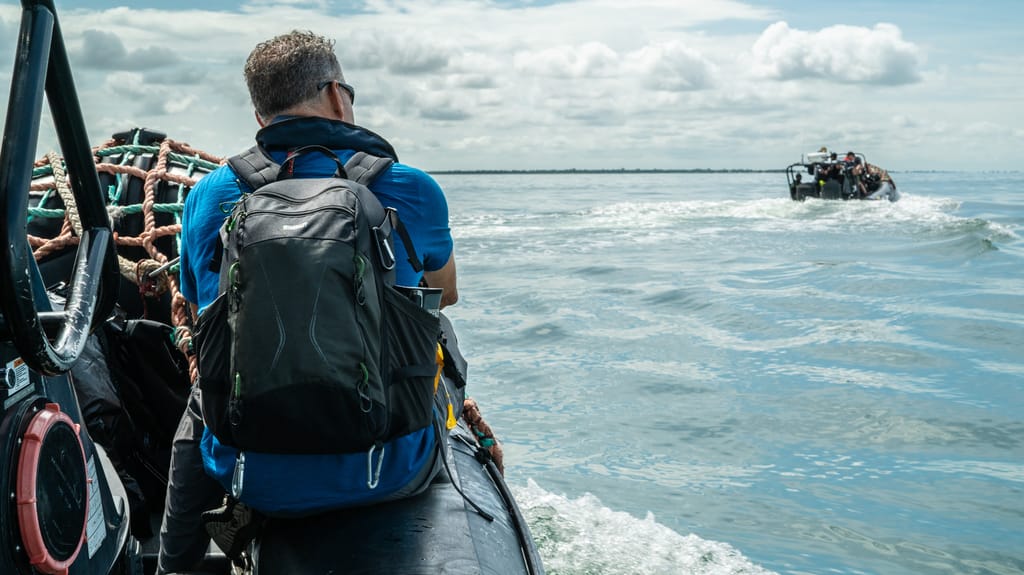
The reporting also involved intensive, on-the-ground work. Reporting teams took six voyages at sea, including the South China Sea, the Southern Ocean near Antarctica, and the North Atlantic Ocean. These expeditions involved boarding fishmeal vessels to review logbooks, inspect living conditions, interview workers, and document potentially illegal practices. On land, reporters visited fishmeal factories and aquaculture sites across Senegal, Thailand, Peru, Gambia, Vietnam, Indonesia, Cambodia, Greece, and India.
Along these supply chains, the investigation documented a wide range of impacts: The depletion of local fish stocks; food insecurity in communities where inexpensive, edible fish is diverted to animal feed; and exposure to hazardous chemicals among residents living near fishmeal plants and waste-dumping sites. The reporting also tracked worker deaths and injuries on fishmeal-associated vessels or in fishmeal plants. The industry impacted the climate by clearing forests of carbon-capturing mangroves and meadows of seagrass to make way for fish farms, and shipping feed to customers thousands of miles away.
To counter these hidden costs and hold the industry accountable, documenting the abuses was only the first step. It was equally important to make the evidence transparent, accessible, and usable by others. To that end, The Outlaw Ocean Project developed several additional tools designed to increase transparency around both our reporting and the fishmeal industry.
The Discussion page documents the correspondence between our journalists and more than 400 companies, government agencies, and certification bodies cited in the reporting. Several months before publication, we contacted each organization, presented them with the relevant findings and methodology, and invited them to respond to specific questions. We published these exchanges in full.
In the stories, we published footnotes that provided the sourcing behind every reported claim, including archived links to all cited documents, news articles, raw data, and web pages.
The methodology page provides a comprehensive public account of the entire investigation’s approach, including the documents, websites, code, and raw data utilized throughout the project. Additionally, case-by-case methodology is offered by way of superscript notes attached to key paragraphs or sections of the investigation.
Bait to Plate
Bait to Plate is an interactive tool that maps seafood supply chains and indicates the crimes and concerns hidden within them. Rather than telling one story or giving one explanation, this tool offers an infinite variety. Think of it as a smart fact-shuffler: it takes tens of thousands of reports from the Outlaw Ocean Project and elsewhere about ships, plants, and companies, then snaps them together like Legos to answer a user’s exact question.
To better navigate Bait to Plate, we created the B2P Bot, which allows users to ask any question they can imagine. The database holds thousands of entities and tens of thousands of connections. A journalist or other researcher who doesn’t know exactly what to look for can spend hours clicking through tables and filters. The B2P Bot allows real-world questions instead. The bot also sees the specific information on a user’s page and what entity they are viewing, and which visualization is open. As a result, a user can ask “What can you tell me about this company?”, and the bot understands the context of the question based on the page the user is on.
The bot has been leashed in ways we think are important. For example, it is limited to foregrounding existing reporting rather than writing its own prose or analysis. The content that it surfaces is always clearly cited to its source type so that a user can discern whether they find that source trustworthy.
What Comes Next
Bait to Plate will continue to grow. Daily, staff at the Outlaw Ocean Project culls hundreds of news articles, NGO or government reports pertaining to ships, plants and farms for additional supply-chain mapping. Our goal with this tool is to be a one-stop-shopping reference for journalists, advocates, researchers, law enforcement and company sustainability officers. By sharing data and investigative resources, the Outlaw Ocean Project seeks not only to expose wrongdoing, but to help create the transparency necessary for institutions, companies, and governments to be held accountable.