It’s possible that I shall make an ass of myself. But in that case one can always get out of it with a little dialectic. I have, of course, so worded my proposition as to be right either way (K.Marx, Letter to F.Engels on the Indian Mutiny)
The standard data migration tools offered by major Android manufacturers such as Samsung, Google and Xiaomi pose significant security risks, as researchers from the Institute of Information Security at Graz University of Technology (TU Graz) and Zentrum für sichere Informationstechnologie (A-SIT) have revealed in a recent study. Their research revealed that critical vulnerabilities in all the tools examined allowed attackers within Wi-Fi range to spy on private user data such as call logs, photos and login details.
Security risk associated with phone cloning
So-called phone clone tools or data migration tools are designed to make it easier to switch from an old smartphone to a new device. The aim is to transfer all data, settings and apps seamlessly from the old device to the new one. These tools usually establish a direct Wi-Fi (WLAN) connection between two smartphones without the need for an external server. However, research carried out by the Graz-based IT security researchers Florian Draschbacher, Lukas Maar, Lorenz Schumm, Rene Denifl, Lukas Treffner and Stefan Mangard now shows that this convenience comes at a huge cost to security.
In all the data migration apps examined from seven Android manufacturers – Google, Samsung, Vivo, Xiaomi, Oppo, Huawei and Honor – the team found vulnerabilities that would allow them, as attackers, to manipulate the transfer or eavesdrop on it. They simply had to be within radio range of the devices – indoors, that’s around 20 to 45 metres. Using inexpensive equipment costing less than 100 euros, they were able to eavesdrop on the data transfer. Places where large numbers of new mobile phones are set up every day, such as specialist electronics shops or mobile phone shops, are particularly vulnerable to such attacks.
Digital life in the spotlight
The potential risk posed by these vulnerabilities is enormous, as almost the entire contents of a smartphone are transferred during a data migration. As part of their investigation, the researchers were not only able to access text messages, contacts and photos, but also to extract highly sensitive information such as health data, login details for saved Wi-Fi (WLAN) networks and app passwords. In some cases, it was even possible to inject malware directly into the new device via app packages that had been tampered with during the transfer.
Billions of users affected – manufacturers respond
The significance of the discovery is evident from the installation figures. The apps examined have been downloaded more than 12 billion times in total and come pre-installed on almost every Android device. “Because these apps are pre-installed and are very convenient for transferring data to a new mobile phone, these security vulnerabilities have a huge impact,” says Florian Draschbacher. The team at TU Graz had already reported the vulnerabilities to the manufacturers in advance as part of a responsible disclosure process. They had confirmed the severity of the issues (including five security alerts classified as high). All seven manufacturers have now released security updates to address the reported vulnerabilities. The researchers urge users, before migrating data between two smartphones, to “ensure that the latest version of the data migration app is installed on both devices, and to always install all relevant updates.” In some cases, this may require updating the entire operating system.
The following Android manufacturers and data transfer apps were examined: Google Android: Android Switch Samsung: Smart Switch Vivo: EasyShare Xiaomi: Mi Mover Oppo: Clone Phone Huawei: Phone Clone Honor: Device Clone
This study is the latest in a series of globally significant cybersecurity risks that have been identified by the Institute of Information Security at TU Graz. For example, a team from the institute was involved in the discovery of the security vulnerabilities Meltdown and Spectre, which affected the vast majority of modern computer processors. In 2024, researchers discovered SnailLoad, which allows users’ online activities to be monitored by comparing the latency times of internet connections with the digital fingerprint of online content. They also discovered the attack method Collide+Power, in which an analysis of a computer processor’s energy consumption makes it possible to read data from its memory. However, the institute is also conducting research in the opposite direction. The Ascon algorithm developed by Maria Eichlseder, Christoph Dobraunig, Florian Mendel and Martin Schläffer, was designated the international standard for lightweight cryptography in 2023. In April 2026 TU Graz opened the Cybersecurity Campus Graz, a new facility dedicated to cutting-edge research and teaching in the field of IT security.
Monday, September 07, 2026
IFA 2026: Xiaomi wants its smart-home cars on European roads by 2027
Xiaomi is done being just a phone brand. At IFA 2026, it laid out plans to launch electric cars in Europe by 2027, all wired into a smart-home ecosystem it calls Human x Car x Home.
Xiaomi may still be best known for its smartphones. But at IFA 2026, the Chinese technology company presented plans for a future that no longer fits inside people's pockets.
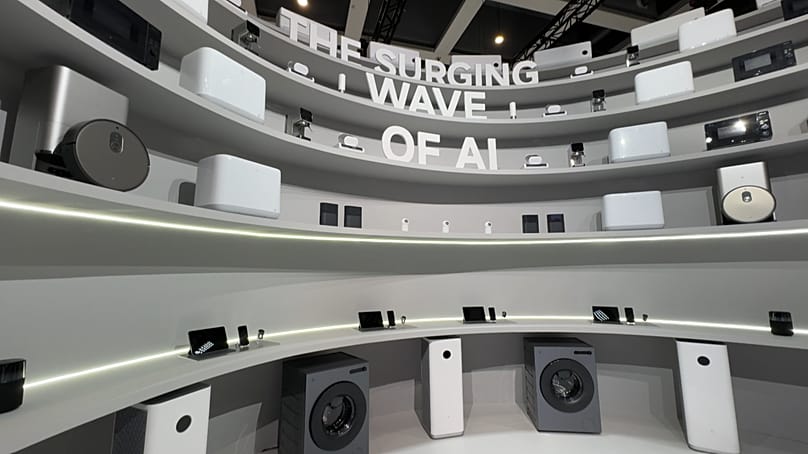
Home appliances and connected devices have become an increasingly important part of its business. Now, Xiaomi is putting greater emphasis on four wheels — and the shift is hard to miss at IFA.
Inside the company's exhibition space in Berlin, one of the first things visitors encounter is a futuristic-looking car carrying the familiar Xiaomi logo, but on a very different scale.
Xiaomi cars are already a familiar sight for consumers in China. Now the company wants to bring them to European roads too.
In that spirit, Xiaomi announced at IFA 2026 that it plans to launch its electric vehicles in Europe in 2027, marking the next stage of its expansion beyond smartphones and consumer electronics.
Xiaomi has also expanded its range of home appliances and connected devices. Euronews
But simply selling cars is not the company's ultimate goal. Like many of the technology companies exhibiting in Berlin, Xiaomi is increasingly focused on connecting different parts of everyday life.
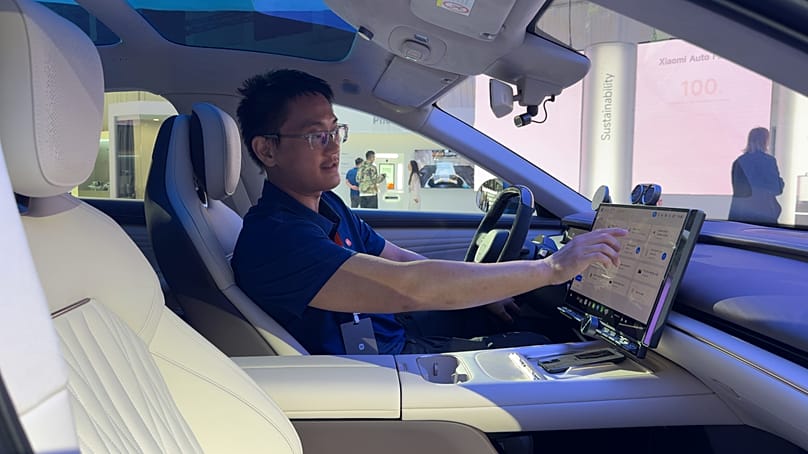
It calls its approach "Human x Car x Home", an ecosystem designed to link personal devices, the car and technology around the home. In practice, the idea is to let you steer your home from behind the wheel of your car.
Euronews took a closer look at Xiaomi's vision at IFA 2026 to see how that ecosystem is supposed to work.
'Human x Car x Home': The vision
Rather than treating the car as a separate product, Xiaomi wants to integrate it into the same connected system that already links devices around the home. The aim is for users to move between different environments while staying connected to the devices they rely on every day.
Euronews At IFA, Xiaomi presented its "Human × Car × Home" ecosystem, connecting cars, smartphones and home devices.
At IFA, Xiaomi demonstrated what that could look like in practice. From inside the car, users could control devices back at home, including opening and closing connected curtains and switching the air conditioning on or off.
This means the car could effectively become another control point for the smart home. Someone leaving work, for example, could adjust the air conditioning before arriving home, while other connected devices could be controlled directly from the vehicle.
Xiaomi says AI and its HyperOS operating system are intended to provide the technological link between these devices. Its longer-term vision goes beyond users manually controlling individual appliances, with AI eventually using contextual information to coordinate devices across the car, smartphone and home.
Relate
For Xiaomi, the car is therefore not only a new product category, but another part of a wider connected ecosystem — extending its technology beyond smartphones and the home and onto the road.
Alongside its more concrete plans, Xiaomi has also left room for imagination, exploring what could become possible further down the road.
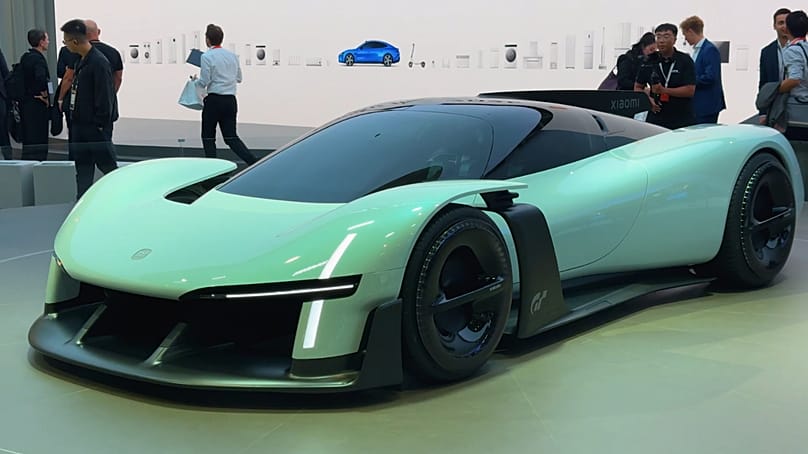
Xiaomi's Vision Gran Turismo Euronews
Among the concepts presented at IFA is the Xiaomi Vision Gran Turismo. The electric hypercar concept was developed for the Gran Turismo racing game series and explores ideas around design, aerodynamics and digital interaction.
For now, however, this vehicle remains firmly a concept rather than a preview of a production model expected to hit the road any time soon.
Local partners
But despite leaving room for experimentation, Xiaomi also made clear that its European ambitions go beyond concepts. At its IFA press conference on 3 September, the company took concrete steps towards its planned market entry.
During a signing ceremony, the company signed letters of intent with eight German automotive retail groups: Emil Frey Germany, the Ernst Dello Group, Autohaus Dinnebier, Hahn Automobile, the LUEG Mobility Group, Fett & Wirtz, SPT Avior and Penske-Jacobs.
Germany, however, is only intended to be the starting point, with Xiaomi planning similar partnerships in other European markets.
"Europe is a key market for our global strategy," Xiaomi Chief Marketing Officer Xu Fei said during the press conference.
The company is also planning significant investment to support this broader strategy. Between 2026 and 2030, Xiaomi says it intends to invest more than €24 billion globally in research and development, with a focus on areas including AI, operating systems, semiconductors, intelligent vehicles, robotics and smart manufacturing.
Thursday, August 20, 2026
CHINA
Unitree's viral dancing, rollerblading robots make a 600% stock market debut
Unitree, known for its dancing and backflipping robots, saw shares surge as much as 629% on its Shanghai stock market debut.
Unitree, the world's biggest humanoid robot maker, has kicked off its public listing with a bang, with shares soaring more than 600% during its trading debut.
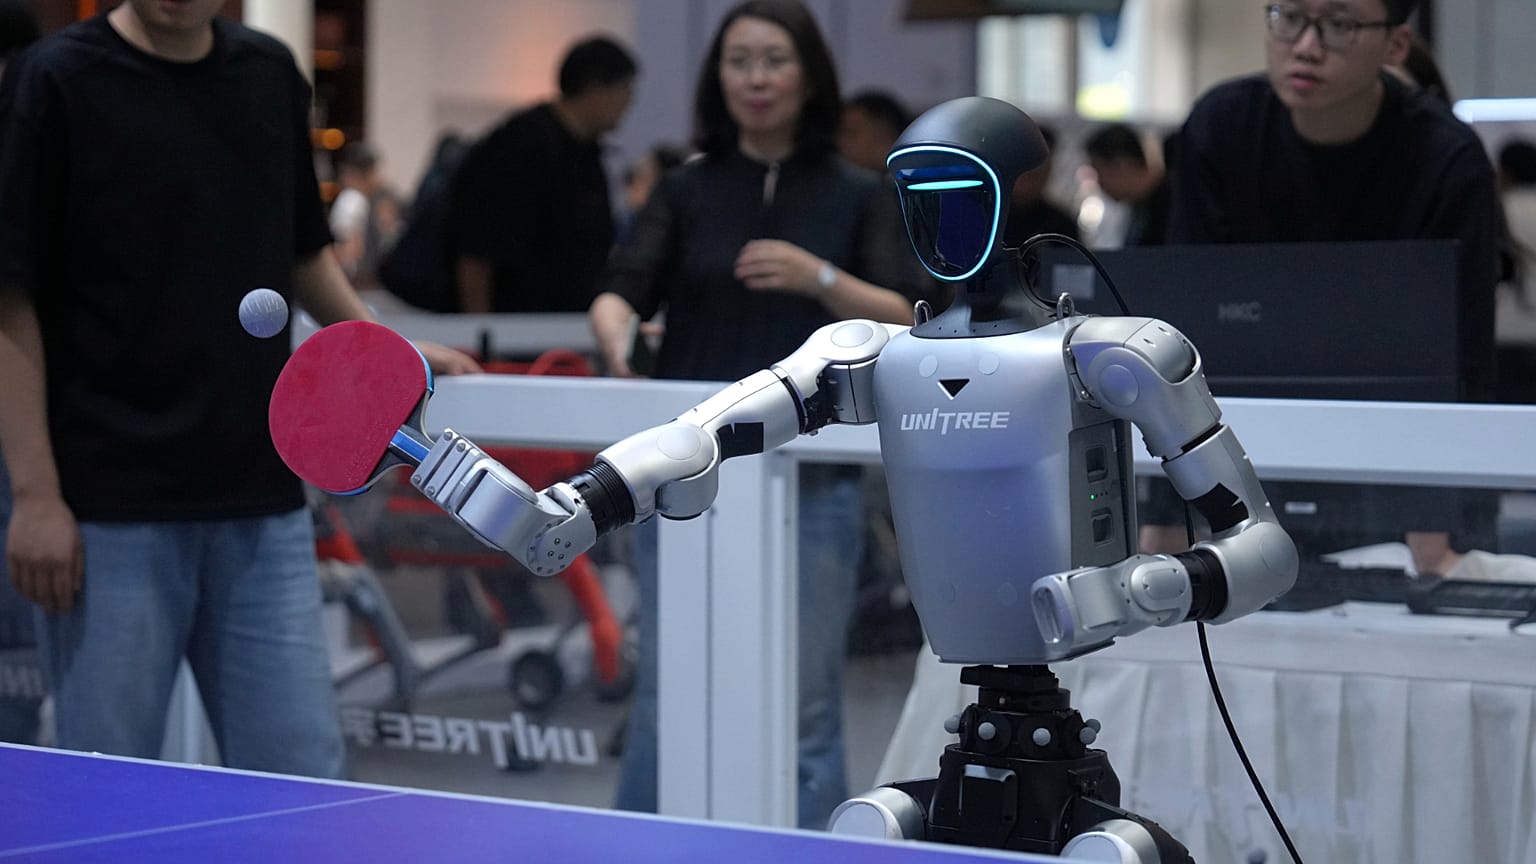
The Chinese company accrued immense worldwide popularity through viral videos of its robots acting as backup dancers for pop stars, alongside performing martial arts and extreme athletic feats. They can also rollerblade, play table tennis, and do backflips and vaults.
Shares surged from an initial public offering (IPO) price of around 150.8 yuan (€19.3) to as high as 1,100 yuan (€140.6) on Wednesday, a jump of more than 600%, although they settled at almost 500% later in the day.
Chinese retail investors formed the bulk of this extraordinary demand, with shares allocated to non-professional investors seeing demand exceed supply by thousands of times over.
Wang Xingxing, the founder of Unitree and its current CEO, still owns around a fifth of the business.
Unitree is exceptionally well-positioned to capture the rising interest in the robotics market, largely thanks to affordable hardware, such as its robot dogs and budget humanoids, which are available at a fraction of the price of their US counterparts.
This is largely down to robust local supply chains in Hangzhou, which keep manufacturing costs relatively low.
Riding on the back of spectacular demos and strong marketing, Unitree has also positioned itself as a high-volume company, ahead of several major US and European competitors. This has helped it turn a profit far earlier than most other early-stage robotics startups.
China also sees robotics as a key national priority in the effort to offset a shrinking workforce.
Relate
Robotics go global
With the global robotics industry seeing considerable advancements in recent years, investors are constantly searching for the next big winner. This is especially true given robotics' central role in advancing artificial intelligence through physical AI.
This allows AI to use robots for real-world learning and trial and error in tasks such as walking and gripping objects. It also develops better perception and reaction skills while creating rich new data loops for feedback and training material for smarter models.
The global market for humanoid robots is likely to reach $38 billion (€32.7bn) by 2035, according to Goldman Sachs.
At present, companies such as China's Unitree and UBTECH Robotics are among the few listed humanoid robot companies, while others such as Tesla, Xiaomi and Hyundai Motor have humanoid robot divisions of their own.
However, a few more Chinese humanoid robotics companies, such as Leju Robotics and Deep Robotics, are also making plans to go public soon.
Despite these advancements, some countries, including the US, still prefer to take a more conservative stance when it comes to importing or relying on foreign-made humanoid and quadruped robots, citing national security concerns.
Unitree has already been included on a list of Chinese military companies by the US Pentagon, which called it a "contributor to the Chinese defence industrial base," despite the company maintaining that its robots are for civilian purposes.
Wednesday, August 05, 2026
China draws up safety rules for autonomous vehicles
China has drawn up new rules for the growing autonomous vehicle industry – Copyright AFP/File Jade GAO
China has drawn up new safety rules for the growing number of autonomous vehicles on its roads, including a mandatory deactivation override, the government said Tuesday.
The standards taking effect July 1, 2027 will cover autonomous vehicles that require a human back-up driver, as well as independently operating vehicles such as the robotaxis made by US manufacturer Waymo.
Under the new rules, manufacturers will have to ensure autonomous systems can match the safety of human drivers, China’s Ministry of Industry and Information Technology said in a statement.
Buyers will also have to be informed of any limitations in autonomous systems.
The rules standardise interactions between humans and machines to “prevent risks of misuse or abuse”, the ministry said.
They will require that autonomous vehicles feature safe procedures to activate and deactivate automated driving, it said.
For cars with a human back-up driver, the autonomous system must monitor their readiness to take over.
Safety concerns and the cost of developing next-level systems have complicated progress in the introduction of of autonomous vehicles.
Beijing warned leading automakers that safety rules would be more tightly enforced after a fatal crash in 2025 involving a Xiaomi car in assisted driving mode.
The new rules follow a UN agency’s adoption in June of the first global regulations for fully autonomous vehicles, which China backed.
Sunday, July 26, 2026
Exploring the role of knowledge graphs and large language models in autonomous vehicle safety
In a new comprehensive review, researchers from Tsinghua University, Xiaomi EV, Beijing Institute of Technology, and University of Electronic Science and Technology of China examine how these two AI paradigms are being applied across the development, validation, and operation of autonomous driving systems, discuss their strengths and limitations, and further review their emerging synergy for more robust, interpretable, and trustworthy autonomous driving systems.
The team published their study in Communications in Transportation Research (https://doi.org/10.26599/COMMTR.2026.9640023).
Two complementary AI paradigms for autonomous driving safety
Autonomous vehicles must operate in highly dynamic and uncertain traffic environments. Although recent advances in sensing and learning have improved perception and control, current systems still face major challenges in scene understanding, risk reasoning, rare scenario handling, and explainability.
In the study, the research team examined two important AI approaches with complementary strengths. Knowledge graphs represent structured knowledge such as traffic rules, object relationships, causal chains, and expert driving experience, enabling explicit reasoning and traceable decision support. Large language models, in contrast, are more flexible in semantic understanding, contextual generalization, and reasoning over open-ended situations.
Comparison and synergy of these two AI paradigms for autonomous driving safety
The review shows that knowledge graphs and large language models offer different advantages for autonomous driving safety. Knowledge graphs are well suited for organizing structured knowledge and supporting explicit, interpretable reasoning, especially in tasks involving traffic rules, causal relations, and expert knowledge. Large language models, in contrast, are more flexible in semantic understanding, contextual reasoning, and handling open-ended situations, which gives them strong potential in complex and uncertain traffic environments.
Rather than treating them as competing approaches, the study further highlights their growing synergy. Researchers are increasingly exploring how structured knowledge can improve the transparency and reliability of large language models, while the flexible reasoning ability of large language models can expand how knowledge graphs are queried, understood, and applied. This emerging combination points to a promising direction for building more robust, interpretable, and trustworthy autonomous driving systems.
Communications in Transportation Research was launched in 2021, with academic support provided by Tsinghua University and China Intelligent Transportation Systems Association. The Editors-in-Chief are Professor Xiaobo Qu, a member of the Academia Europaea from Tsinghua University, and Professor Xiaopeng (Shaw) Li from University of Wisconsin–Madison. The journal mainly publishes high-quality, original research and review articles that are of significant importance to emerging transportation systems, aiming to serve as an international platform for showcasing and exchanging innovative achievements in transportation and related fields, fostering academic exchange and development between China and the global community.
It has been indexed in SCIE, SSCI, Ei Compendex, Scopus, CSTPCD, CSCD, OAJ, DOAJ, TRID and other databases. It was selected as Q1 Top Journal in the Engineering and Technology category of the Chinese Academy of Sciences (CAS) Journal Ranking List. In 2022, it was selected as a High-Starting-Point new journal project of the “China Science and Technology Journal Excellence Action Plan”. In 2024, it was selected as the Support the Development Project of “High-Level International Scientific and Technological Journals”. The same year, it was also chosen as an English Journal Tier Project of the “China Science and Technology Journal Excellence Action Plan Phase Ⅱ”. In 2024, it received the first impact factor (2023 IF) of 12.5, ranking Top1 (1/58, Q1) among all journals in "TRANSPORTATION" category. In 2026, its 2025 IF was announced as 12.7, maintaining the Top1 position (1/66, Q1) in the same category.
From Volume 6 (2026), Communications in Transportation Research will be published by Tsinghua University Press on the SciOpen platform with the official journal website at https://www.sciopen.com/journal/2097-5023. We kindly request that all new manuscript submissions be made through the journal’s submission system at https://mc03.manuscriptcentral.com/commtr. For any submission-related inquiries, please contact the Editorial Office at commtr_e@mail.tsinghua.edu.cn.
The graph illustrates the experimental speed profile used to evaluate one-pedal driving (OPD) and two-pedal driving (TPD). It features four distinct segments of speed fluctuations and transitional deceleration phases, simulating both high-speed and low-speed traffic conditions to test how following vehicles adapt to varying levels of disturbance.
With the rapid global shift toward electric vehicles (EVs), one-pedal driving (OPD) has become a standard feature. In this mode, the accelerator pedal alone manages both acceleration and deceleration. While celebrated for improving energy efficiency by up to 22% in urban environments, its specific impact on traffic flow stability and car-following behavior remained largely unexplored until now.
To address this gap, a research team at the University of Georgia conducted field experiments using a fleet consisting of one lead internal combustion engine vehicle and three following EVs equipped with OPD and Adaptive Cruise Control (ACC).
The team published their study in Communications in Transportation Research (https://doi.org/10.26599/COMMTR.2026.9640030).
“Our findings highlight a fundamental difference in how regenerative braking interacts with the control source,” says Handong Yao, an Assistant Professor in the College of Engineering at the University of Georgia. “In manual driving, the high sensitivity of the system can lead to overcorrections by drivers. However, when managed by automated systems like ACC, that same sensitivity allows for incredibly precise and stable longitudinal control”.
Manual Control: The Learning Curve
Under manual control, the study found that OPD produces more pronounced speed oscillations and sharper decelerations compared to traditional two-pedal driving (TPD). This is particularly evident among drivers who are novices to the one-pedal paradigm.
Increased Variability: Drivers struggled with fine speed modulation at low speeds, resulting in wider distributions of spacing and acceleration.
Quicker Response: Deceleration under OPD is initiated more rapidly because there is no mechanical lag from switching between the accelerator and brake pedals.
Adaptation Needs: The researchers suggest that during the early stages of OPD adoption, drivers may require additional training or supportive safety features, such as visual feedback, to mitigate operational noise and reduce potential risks.
ACC Integration: Unlocking Stability
The results took a dramatic turn when automation was introduced. When integrated with ACC, one-pedal driving yielded narrower distributions of speed, acceleration, and spacing than traditional two-pedal driving.
Smoother Flow: The ACC system leverages the zero-transition time of regenerative braking to respond more conservatively and smoothly to speed changes by precisely regulating regenerative torque.
Platoon Stability: This seamless control effectively attenuates speed perturbations throughout the vehicle string, suggesting that OPD-equipped automated vehicles could significantly improve overall traffic flow efficiency and stability.
“The synergy between one-pedal driving and smart infrastructure or automated systems is where the real potential lies,” explains Tianle Zhu, a Ph.D. student and the study’s first author. “By aligning these natural regenerative curves with automated guidance, we can move toward a more stable, energy-efficient, and safer mobility ecosystem”.
Communications in Transportation Research was launched in 2021, with academic support provided by Tsinghua University and China Intelligent Transportation Systems Association. The Editors-in-Chief are Professor Xiaobo Qu, a member of the Academia Europaea from Tsinghua University, and Professor Xiaopeng (Shaw) Li from University of Wisconsin–Madison. The journal mainly publishes high-quality, original research and review articles that are of significant importance to emerging transportation systems, aiming to serve as an international platform for showcasing and exchanging innovative achievements in transportation and related fields, fostering academic exchange and development between China and the global community.
It has been indexed in SCIE, SSCI, Ei Compendex, Scopus, CSTPCD, CSCD, OAJ, DOAJ, TRID and other databases. It was selected as Q1 Top Journal in the Engineering and Technology category of the Chinese Academy of Sciences (CAS) Journal Ranking List. In 2022, it was selected as a High-Starting-Point new journal project of the “China Science and Technology Journal Excellence Action Plan”. In 2024, it was selected as the Support the Development Project of “High-Level International Scientific and Technological Journals”. The same year, it was also chosen as an English Journal Tier Project of the “China Science and Technology Journal Excellence Action Plan Phase Ⅱ”. In 2024, it received the first impact factor (2023 IF) of 12.5, ranking Top1 (1/58, Q1) among all journals in "TRANSPORTATION" category. In 2026, its 2025 IF was announced as 12.7, maintaining the Top1 position (1/66, Q1) in the same category.
From Volume 6 (2026), Communications in Transportation Research will be published by Tsinghua University Press on the SciOpen platform with the official journal website at https://www.sciopen.com/journal/2097-5023. We kindly request that all new manuscript submissions be made through the journal’s submission system at https://mc03.manuscriptcentral.com/commtr. For any submission-related inquiries, please contact the Editorial Office at commtr_e@mail.tsinghua.edu.cn.
Since the start of this year’s World Cup, a highly notable shift has emerged on the stadium’s advertising boards. One can notice that the presence of Japanese manufacturing brands has visibly waned compared to the past. From the 1980s and 1990s through the turn of the century, Japanese companies were among the most ubiquitous sponsors of global sporting events such as the World Cup, the Olympics, and Formula 1. Brands such as Sony, Toshiba, Panasonic, Canon, Fujifilm, and JVC were long synonymous with televisions, cameras, VCRs, film, household appliances, and office equipment.
Back then, Japanese manufacturing possessed both the core technology and the end-consumer market. More importantly, it was a direct part of the daily lives of households worldwide. A mega-event like the World Cup, with its massive concentration of global viewers, was the perfect stage for Japanese consumer electronics and home appliance brands to flex their muscles. Today, however, a glance at the pitch-side ads reveals that the spotlight has largely shifted to service-sector brands from China, South Korea, and the United States, alongside capital from the Gulf states. While Japanese manufacturing still exists, it no longer commands the front row of the advertising hoardings.
ANBOUND’s founder Kung Chan believes that global manufacturing is undergoing a transition of momentum, and the conspicuous decline of Japanese manufacturing ads at the World Cup serves as a clear signal. Gone were the days when Japanese corporations completely dominated World Cup billboards. As one of the world’s premier showcases for global commercial power, the World Cup reflects deeper shifts. Companies willing to pay a premium for global exposure, those seeking to use the tournament to amplify their international presence, and those shifting away from mass-consumer branding all reflect broader changes in industrial structures, corporate strategies, and national competitiveness. The billboards may look like mere commercial marketing, but they reflect shifts in the power structure of manufacturing.
This shift is far from being an isolated phenomenon. According to statistics from fDi Intelligence, World Cup sponsorships were almost entirely dominated by American, Japanese, and Western European enterprises before 2006. Since then, however, the sponsorship structure has visibly pivoted eastward. At the 2022 World Cup in Qatar, the number of Asian sponsors surpassed that of Euro-American companies for the first time. Chinese corporate sponsorship accounted for a share comparable to that of U.S. companies for two consecutive tournaments, while Japanese sponsors were conspicuously absent. Looking at the 2026 World Cup, FIFA’s core partners include Hyundai-Kia, Lenovo, Coca-Cola, Visa, and Adidas, alongside the likes of Qatar Airways and Saudi Aramco. The emergence of Gulf enterprises like Qatar Airways and Saudi Aramco demonstrates that sports sponsorship is no longer just a corporate marketing tool. Instead, it now carries undertones of national image-shaping and the spillover of capital influence. By leveraging a global mega-event like the World Cup, Gulf states are packaging their energy wealth, aviation hubs, tourism services, and national brands together, transitioning from mere energy exporters into major players on the global commercial and cultural stage. This signifies that both the manufacturing representatives and the capital forces on the global business stage are changing. Where Japanese corporations once stood as the face of Asian manufacturing, Chinese electronics, South Korean automobiles, and emerging-market capital now occupy far more space.
It is worth noting that Japanese manufacturing has not simply collapsed. Rather, its center of gravity has undergone a major shift. In the past, Japan’s strength was on the consumer side. Products like televisions, cameras, audio-video recording equipment, home appliances, and automobiles faced ordinary consumers directly, making global exposure a natural necessity for these brands. Today, many Japanese enterprises have shifted to the mid-to-upstream segments of the industrial chain, concentrating heavily on semiconductor equipment, precision materials, industrial robots, machine tools, sensors, automotive components, and power devices. Companies like Tokyo Electron, Shin-Etsu Chemical, Murata Manufacturing, Keyence, Fanuc, and Yaskawa Electric remain vital to the global industrial chain. However, because their clients are primarily chip fabricators, automakers, and industrial firms, they do not need to repeatedly assert their presence in mass-consumer arenas like the World Cup. In other words, Japanese manufacturing has shifted from “selling to global consumers” to “selling to the global industrial chain”, moving from frontline branding to backstage technology.
There is a positive side to this as Japan maintains formidable barriers to entry in many high-end segments. In semiconductor materials and equipment, for instance, Japanese firms remain irreplaceable in fields such as photoresists, silicon wafers, inspection equipment, etching and deposition systems, and high-end components. The AI-driven semiconductor investment cycle also continues to offer opportunities for Japanese businesses. SEMI forecasts that global sales of semiconductor manufacturing equipment will grow from USD 133 billion in 2025 to USD 145 billion in 2026 and reach USD 156 billion by 2027, driven primarily by AI, high-end logic, memory, HBM, and advanced packaging. Taiwan, South Korea, and Mainland China remain the most critical regions for equipment investment. This indicates that the new momentum in global manufacturing no longer stems from traditional home appliances and consumer electronics but from chips, computing power, data centers, advanced packaging, AI servers, and high-end equipment, and these are the exact sectors where Japanese firms are still highly influential.
Yet, this is also where the problem lies. If manufacturing remains “backstage” for too long, its technical barriers may endure, but its global brand influence will inevitably wane. In the past, Japanese manufacturing represented a lifestyle: Sony for televisions, Canon for photography, JVC for video recording, Panasonic for home appliances, and Toshiba for office equipment. Today, the direct impression of Japanese manufacturing among many young consumers has faded; instead, they are far more familiar with brands like Apple, Samsung, BYD, Xiaomi, Hisense, TCL, Hyundai, and Kia. While Japanese enterprises still hold immense value deep within the supply chain, their brand aggressiveness on the consumer side is a shadow of its former self. For a manufacturing powerhouse, this is no trivial matter. Global competition in manufacturing is not just a battle over components; it is equally a competition over brands, channels, ecosystems, and consumer mindshare. Being an “indispensable supplier” is certainly important, but if it cannot continuously roll out products aimed at global consumers, its image as a manufacturing superpower will inevitably contract.
Japan’s Ministry of Economy, Trade and Industry (METI) admitted in its White Paper on International Economy and Trade 2025 that the volume of Japanese goods exported has declined and that the nation needs to develop new export goods, export enterprises, and export markets while increasing digital and service value-add. This effectively shows that Japan itself recognizes that its traditional export model is no longer sufficient. The dilemma facing Japanese manufacturing is not just about high costs, an aging population, or corporate conservatism. This also stems from product lifecycles being rewritten by new technologies. Japanese companies used to excel at perfecting hardware engineering, but they have generally been slow to react to smartphones, platform economy, software-defined vehicles, AI terminals, and digital services.
At the same time, Chinese manufacturing is becoming more and more noticeable. In the past, China acted primarily as the provider behind the scenes, such as supplying World Cup merchandise, jerseys, display screens, stadium seating, venue equipment, and construction machinery. The products were in the stadium, but the brands were not. Today, Chinese enterprises are entering the sponsorship frameworks, broadcasting systems, and global marketing arenas directly. Companies like Hisense, Mengniu, vivo, Wanda, and Lenovo have consecutively leveraged the World Cup to expand their international footprint. Behind this trend lies a transformation in Chinese manufacturing from exporting contract-manufactured goods to exporting brands, technology, and application scenarios. Chinese companies are no longer content with being mere suppliers. Instead, they want to build global brand recognition. Particularly in display equipment, major home appliances, smart terminals, new energy vehicles, power batteries, photovoltaics, and construction machinery, China has forged distinct advantages in scale, cost, supply chain integration, and iteration speed. This is the reason for the confidence that emboldens Chinese enterprises to step up to the advertising boards.
However, one should not jump to the simplistic conclusion that “Chinese manufacturing has won a total victory” merely because Japanese ads have dwindled and Chinese ads have multiplied. The reduction in Japanese manufacturing ads signals a retreat of its consumer-facing brands, but it does not mean its underlying technology has vanished. Conversely, the rise in ads from Chinese brands shows a stronger desire for globalization among Chinese firms, but it does not mean all core dependencies have been resolved. The most prominent advantages of Chinese manufacturing right now are scale and speed, while its shortcomings remain in foundational software, high-end industrial software, core equipment, advanced materials, precision components, global service networks, and brand trust. Especially in fields like semiconductors, aviation engines, high-end machine tools, medical devices, and industrial control systems, China still requires long-term accumulation. While advertising on billboards means more visibility, the deep recesses of the supply chain represent hard power. This distinction must be kept clearly in view.
South Korean manufacturing offers an alternative point of reference. The sustained presence of Hyundai-Kia within the World Cup sponsorship ecosystem demonstrates that South Korean enterprises have successfully held onto the global consumer brand lifeline. The hallmark of South Korean manufacturing is its ability to blend automobiles, electronics, entertainment, design, and national image. Samsung, Hyundai, Kia, and LG, coupled with K-pop, K-dramas, gaming, and K-beauty, collectively form South Korea’s outward-facing brand ecosystem. South Korea may not possess China’s manufacturing scale, nor Japan’s deep accumulation in materials and equipment, but it excels at packaging manufacturing into global consumer culture. This is a lesson worth learning for China. When Chinese enterprises venture abroad, they cannot rely solely on price and production capacity. What they must also address should include brand aesthetics, user experience, after-sales service, cultural communication, and localized operations. Otherwise, no matter how much is spent on advertising, it will remain difficult to truly crystallize into enduring global brands.
All in all, Kung Chan’s observation of manufacturing shifts through the lens of World Cup advertising offers a highly piercing entry point. World Cup billboards are not industrial reports, yet they visually display the shifting dynamics of global industrial power. Japanese manufacturing has largely receded into the backstage of the industrial chain, Chinese manufacturing is accelerating its journey to the forefront of global branding, South Korean manufacturing continues to fuse consumer brands with cultural exports, and the Gulf states are reshaping their national images through sports sponsorship. This evolution indicates that global manufacturing competition has expanded from pure product rivalry into a comprehensive contest encompassing technology, branding, capital, and national image.
Final analysis conclusion:
As the ads at the World Cup shift, the era of manufacturing is also changing. For China, being seen by global consumers is merely the first step. What matter the most is whether it can establish a firm foothold in core technologies, global services, brand trust, and supply chain organization. Billboards can let it being seen and heard, but a manufacturing superpower ultimately depends on the structural fortitude of its industrial system.
Yang Xite is a Research Fellow at ANBOUND, an independent think tank.
About Anbound Anbound Consulting (Anbound) is an independent Think Tank with the headquarter based in Beijing. Established in 1993, Anbound specializes in public policy research, and enjoys a professional reputation in the areas of strategic forecasting, policy solutions and risk analysis. Anbound's research findings are widely recognized and create a deep interest within public media, academics and experts who are also providing consulting service to the State Council of China.