World Nuclear News
Fresh record set for nuclear generation in 2025
The World Nuclear Association report includes an assessment of progress towards the widely-shared ambition - which 38 countries have signed up to - for a tripling of global nuclear energy capacity by 2050. It also sets out a series of policy recommendations.
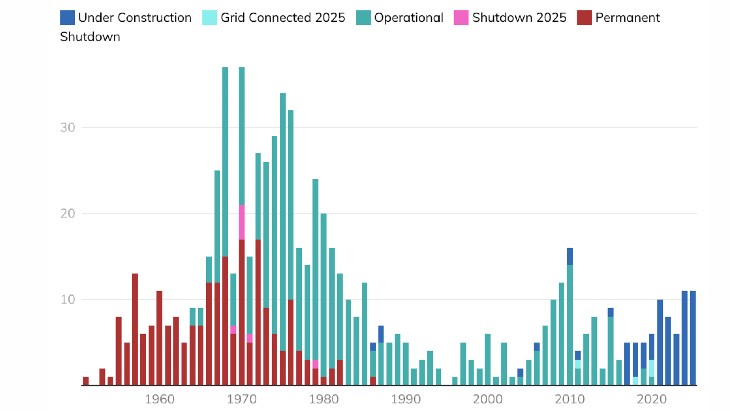
Focusing on the existing fleet, the report notes that there has been a recent increase in construction starts, as shown by the chart below, which shows how it has fluctuated over the past 75 years.
(Image: WNA)
It also finds that the reliability of nuclear energy plants remains high across the global fleet and across the life of reactors, even as individual units age. The average capacity factor was 83.7% in 2025 (a capacity factor of 100% would be if a unit generated electricity 24 hours a day 365 days a year).
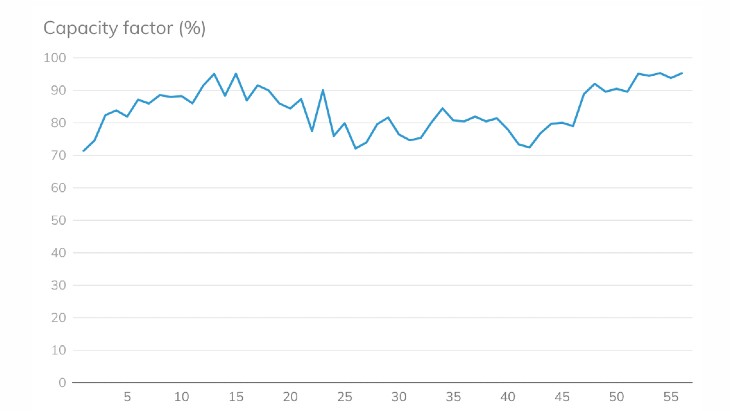
The capacity factor rises as the age of reactors passes 50 years (Image: WNA)
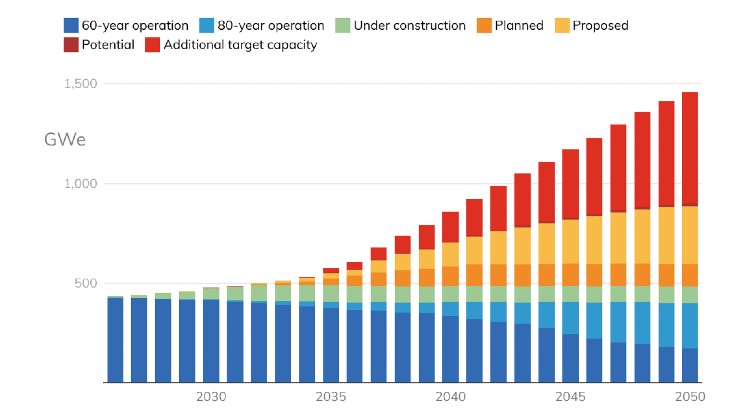
Looking ahead at the prospects for new nuclear capacity, the report projects that it could reach 1,457 GWe by 2050 if all national targets and goals are achieved and the existing fleet continues to operate. With current operating capacity being 423 GWe, that projected figure would be 200 GWe more than a tripling of the current levels.
New capacity under construction increased to 82 GWe, with eleven reactors starting construction in 2025. The combined total of planned, proposed and potential capacity increased to 416 GWe, reducing the gap between actual projects and government targets, although around 550 GW of proposed capacity by 2050 has yet to be translated into specific projects.
(Image: WNA)
As to where the new capacity would be located, the report found that the largest share of the new capacity would come from the established users of nuclear energy - the USA, China, France, Russia and India.
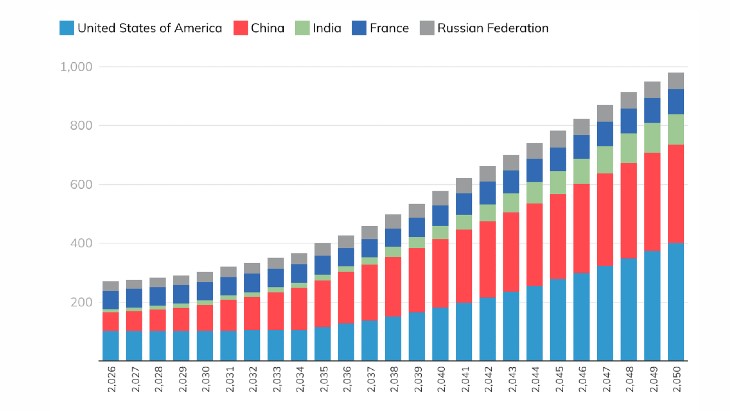
(Image: WNA)
World Nuclear Association Director General Sama Bilbao y León, said: "This is an extraordinary moment for nuclear energy. Reflecting on another year of record performance, and looking ahead to a future of record ambition, governments are clear: they need much more nuclear energy to address the interconnected challenges of energy security, affordability, competitiveness and climate goals.
"But ambition alone will not deliver 24/7 clean energy. That's why the Association has published recommendations that set the path towards tripling global nuclear energy capacity by 2050. We need to make full use of the existing fleet, complete reactors already under construction, capitalising on the acquired capabilities, commit to the next projects and move from individual projects to sustained programmes of deployment."
As well as reviewing the progress towards individual countries' targets, the report includes a series of policy recommendations for governments, industry, financiers and regulators.
These range from "establishing durable policy and investment frameworks, streamlining regulation and strengthening supply chains, to building the workforce, supporting proven reactor deployment and creating the programme-based delivery models needed". It also highlights that maintaining and extending the existing fleet is the fastest and most cost-effective ways to secure low-carbon electricity.
According to World Nuclear Association, "For the rest of this decade, the focus must be on turning national ambitions into credible project pipelines, supported by the institutions, investment, people and industrial capacity needed to deliver them."
IAEA's projections suggest there could be 1,000 SMRs by 2060
In Energy, Electricity and Nuclear Power Estimates for the Period up to 2060, the International Atomic Energy Agency (IAEA) raises its projections of the growth of future nuclear energy capacity for the sixth successive year, with it now forecast to more than triple by 2060.
At the end of 2025, there were 413 operable nuclear power reactors operating worldwide, generating 377.1 GWe, the IAEA said. In its high-case scenario, the agency projects that this figure could reach 1,045 GWe by 2050 GWe - up from the 992 GWe forecast last year. This year's projections continue to 2060 for the first time, with the nuclear generating capacity now reaching 1,284 GWe by that time, which would be 3.4 times the figure at the end of 2025.
The low-case projection for 2060 is for nuclear capacity to reach 696 GWe by 2060, and 641 GWe by 2050, up from the 561 GWe by 2050 forecast last year.
The publication, which is put together by an international group of experts, develops its estimates by considering all operating reactors, possible licence renewals, planned shutdowns and plausible and planned construction projects foreseen for the next few decades. The low-case assumptions are that current trends continue and there are few changes in laws, policies and regulations. The high-case assumptions include national intentions for expanding the use of nuclear power and the "high-case projection remains both plausible and technically feasible and notes the possibility for capacity to exceed this estimate".
Enabling factors, such as national policies, supporting investment and workforce development - plus regulatory collaboration and global harmonisation - would be necessary to help facilitate at least reaching the high case.
IAEA Director General Rafael Mariano Grossi, speaking at the 70th IAEA General Conference in Vienna, said: "The IAEA projections show the increasing role of nuclear power in meeting the world's growing electricity needs. To realise this potential, investment in new nuclear capacity and reactor lifetime extensions will be essential."
The role of small modular reactors - the first few of which are now online or under construction - is projected to grow rapidly, to encompass 28% of the 1,017 GWe of new capacity added under the high-case projection, or 23% of the 521 GWe that would be added under the low-case.
The IAEA's definition of a small modular reactor is for a capacity of up to 300 MWe, and the 100+ designs in development have a wide range of capacities, from a starting point of 20 MWe. Assuming an average capacity of 300 MWe, the low-case projects SMRs accounting for 120 GWe by 2060, which would be the equivalent of 400 new units. If those units averaged 250 MWe capacity it would mean 480 SMRs. Last year's forecast to 2050 had a 24% share for SMRs in the high case and 5% in the low case.
The IAEA projections - which are to 2060, rather than 2050 for the first time - include a breakdown of SMR deployments across regions, projecting that about 60% of new nuclear capacity in North America could come from SMRs. In South-Eastern Asia and in Latin America and the Caribbean, the figure is 40% in both the high and low cases.
Also key to achieving the projected growth of future nuclear capacity is extending the life of currently operating reactors, with the IAEA Energy Planner/Economist Jessica Callen-Kovtunova telling a media briefing that under the high-case scenario 70% of currently operating capacity remains in operation in 2060, while under the low-case scenario that proportion is reversed, with almost two-thirds of currently operating units retired.
The IAEA says that "a lifetime extension for an existing reactor, if it is viable, is one of the most cost-effective baseload low emission electricity sources and is of particular importance for regions with ageing nuclear fleets".
The role of finance is also seen as playing a big role. The document says: "The upward revision of the projections reflects growing recognition of the role that nuclear power can play in supporting energy security and long-term economic growth. There has been renewed engagement with nuclear power by international financial institutions, such as the World Bank Group and the Asian Development Bank, signalling a broader shift that other international financial institutions have begun to follow.
"Energy security and affordability concerns intensified following successive energy crises since 2022. Disruptions to oil and gas flows have major implications for both energy security and global energy markets. In response, interest in diversified electricity generation has grown, including interest in nuclear power."
The IAEA also reported that compared with 2024, nuclear electricity generation increased by 1%, although global electricity generation grew faster, by 2.7%, with nuclear's share of electricity generation falling from 8.7% in 2024 to 8.4% in 2025.
World Nuclear Association's World Nuclear Outlook Report, published last week, found that global nuclear energy capacity could reach 1,457 GWe by 2050 if all national targets and goals were achieved and the existing fleet continues to operate.
Podcast: World Nuclear Outlook Report's key findings
The World Nuclear Outlook Report outlines a record year for nuclear energy generation in 2025, highlights where that growth is coming from, assesses the progress towards ambitious future capacity goals, and also makes policy recommendations to help achieve them. Its author, Jonathan Cobb, joined the World Nuclear News podcast to discuss its findings in depth.
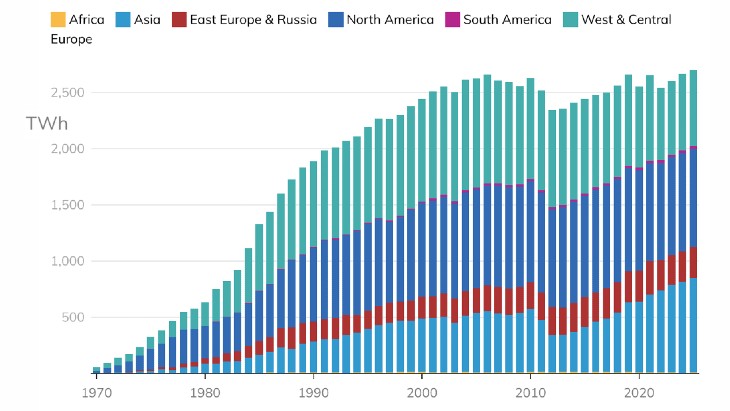
Nuclear reactors worldwide generated 2,702 TWh of electricity in 2025, beating the previous year's record of 2,667 TWh. And the positive trend is also seen in a recent increase in construction starts, as shown by the chart below, which shows how it has fluctuated over the past 75 years, says Cobb, who is senior programme lead, climate, at World Nuclear Association.
(Image: World Nuclear Association)
Cobb says: "That represents around 9% of world electricity. So we are seeing this increase in nuclear generation worldwide, principally at the moment in Asia, with other regions maintaining their levels of generation. But as we look to countries wanting to increase their nuclear capacity, and new build programmes coming into place, we would expect to see the nuclear generation rising in the future in all regions."
He also talks about the stats showing that the reliability of nuclear energy plants remains high across the global fleet and across the life of reactors, even as individual units age. The average capacity factor was 83.7% in 2025 (a capacity factor of 100% would be if a unit generated electricity 24 hours a day 365 days a year).
Looking ahead at the prospects for new nuclear capacity, the report projects that it could reach 1,457 GWe by 2050 if all national targets and goals are achieved and the existing fleet continues to operate. With current operating capacity being 423 GWe, that projected figure would be 200 GWe more than a tripling of the current levels.
New capacity under construction increased to 82 GWe, with eleven reactors starting construction in 2025. The combined total of planned, proposed and potential capacity has increased to 416 GWe, reducing the gap between actual projects and government targets. That means there is still about 550 GWe of capacity countries are targeting which has yet to become specific announced projects.
"So there is a need for governments, if they are going to reach the goals that they wish to reach, to take the measures and work with industry, work with finance community to bring on the plans for that additional capacity," he says.
Out of the ambitions for 1,457 GWe capacity by 2050, 1,303 GWe would be in countries which already have nuclear power reactors. There would be another 154 GWe of capacity that would be in countries that are either constructing their first reactors or are already planning to build reactors in the future, he says.
To help the process of achieving that goal, the report sets out 12 policy recommendations.
Cobb explains: "We have 12 connected policy priorities. They're not separate initiatives. The first is defining energy and sustainable economic policy. Governments need to give a clear, durable place for nuclear in national energy, climate, industry and development strategies and ensure that international frameworks recognise its contribution to security, resilience and decarbonisation. There's a need for work on financing and market design. Political risk needs to be reduced through long-term commitments. And you need to make sure that risks are allocated appropriately between public and private sectors.
"There are recommendations on regulation and permitting, on optimising the performance of existing reactors. Looking also at nuclear technology development and deployment. We also look very clearly at uranium and fuel supply, because it's obviously important if you're going to build a lot more reactors, to ensure that you have the mining, the conversion, the enrichment and fabrication all in place, expanding so it can meet the demand that those new reactors are going to generate. We also look at reprocessing and recycling for those countries that choose that route. For them, stable policy and predictable regulation is going to help improve resource use, strengthen fuel security.
"We also look at waste management, disposal and decommissioning. Every programme really needs an integrated, funded, long-term strategy, and we look at supply chain capability. Long-term order books can give suppliers the confidence to invest. Aligning standards and qualifying suitable industry-grade components could help broaden participation and lower costs. We need to look at industry policy and programme delivery. Nuclear projects should support regional development and high-value employment. But delivery also requires clear ownership, realistic schedules, collaborative contracts, and early supply chain involvement.
"And very much related to that is workforce and skills. Workforce planning needs to be put in place alongside programme design. That means expanding education and training, enabling international skills mobility, transferring expertise and creating retraining routes from adjacent industries needs to be put in place. And finally, of course, we need to bring the public along with us and other stakeholders. There needs to be public confidence and engagement. Trust is going to depend on accessible evidence about both the benefits and risks involved in projects, early stakeholder mapping and meaningful community participation."
So does Cobb think the tripling capacity target will be achieved? "I think there are some very good signs. What we have seen, even over less than a year since the last report, is that the number of planned projects has increased, the amount of under construction projects has increased. We are seeing that transfer from government goals into actual identifiable projects, and then into getting spades in the ground and starting construction. So we are starting to see that movement from ambition into action."
"The 2050 goal that was set may have seemed somewhat in the future, but it is less than 25 years away now. So we really, as an industry and as a society as a whole, need to be accelerating the steps that have been taken so far in order to deliver on those ambitions."
You can listen and subscribe on all major podcast platforms:
World Nuclear News podcast homepage
Apple
Spotify
Amazon Music
Episode credit: Presenter Alex Hunt. Co-produced and mixed by Pixelkisser Production
Cover Picture Credit: Adobe Stock/Vadym
Uranium companies see new chapter for the market

Kazatomprom could easily sell all its uranium output "into the East" - and new types of buyers need to be aware that the uranium market is in a new chapter rather than just another cycle, Kazatomprom Chief Strategy and International Development Officer Dastan Kosherbayev said on the sidelines World Nuclear Symposium 2026.
Kazatomprom has a diversified sales portfolio, with about half of the company's annual sales going to what it calls the East and the rest almost evenly split between Europe and the USA. Year-to-year, the appetite from the East continues to grow, and this is backed up by a concrete set of actions, Kosherbayev said during a panel session at the London conference, which had "From Ambition to Action" as its overarching theme. But this is not being matched in the West, he said, adding that Kazakhstan is "eagerly waiting for when one of the countries in the West will actually start delivering on nuclear capacity".
"We will do business with everyone who's willing to do business, and as long as it's fruitful for all the parties involved, we will be committed," he said.
While there were "excellent" fundamentals in place, Kosherbayev told journalists the national atomic company of Kazakhstan has to extract as much value as possible for its shareholders. "A lot of Eastern buyers see uranium as more of a strategic commodity and are less price-sensitive than Western buyers, with volumes of more concern to them than pricing.
"At Kazatomprom, we find ourselves in a situation where it's fair to say that we could have sold the entire volume of our production into the East and still there would be more appetite coming from the East," Kosherbayev said on the sidelines of the two-day symposium.
Cameco is a joint venture partner with Kazatomprom in the Inkai joint venture, in addition to production from its Tier 1 assets in Canada. Cory Kos, the company's Vice President, Investor Relations and Communications, said buyers were willing to accept premium pricing for reliable production from safe sovereign jurisdictions, but this is not yet at a level to incentivise Cameco to consider moving its Tier 2 assets - including mothballed assets in the USA - back into operation.
At this stage, Kos said, Cameco sees its Tier 2 assets as competitive with "greenfield" projects - although greenfield projects have a higher risk profile. "When there's a customer in discussions with a greenfield producer to say we will pay X to start that new mine in 2035, or 2036 … we'll be at the other end of the table to say, well, you could take a risk with that brand new producer who's never produced a pound … or you can come to us and we could restart these Tier 2 operations, bring those to the table, and we have alternative sources and such."
Kos also said new types of buyers - such as hyperscalers - were showing an interest in uranium. "We've got a few term sheets out to something, nobody's bought anything yet, but a few of the big names that you would know are poking around." Energy security, rather than cost, is the driver here, he said, even when companies are not clear on their own energy strategy just yet. Some such companies may target a strategy of actually building and operating a nuclear reactor to meet their electricity needs, others may consider securing electricity power purchase agreements or similar, while some will simply buy from the grid.
"But in each one of those strategies, they're all looking at it and saying, well, if I do, or a company that's running a reactor for me, needs uranium in a tight supply situation, maybe I should just buy some today … And looking at the supply demand scenario today, it doesn't look like that's too bad of an investment."
Deep Fission completes borehole demonstration
A full-sized prototype of the canister that will hold the Gravity reactor has been installed and then retrieved from a borehole using standard equipment already in commercial service in the drilling industry.

California-based Deep Fission is developing the Gravity reactor, a small modular reactor designed to be placed underground in an optimised borehole one mile (1.6 km) deep.
The company has announced that it has now successfully lowered the 20 foot (6 metre) canister to a depth of 100 feet inside a 34 inch (86 centimetre) wide borehole, aligned it, and brought it back to the surface, an emplacement and retrieval sequence that Deep Fission's deployment model depends on. The prototype canister is a full-size, non-nuclear replica of the canister designed to house the Gravity reactor core.

(Image from Deep Vision's video)
The process was carried out using standard commercial drilling equipment operated by a commercial drilling and rigging crew: nothing about the demonstration required equipment that had to be invented, custom-built, or adapted for nuclear service, the company said.
"The most important thing about this demonstration is what we did not have to do," Deep Fission CEO Liz Muller said. "We did not have to develop new technology. We used a rig and rigging that is commercially available in the field today, and our reactor uses pressurised water technology that has been operating in the nuclear industry for decades. Our innovation is in how we put proven pieces together, not in inventing something that has never been built. That is the difference between a science project and something you can deploy."
The demonstration took place on 3 September and is part of a commercial validation programme that also includes drilling, system integration, regulatory approvals and ultimately, commercial operation, the company said.
Proxima announces plan for German HTS production facility

The MoU covers the assessment of potential sites in Lower Saxony, establishing a milestone-based support and funding structure, facilitating permitting processes and developing partnerships with companies, municipalities and research institutions across the state. Around EUR140 million (USD46.5 million) in investment is planned for the first two project phases, running until the end of 2029. Proxima aims to finance the total investment equally through private capital and public funding, with the State of Lower Saxony providing EUR21 million, representing just under 30% of the proposed public funding contribution.
The planned production site, which will be the first-of-its-kind in Germany and Europe, will create an essential industrial foundation in Lower Saxony for Proxima's Alpha fusion demonstrator, its planned Stellaris power plant at the site of a former Gundremmingen nuclear power plant, and, ultimately, the production of stellarators at scale. Beyond supporting the stellarator supply chain, the High-temperature superconducting (HTS) manufacturing capacity would also serve other applications including high-performance electricity grids, medical imaging and treatment, advanced propulsion systems and other high-field magnet technologies. Under current plans, Proxima will require approximately 20,000 kilometres of HTS tape for Alpha and a further 40,000 kilometres for Stellaris.
"This plant enables Germany to retain manufacturing expertise and economic value, make its European supply chains more resilient and translate its world-leading stellarator research into an internationally significant industry," Proxima said. "By bringing together materials expertise, production processes, quality assurance, skilled workers and suppliers, it would create a critical upstream manufacturing capability with applications across a wide range of sectors while reducing dependence on overseas suppliers."
Proxima - which was spun out from the Max Planck Institute for Plasma Physics - said it is in discussions with several international technology partners about bringing established HTS manufacturing expertise and production capabilities to Lower Saxony.
"We are making Lower Saxony a pioneer in European HTS manufacturing," said Olaf Lies, Minister-President of Lower Saxony. "This will not only support Germany's ambitious fusion-energy goals, but also bring advanced manufacturing, new economic value, highly skilled jobs and technological expertise to our state, with the potential to generate positive innovation effects across many other industries. Lower Saxony will become, quite literally, a magnet for a new critical technology."
Francesco Sciortino, co-founder and CEO of Proxima Fusion, added: "HTS tape is one of the critical technologies needed to scale fusion rapidly at an industrial level. Alpha and Stellaris will create the demand required to build this manufacturing expertise locally. Lower Saxony has the industrial base, energy expertise and political determination to turn a supply-chain dependency into an enduring strategic strength for Germany and Europe."
HTS tape is a specialised metallic tape that becomes superconducting at relatively high temperatures. In its superconducting state, it can carry electrical currents with virtually no resistive losses, making it possible to build electromagnets that are both exceptionally powerful and compact. The magnets built from the tape are essential to stellarators: they generate the magnetic fields that confine and control the extremely hot plasma inside a fusion machine. This makes HTS tape a key enabling technology for fusion. By enabling more compact and powerful fusion machines, it supports not only the technical realisation of fusion energy, but also the development of cost-effective power plants. Currently, HTS tape is manufactured at industrial scale primarily in Asia.
A stellarator fusion reactor is different to a tokamak fusion reactor such as the Joint European Torus in the UK or the ITER device under construction in France. A tokamak is based on a uniform toroid shape, whereas a stellarator twists that shape in a figure-8. This gets round the problems tokamaks face when magnetic coils confining the plasma are necessarily less dense on the outside of the toroidal ring.
Tips from China's 56-month nuclear construction schedule

Speaking at World Nuclear Association's World Nuclear Symposium in London, Ma said the ambition for the world to triple nuclear energy by 2050 was clear, but the challenge would be on delivery.
State Nuclear Power Technology Corporation is a subsidiary of the State Power Investment Corporation (SPIC), and is involved in design, standardisation and fleet-based construction.
With China having the largest construction programme in the world - with 58 units currently under construction and a target of 150 GW capacity by 2035 - he said their experience had found four major challenges which needed to be met - "to deliver many projects in parallel, safely, on schedule and on budget" which was "a question for everyone" involved in the sector.
The first was design, where, he said, there was a need to "strike the right balance between fixing a standardised design and continuing to improve the technology. A design that changes too frequently disrupts construction, while a design that never changes will become outdated. Finding that balance is the first test of high-quality fleet-based construction".
The second challenge was to ensure the supply chain can match demand - the risk was that "long-lead critical equipment supply cannot match the scale of project demand ...These constraints can make it difficult to build multiple units in parallel and deploy our reactor series at scale."
The third area was management. "Managing one project is hard, managing many at once is harder. We need standardised management models that are replicable, and that reach deep into construction and installation," he said, as well as needing coordination of people and equipment across parallel commissioning programmes.
The fourth area of challenge he highlighted was the need to ensure "specialised talent development" was able to keep up with project growth. "Certified nuclear-grade welders and non-destructive testing technicians are in short supply, which constrains equipment manufacturing and construction progress alike."
He said that none of these challenges can be solved by a single project or a single company and "they are the common test of our industry" at scale.
On engineering and procurement, he said their practice was to have a standardised design with integrated feedback from construction, commissioning and operation. There is a Design Change board which "reviews every change through tiered approval" and their target was to have a "standard design reuse ratio" of above 80%.
On procurement, they consolidate orders from multiple projects to allow centralised procurement as well as having reactor-specific industrial chains and an "early warning mechanism for supply chain risk", with a backup plan for high-risk items. Their key target was to have a more than 93% first-time pass rate of equipment acceptance.
On construction, there is standardised management organisation, "with fixed-price contracts and strict control of project boundaries and design changes, and AI and digital tools that make construction less labour intensive ... and modular construction will optimise the work sequence, connecting design, procurement, construction and commissioning end-to-end".
He said that: "Through these measures we are working towards a 56-month construction schedule with a first-time pass rate of 95% for key processes."
On commissioning, he said "we have adopted a commissioning model led by the EPC contract with deep owner involvement ... which reaches 40% to 50% on new projects and 50% to 60% on expansion projects,". There was also a "cross-project commissioning manpower matrix" and "two-tier tools and equipment pooling and deployment across sites".
He said these all helped a fleet-based construction system which was "reliable, transferable and sustainable".
In conclusion, he said: "For our industry, fleet-based construction is no longer a choice - it's a question we must all answer and it's the surest bridge from ambition to action. SNPTC looks forward to working with partners around the world on technical standards, supply chain resilience, talent development and smart construction to turn the grand vision for our industry into reality."
New study sets 'robust' pathway for Honeymoon project

The company announced the findings of the study alongside an updated mineral resource estimate for the project, which is in South Australia. It withdrew its 2021 enhanced feasibility study for the project and initiated the new feasibility study last December, after a review confirmed that the underlying material assumptions had changed.
The new feasibility study reflects an updated mineral resource estimate, as well as incorporating additional drilling, detailed permeability and geometallurgical analysis, actual wellfield performance and advanced reactive transport modelling. Taken together, the company says, this has "materially improved Boss's understanding of the distribution of uranium mineralisation, permeability, hydraulic connectivity and the geochemical processes controlling uranium recovery".
Estimated resources now stand at 20.8 million pounds U3O8 at a 100 ppm cut-off (lower than the 250 ppm cut-off in the previous estimate), with 13.7 million pounds in the Indicated category and 7.1 million pounds U3O8 of Inferred resources. As well as the reduction in cut-off grade, the new figure reflects a change in estimation approach and the application of ISR-specific criteria for assessing the reasonable prospects for eventual economic extraction. The updated figure represents a decrease in metal of 15.1 million pounds U3O8 compared to the previous (2019) estimate.
The study also confirms a wide-spaced five-spot, 8 pattern, wellfield design as optimal for the development of the Honeymoon, where in-situ recovery (ISR) - also known as in-situ leach - is used to recover uranium. ISR is a method of mining uranium by dissolving and recovering it via wells. A wider spaced drilling pattern reduces the number of wells and associated surface infrastructure required and lowering the relative cost of development. The wider spacing and refined operational design enabled by deposit characteristics at Honeymoon result in significantly lower acid consumption, while increased effective recoveries enable more of Honeymoon’s extensive lower-grade mineralisation to be incorporated into the production plan, the company said.
Boss CEO and Managing Director Matthew Dusci said the new study "establishes a technically robust pathway for Honeymoon and delivers a fundamental step change in the operation’s cost structure", and has enabled the wellfields to be redesigned around the characteristics of the orebody. There remains "significant scope" for further optimisations as operating data continues to build, he added, with 45.1 million pounds U3O8 of resources at Gould's Dam and Jasons Deposit - which are not included in the NFS - providing "substantial potential to increase annual production and extend mine life".
In its guidance for FY2027 - which Boss Energy says is a transition year as Honeymoon moves from legacy wellfield spacing to the wide-spaced design - the company expects production of 1.25-1.30 million pounds U3O8.
ISR operations began at Honeymoon in 2011, but the mine was put on care-and-maintenance in 2013 by its then-owner Uranium One. Boss acquired the project in 2015.

