Sunday, September 13, 2026


Lithium’s inventory upheaval confounds industry, hits prices
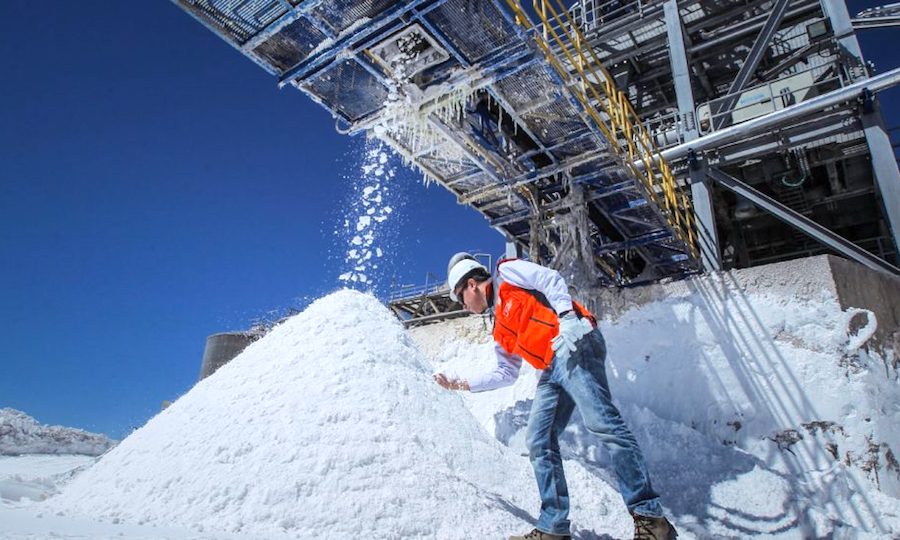

(Image courtesy of SQM.)

A surprise surge in lithium stockpile data — after a change in methodology — has confounded traders and weighed on prices, prompting some to call on authorities to step in.

Data released last week by SMM Information & Technology Co., leaning on a larger sample than previously, saw stockpiles jump to 175,000 tons. The previous figure stood at 78,800 tons. In response, prices for the most-active lithium carbonate contracts in China fell more than 14% across three days.

The lithium market has seen plenty of turmoil over recent years, but the sharp and unexpected jump in inventories raised fresh concerns about the true state of demand and about the challenges of predicting next steps for an opaque and still-developing market.

A dozen company officials, traders and analysts described an industry left baffled by the sudden jump, and fretting about reliable data. They all asked not to be named speaking on sensitive matters, but pointed to a petition circulating online demanding that relevant agencies investigate.

SMM said on Friday that its new method showed stockpiling among downstream cathode-material plants, while upstream smelters and battery plants showed destocking activities.  

The revised method includes sampling from more manufacturers and will also result in changes to some previously published data, SMM said. It added that estimates are derived from public information, market communications and its internal data models.

One official at SMM said the company may have underestimated the impact of its inventory shift, but had begun internal compliance checks to examine the issues. He also asked not to be named as those discussions are not public.

SMM did not respond to messages requesting comment.

“If data and prices provided by some third-party pricing platforms fail to objectively reflect the real market levels, we will adopt more market-oriented and diversified pricing methods to ensure that product prices are fair and reasonable,” Ganfeng Lithium said in response to investors query on a stock exchange platform.

(By Annie Lee and Alfred Cang)


Lohum ships first lithium ore from Zimbabwe, starts overseas mining
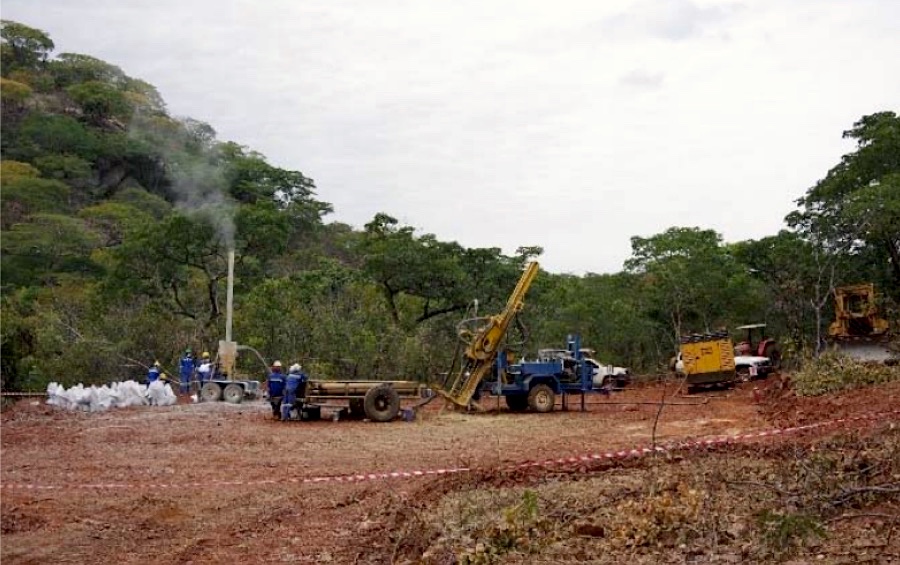

Zimbabwe is one of the top 10 lithium producers but currently produces only a fraction of the worldwide total. (Image courtesy of Prospect Resources | Investor Presentation at Mining Indaba, Feb. 2018. )

Lohum said on Wednesday it had dispatched its first shipment of lithium ore from Zimbabwe, marking the start of its mining operations in the southern African country and making it the first domestic company to produce lithium from overseas assets.

The Indian producer of sustainable critical minerals has secured rights to 10 lithium mining blocks in Zimbabwe’s Matabeleland South Province covering about 1,100 hectares, with estimated deposits of 30 million-40 million tonnes of ore.

The assets are expected to support production of around 300,000 metric tonnes of lithium carbonate equivalent and carry an estimated value of about $7 billion at current prices.

The company also holds an option to acquire up to 90 adjacent mining blocks.

Lohum said the move expands its presence across the critical minerals value chain, complementing its existing refining, advanced manufacturing and recycling businesses.

Chief Executive Officer Rajat Verma said securing lithium supplies at the source would help reduce battery costs and strengthen India’s electric vehicle supply chain.

It also plans to build processing capabilities in Zimbabwe rather than exporting raw ore.

(Reporting by Urvi Dugar in Bengaluru and Neha Arora in Delhi; Editing by Ronojoy Mazumdar)


Cuba property claims complicate rival bids for Canadian miner Sherritt


Credit: Sherritt International

The tussle for control of Sherritt International Corp, a Canadian mining company with deep ties to Cuba, has drawn in two unlikely players: Citigroup Inc. and Office Depot Inc.

Thanks to a byzantine series of mergers and acquisitions that go back almost a century, both companies hold claims on property seized during Cuba’s 1959 revolution and subsequently used by the Toronto-based nickel and cobalt producer.

Now, as Sherritt looks for a US backer to help get out from under Donald Trump’s punishing sanctions, those long-dormant claims are taking on new life. Worth more than $350 million on paper, they’re also shining a light on how laws designed to protect those who lost property to the communist regime have created a minefield for the new investment Cuba desperately needs.

“These claims are a veto, not a nuisance,” said Davy Karkason, founding attorney at Transnational Matters PLLC, which specializes in US sanctions and international arbitration. “If Citi says ‘no’ nobody gets to have the mine and Sherritt goes back to square one.”

Sherritt’s fate has been up in the air since May, when the US president issued an executive order designed to chase foreign companies out of Cuba. The Canadian miner initially said it would dissolve its joint ventures on the island, which include a mine and a power-generation operation, only to reverse course when a former adviser to Trump emerged as a potential savior.

In addition to talks with Gillon Capital LLC, the family office of real estate magnate and Republican Party patron Ray Washburne, Sherritt has been approached by a rival consortium that includes global commodities giant Glencore Plc and another Texas billionaire, oil tycoon Albert Huddleston. 

Washburne confirmed in an interview that he’s working to resolve at least one of the two claims as part of his pursuit of the company. “It’s the mine I’m concerned about,” he said this week in Dallas. Asked if he’d be willing to buy out the claim on the facility, he replied: “That’s right.”

Kyma Capital Ltd., Sherritt’s biggest creditor and part of the Glencore consortium, said the group is aware of the claims and “will seek to resolve them in the context of the applicable US legal and policy framework,” declining to elaborate on how a solution might be structured. Spokespeople for Huddleston didn’t respond to requests for comment.

Should the successful buyer find a formula that satisfies Citi and Office Depot, it could pave the way for untangling nearly 6,000 outstanding claims under the Helms-Burton Act that have made investing in Cuba treacherous, according to Pedro Freyre, the chair of international practice at Akerman LLC in Miami.

Any business that touches — even tangentially — on one of those claims is open to allegations of “trafficking” in seized property, the attorney said.

However, if the claim holders can be bought out, brought in as partners or paid some sort of lease, it might be “a model” for a number of the bigger registered cases, Freyre said. “Solving American claims under the Helms-Burton framework is the Gordian knot as it pertains to investing in Cuba.”

Trump has been pummeling the island with almost weekly economic sanctions as he tries to end nearly seven decades of one-party rule. The US has also imposed a de facto oil blockade on Cuba, worsening chronic blackouts. The energy crisis prompted Sherritt to halt operations at its mine in February. 

Citigroup is linked to Sherritt through a legacy equity stake in the Moa Bay Mining Co. that was seized by Fidel Castro in 1960 after he overthrew US-backed dictator Fulgencio Batista. Since 1994, the mine was operated by the Canadian company’s joint venture with Cuba’s state-owned General Nickel Co. SA. 

The Foreign Claims Settlement Commission — established to adjudicate claims by US nationals against foreign governments — valued the demand against the Moa mine at $88 million. It’s now held by Citi and is the third-largest of all certified cases, according to the US-Cuba Trade and Economic Council, which tracks the issue. The group estimates that, with interest, the 5,913 combined claims are now worth more than $9 billion.

A spokesperson for Citi declined to comment.

Office Depot’s connection to Sherritt goes back to 1927, when the Cuban Electric Co. was incorporated in Florida and started buying regional power plants in Cuba. By the 1950s, the company was providing more than 90% of all electricity to the island and was a major natural gas supplier to the capital of Havana.

When Castro swept to power, Cuban Electric was among the first foreign companies expropriated in the name of the revolution. Its majority shareholder at the time was American & Foreign Power Co. Inc., which in 1967 merged with another firm and became Ebasco Industries Inc. Two years later, paper giant Boise Cascade Co. bought Ebasco.

In 2003, Boise purchased OfficeMax and adopted its name. A decade later, OfficeMax merged with Office Depot and took its name. And in 2025, Connecticut-based private equity firm Atlas Holdings LLC bought Office Depot’s parent company, ODP Corp., and inherited the Cuba claim.

By that point, recovering the debt was so precarious that ODP had relegated it to two sentences in its most recent US regulatory filing.

“The company owns 88% of a subsidiary that formerly owned assets in Cuba, which were confiscated by the Cuban government in the 1960s,” ODP said. “Due to various asset restrictions, the fair value of this investment is not determinable.”

Initially valued at $268 million by the claims commission, the Cuban Electric claim has been growing at a rate of 6% annually. It’s the largest on the books and is almost three times more valuable than the next nearest one.

In 2000, Sherritt took a stake in Energas SA, a power-generation company it operates as a joint venture with two state-run companies. Those gas-fired installations formerly belonged to Cuban Electric. In July, Atlas sued Cuba’s state electricity company and Energas for $803 million under Helms-Burton. 

Atlas didn’t respond to emailed requests for comment. 

Karkason, the sanctions lawyer, said there’s a possibility that the suitors circling Sherritt’s nickel mine might be able to cut a deal that leaves Energas, and therefore Atlas and Office Depot, out of it. 

Washburne indicated that’s his intent. “I don’t really care about that,” he said of Sherritt’s power business.

John Kavulich, president of the US-Cuba trade council, said the miner is one of the “poster children” of the investment quagmire that Helms-Burton created. And the successful resolution of its case could be a “miracle of miracles” that resolves both the largest and third-largest certified claims. 

No bidder for Sherritt will get the Trump administration’s blessing “unless they have the approval of the certified claimants,” Kavulich said. “It’s sort of a race for these parties to cut a deal.”

(By Jim Wyss, Ari Natter and Sybilla Gross)

EU scrutiny of Anglo-MMG nickel deal tests China stance


Niquelândia processes both nickel and manganese from Codemin and Barro Alto sites. (Image courtesy of Anglo American.)

China-backed MMG is urging European regulators to approve its $500-million purchase of Anglo American’s Brazilian nickel business, in a case that could test how far Brussels will go to limit Chinese control over strategic resource supply chains.

The European Commission (EC) is investigating whether the acquisition could allow MMG to divert Brazilian ferronickel away from Europe, potentially raising costs for stainless steel producers. EU regulators are expected to issue a formal warning over the transaction next week.

“Ultimately, we’re confident that DG COMP will put geopolitical considerations aside and judge this on the data,” Troy Hey, MMG executive general manager of corporate relations, told the Financial Times, referring to the commission’s Directorate-General for Competition.

The case reaches beyond a conventional competition review as Europe tries to reduce its reliance on China for metals and minerals following Beijing’s export restrictions on a range of materials. Ferronickel is not classified as a critical mineral, but European steelmakers are concerned that increasing Chinese ownership of overseas production could leave the industry more exposed to supply disruptions or economic pressure.

Supply concerns

MMG agreed in February 2025 to acquire Anglo’s Brazilian nickel business, including two ferronickel operations and two greenfield projects. The Hong Kong-listed miner is controlled by state-owned China Minmetals.

The commission said late last year that the transaction could give MMG the ability and incentive to divert ferronickel supplies away from Europe, potentially weakening the competitiveness of the region’s stainless steel producers.

MMG disputes that assessment. “The independent data commissioned by DG COMP is very clear and consistent,” Hey told the FT. “There is no ability to foreclose the market, nor is there any incentive to do so.”

Anglo has also argued the transaction should be cleared without conditions, pointing to expanding ferronickel production from other suppliers and European customers’ ability to switch sources. It said EU restrictions on Chinese steel imports also mean Chinese stainless steel cannot simply be redirected into Europe and should not be considered a competitive threat.

Brazil and Indonesia are notable ferronickel producers, while China does not produce the material, according to price reporting agency Fastmarkets. China is instead a major producer and consumer of nickel pig iron, another feedstock used in stainless steel manufacturing, while European producers also rely heavily on recycled material.

Critics argue those headline supply figures understate the difficulty of replacing Brazilian ferronickel. Nickel content, product quality, reliability and carbon intensity vary between suppliers, potentially making alternatives more costly or unsuitable for some European manufacturers. Brazil’s heavy reliance on hydroelectricity also gives its production a relatively low carbon footprint.

Wider stakes

The transaction is also attracting scrutiny outside Europe. Brazil’s competition authority launched an investigation following a complaint by CoreX Holding, an industrial group and regional competitor.

Opponents say regulators should consider the acquisition against the broader competition among major economies for control of raw materials and escalating trade tensions between the US and China.

That argument presents Brussels with a difficult choice. Competition authorities must assess the transaction on its market effects while European policymakers are simultaneously trying to reduce strategic dependencies and strengthen domestic industrial supply chains.

Blocking or imposing conditions on the acquisition could signal that ownership and geopolitical supply risks are becoming more important considerations in European resource deals. Clearing it without conditions would reinforce MMG and Anglo’s argument that concerns about Chinese control do not outweigh the available evidence on ferronickel competition.

At SMM, ABS Says the Best Green Investments are Agility and Efficiency

ABS SMM
Courtesy ABS

Published Sep 7, 2026 2:17 PM by The Maritime Executive


In a panel event just before the opening of SMM 2026, the American Bureau of Shipping updated its outlook for the state of green shipping and came away with a new conclusion: success doesn't depend on picking the right winning fuel - it depends on making the right capital decisions, preparing for multiple scenarios, investing in people and execution capacity, and staying ready to adapt. 

At present, future fuels are constrained by a hard market reality: charterers want the least-cost quality option. One owner told ABS that not one customer had been willing to pay anything over direct regulatory cost in the last three years.

"We want to decarbonize. Very few customers, on the other hand, are willing to pay a meaningful premium for it," explained Rostom Merzouki, Vice President of Sustainability at ABS. "That means there is no guarantee that greener vessels will earn more revenue." 

In this commercial environment, the watchword of the moment is efficiency, he says. Inefficient tonnage incurs present-day costs, and not just in fuel consumption. In Europe, FuelEU and ETS charges now add up to as much as $9 million per vessel per year on Asia-Europe trade lanes. Outside of the EU, vessels with the worst CII ratings charter at a discount to better B-rated ships, and sell at an even steeper discount of up to 15 percent. 

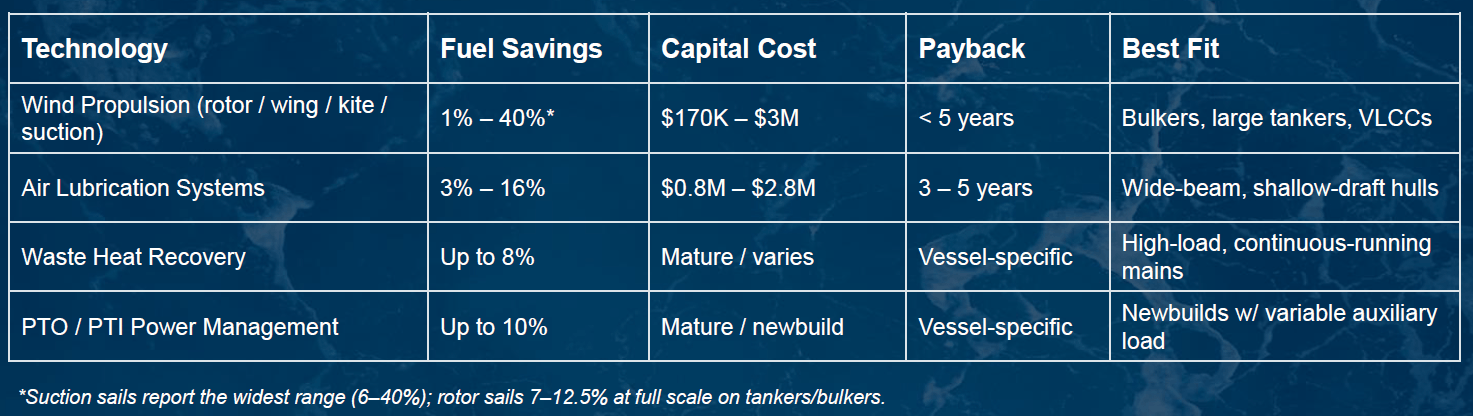
"Fuel efficiency remains the most resilient investment available today. It creates value regardless of which fuel wins, which regulation emerges in the field," he said. "Significant value can already be achieved through the technologies that are available now, like wind-assisted systems, air lubrication, waste heat recovery, digital optimization, predictive maintenance, and advanced voyage management."

Courtesy ABS

Capturing those savings requires "organizational readiness" - the staff capacity to adapt and execute - and a willingness to strike while the iron is hot. Supply chain capacity for efficiency retrofits may be limited by 2030, he says, when more and more operators may have to schedule yard periods to improve vessel fuel economy. Those jumping on the efficiency opportunity in 2027-28, he said, may be more likely to secure economical terms - and can abate the steep base-case compliance costs of the IMO NZF, if it enters into effect.

"Those waiting for more certainty may discover that certainty arrives after the available capacity is gone," he cautioned.

Contrary to conventional wisdom, investing in efficiency now may even be a better idea than casting the dice on a form of dual-fuel propulsion, depending upon fuel type and vessel trading pattern. "In many cases, investing in efficiency generates a stronger business case than investing in fuel flexibility that cannot be fully utilized," he said. 


First LNG Carrier with Two Wind Sails Named Ahead of Commissioning

LNG with wind sails
Fujin Sailor built by MOL and operating under charter to Chevron is the first LNG carrier and the first vessel with two rigid wind sails (MOL)

Published Sep 10, 2026 7:21 PM by The Maritime Executive


Japan’s Mitsui O.S.K. Lines celebrated the naming of the first LNG carrier fitted with rigid sails, which is also the first vessel to be fitted with two of the sails. The vessel, named Fujin Sailor, was built at Hanwha Ocean’s Geoje, South Korea, shipyard and, when delivered at the end of the month, will begin operating under a long-term charter to Chevron.

Development of the ship required a collaborative effort between MOL, Chevron, and Hanwha Ocean to address the unique challenges of fitting the sails to an LNG carrier. They had previously highlighted that for tradability, the installation position of the Wind Challenger rigid sails aims to minimize impact on the existing design of membrane-type LNG carriers. They said it would enable the unchanged retention of the existing mooring arrangement and thereby minimize impacts on ship-to-shore compatibility, together with limited impact on the vessel's windage area.

It is the first application of a design concept that was approved in 2024 after MOL and its partners conducted a risk assessment that comprehensively evaluated factors such as the placement of the sails, their impact on visibility, emergency operation procedures, and other safety measures, to add the technology to an LNG carrier. It also worked with GTT (Gaztransport et Technigaz), which holds the patents on the technology for the LNG tanks, for the evaluation of the impact on the cargo tank due to the sail installation.

The vessel is 295 meters (968 feet) with a capacity for 174,000 cbm of LNG. It uses an Everllence (MAN Energy Solutions) main engine and is also fitted with air lubrication for the hull and shaft generators. The telescoping rigid sails are made of fiber-reinforced plastic. Each sail consists of three panels and, when fully extended, stands approximately 49 meters (160 feet) above the deck near the bow of the ship. Each is about 15 meters (49 feet) in width. The first images of the ship appeared in May as it was outfitting after the sails were installed.

It is the fourth vessel that MOL has outfitted with its wind sails, after two coal carriers and a bulker. Plans call for a second, similarly sized, LNG carrier to be delivered later this year, also fitted with two Wind Challenger sails. It will be operating under charter to Tokyo LNG Tanker Co., a subsidiary of Tokyo Gas. The vessel is also being built by Hanwha Ocean at the same shipyard.

MOL has currently committed to installing the Wind Challenger rigid sail on a total of 11 vessels. It has also ordered six bulk carriers, each to be fitted with one rigid sail. They are being built by Japan’s Oshima Shipbuilding Co.

It is a further demonstration of the growing trend to leverage wind-assisted propulsion more broadly in commercial shipping and in more categories of ships. Maersk and Anemoi Marine Technologies recently agreed to the first test of a wind rotor aboard a containership. That installation is scheduled for mid-2027.


bound4blue Secures Bureau Veritas Design Assessment for Model 3-24 eSAIL

bound4blue's eSAIL® technology gains independent validation from Bureau Veritas.

bound4blue Secures Bureau Veritas Design Assessment for Model 3-24 eSAIL®

Published Sep 12, 2026 12:04 PM by The Maritime Executive


[By bound4blue]

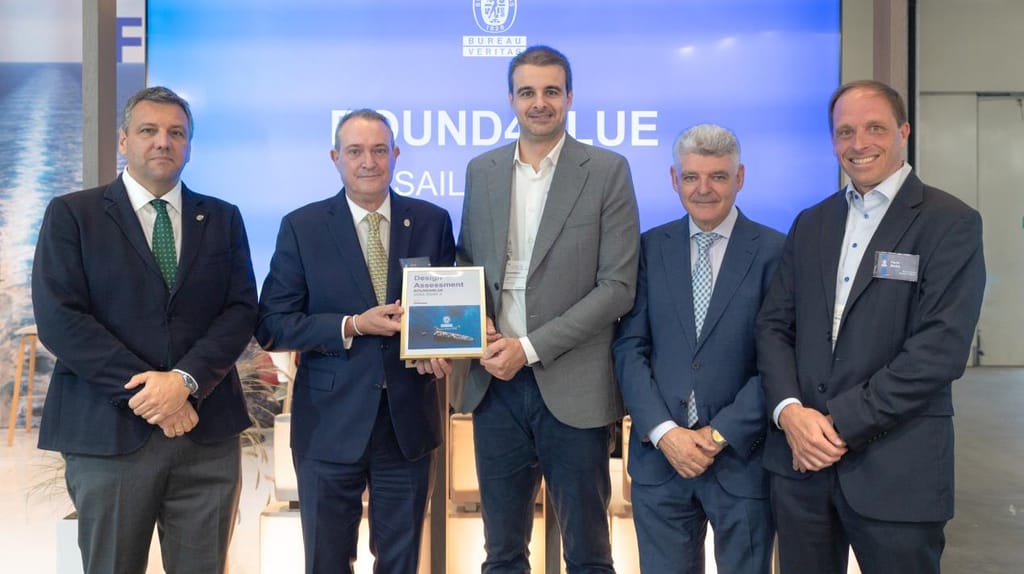
bound4blue has received a Design Assessment from Bureau Veritas Marine & Offshore for its flagship Model 3-24 eSAIL®, developed to maximise the contribution of wind propulsion on larger vessels.

Presented during a handover ceremony at SMM 2026 in Hamburg, the assessment confirms that the design has been independently reviewed against Bureau Veritas' technical requirements, providing further confidence for shipowners looking to deploy proven, scalable wind propulsion solutions.

bound4blue’s eSAIL® suction sail technology has made significant strides forward across multiple shipping segments in the space of the past year, with more than 50 units now ordered and installations completed onboard 13 vessels.

The Model 3 range spans heights from 24 metres to 36 metres, with the 3-24 becoming the first commercial installation earlier this year onboard Klaveness Combination Carriers' newbuild MV Baltazar. The sails feature an expanded surface area and optimised aerodynamic profile, ensuring even the largest ships can take advantage of compelling commercial and regulatory gains.

“As the market matures, confidence becomes just as important as innovation,” says José Miguel Bermúdez, CEO and co-founder of bound4blue. “So, as wind takes its place within mainstream fleet investment, independent assessments really do play an increasingly important role in differentiating and substantiating technical solutions.

“Here at bound4blue it’s been a focus since day one. We are committed to engaging with leading Class societies to demonstrate the quality and potential of our proprietary technology. By doing so we provide owners, yards and wider industry stakeholders with the reassurance they need to embrace the wind revolution and unlock significant environmental and business benefits. We’re delighted to achieve this latest recognition from Bureau Veritas as we continue to cement our position as a trusted industry partner.”

The Model 3-24 builds on bound4blue's proven Model 2 platform, retaining the company's hallmark technical simplicity for straightforward installation and autonomous operation.

eSAILs® work by utilising boundary layer suction to draw air across an aerodynamically optimised surface and generate propulsive force up to seven times greater than rigid sails of the same size, while requiring far less maintenance. The result is significantly lower fuel consumption, reduced CO? emissions and improved operational efficiency. In addition, the non-ATEX technology supports compliance with a growing range of environmental regulations, including FuelEU Maritime and the EU Emissions Trading System (EU ETS), while contributing towards improved Carbon Intensity Indicator (CII) performance and EEXI compliance.

Speaking of the Design Assessment process, David Barrow, SVP for Western Europe and Americas at Bureau Veritas Marine & Offshore, comments: “Wind propulsion is becoming an increasingly important element of the maritime industry's decarbonisation journey, and independent technical assessment helps provide confidence as these technologies continue to mature and scale. Through this Design Assessment, Bureau Veritas is pleased to support bound4blue in advancing safe and reliable innovation, helping shipowners reduce emissions while maintaining robust technical standards.”

eSAILs® have emerged as a solution of choice for many of shipping’s leading names, including companies such as Maersk Tankers, Eastern Pacific Shipping, Odfjell, Louis Dreyfus Company, and many more.

Designed as a simple, plug-and-play system for both retrofits and newbuilds, bound4blue suction sails operate alongside conventional propulsion systems while also supporting the adoption of future fuels such as methanol and ammonia, helping shipowners integrate complementary sustainability solutions into their decarbonisation strategies.

eSAILs® are market proven to deliver double-digit fuel savings, with typical payback periods of less than five years.

The products and services herein described in this press release are not endorsed by The Maritime Executive.

 Poten: VLCC Rates Hit Unprecedented Levels Amidst Mideast Conflict


Tanker owners should take advantage of the current market, which may never happen again, says Poten & Partners

Press handout / file image courtesy China COSCO

Published Sep 11, 2026 
 by Erik Broekhuizen / Poten & Partners

Participants in the tanker industry are no strangers to market cycles combined with extreme volatility. However, even seasoned veterans are looking at current developments in the market and scratching their heads. What is happening is truly unprecedented. It begs the question: What is driving this market and, more importantly, how sustainable is it? In this Tanker Opinion we will focus on the market for Very Large Crude Carriers (VLCCs), the most volatile and visible tanker segment.

Just to provide a little context, VLCCs are large crude oil tankers, with a carrying capacity of two million barrels, They are the main vehicle for long-haul seaborne crude oil transportation. As per September 1st, the global VLCC fleet consisted of 928 vessels, with an average age of 13 years. VLCC earnings are notoriously volatile, driven by supply and demand dynamics in a highly competitive market.


Chart 1 shows VLCC Time Charter Equivalent earnings over the last 15+ years (monthly averages in $/day). In July 2008, at the tail-end of the shipping “super cycle”, VLCC rates hit almost $200,000/day. On the back of China's extraordinary growth, shipping markets were exuberant, and owners had lined up at Asian shipyards to order more capacity. The orderbook ballooned. In late 2008, the global financial crisis hit, sending the world economy into a tailspin, taking the shipping markets with it. By mid-2009, tanker rates had dropped below $20,000/day.

The market has gone through a few more cycles since then. The next time the market closed in on $200,000/day was in April 2020, at the onset of the Covid-19 pandemic. Saudi Arabia flooded the oil markets after Russia refused to make the deep production cuts needed to address the demand destruction resulting from the pandemic lockdowns. The oil glut that followed quicky filled onshore tanks and raised demand for floating storage, boosting VLCC rates. This rate boom was also followed by a long period of depressed earnings. A recovery was triggered by Russia’s war on Ukraine, but that benefited Aframaxes/Suezmaxes more than VLCCs.

This brings us to the current rate spike. The war in the Middle East and the subsequent closure of the Strait of Hormuz, recently followed by significant restrictions transiting the Bab el-Mandeb Strait, have pushed VLCC rates to levels that we have never seen before. Earnings on the benchmark AG-Far East route averaged $600,000/day in August and reached more than $800,000/day in September to date.

It should be noted that these rates are for voyages originating within the Arabian Gulf. Due to the hazards associated with traversing the Strait of Hormuz, only a few owners are willing to take that risk, leading to sky-high rates. However, VLCC rates on other key routes are very high as well. Vessels loading in the Gulf of Oman, just outside the Strait of Hormuz, can earn $450,000/day. Even VLCCs that stay far way from the conflict zone can earn exceptional returns: $380,000/day for West Africa – Far East and $275,000/day for U.S. Gulf to Asia.

Not surprisingly, the exceptional spot rate environment has had an impact on time-charter rates and vessel values as well. Values for modern secondhand vessels are much higher than prices for newbuildings. A 5-year-old VLCC (if you can find one) will set you back $158 million, while you can order a new vessel for $129 million. The reason for the discrepancy is simple: You can employ a newly acquired vessel immediately in the red-hot spot market, while you have to wait several years before a newbuilding is delivered from the shipyard. And while you know what a vessel can earn in the market today, the future rate environment is much more uncertain. If history tells us anything, it is that periods of exceptional rates are usually followed by periods of low earnings, especially if the high earnings have spurred an ordering bonanza (Chart 2).

So, what’s next for the VLCC market? Opinions differ. Some people look at the unusual set of circumstances that triggered the current rate bonanza and with an eye toward the high orderbook (40% of the current fleet), they see another bust following this boom within a few years. Others are more sanguine considering the age profile of the fleet and the large contingent of sanctioned vessels that could be sidelined once the geopolitical conflicts are resolved. On top of that, restocking and a diversification trend away from the Middle East could create a higher ton-mile demand baseline. In the meantime, owners should take advantage of the current market. This may never happen again!

This post appears courtesy of Poten & Partners.


Alphaliner: Economic Pressures to Push Carriers to 27,500 Gigamax Boxships

giant containership loaded with record 22,000 boxes
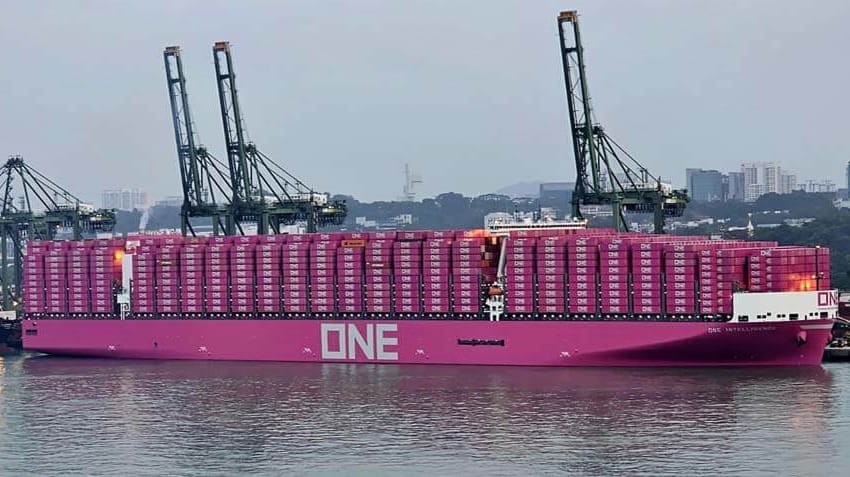
Just a few years ago, ONE was claiming records when it loaded more than 22,000 TEU in Singapore (ONE)

Published Sep 9, 2026 6:52 PM by The Maritime Executive


Do you want to supersize that containership may soon be the question shipbuilders and owners are contemplating, according to the consultants at Alphaliner. While the industry has plateaued at ultra-large container vessels, Alphaliner sees the elements that could easily lead to a new, ever-bigger class of Gigamax container vessels.

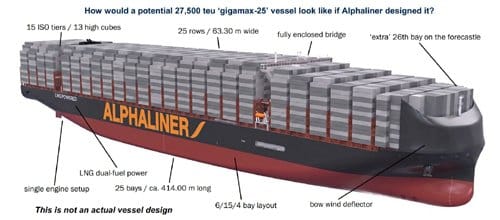
The consultancy is dusting off hypothetical concepts it presented five years ago, saying that market factors may just make the timing right for the new, bigger ship. It foresees a time by 2030 when the world’s top carriers could “theoretically deploy at least one 'full set’ of next-generation containerships on the East-West mainlines.”

“Increased cost pressure might prompt some of the largest carriers to reconsider their fleet strategies,” writes Alphaliner. It predicts some of the carriers will “opt for a novel ship type that is slightly larger than the current capacity record holders.”

The industry has a strong history of moving through these size categories. It went to the 18,000 to 19,000 TEU vessel for economies of scale. The next jump was to 23,000 to 24,000 TEU, but according to Alphaliner, for about a decade now carriers have stuck with that level. The ships are about 400 meters (1,312 feet) in length and have a beam of 61 meters (201 feet). It fits through the Suez Canal, and ports are adapted to handle this size of vessel. Shipyards and naval architects have toyed with the available space, and by making small changes to loading patterns and systems, they have squeezed the capacity by at most a few hundred boxes. The largest official TEU rating now stands at just over 24,300 boxes. 

Carriers have discussed bigger ships, but so far none has made the move. They said the 24,000 TEU load seems "about right" for the market and the operating factors.


Alphaliner's hypothetical concept for a 425+ meter container vessel with 27,500 TEU capacity


The consultants at Alphaliner, however, are answering the question of why carriers might finally jump the current barrier.

“Especially in very long-haul East-West mainlines,” says Alphaliner, “factors like the increasing price of fuel and the introduction of carbon emissions taxes will give bigger ships a competitive edge in the long run.”

Its Giamax concept would be incremental, adding one hold or possibly two 40-foot bays beyond today’s 400-meter ships. They forecast a length of 425 meters or more, and that would give the ships a capacity of 27,500 TEU.

They believe that the ports that have already adapted to the 24,000 TEU ships would be able to absorb these slightly larger vessels. The applications would be limited, however, as many ports, such as in the United States, cannot handle even the 24,000 TEU ultra-large vessels.

Alphaliner is not the only one working on theories for the next generation of giants. China’s Shanghai Ship Research and Design Institute and projects looking at the future of nuclear-powered containerships have also shown the potential to leap the 24,000 TEU barrier.

The concept of going to bigger ships seems to fit with the trends in the industry. As the ships get more expensive to build and operate, more boxes will rebalance the economic equation and potentially help with the anticipated wave of older ship retirements that has long been predicted. 

The container segment already has a record orderbook as carriers continue to order new ultra-large vessels. Alphaliner points out that over a relatively short period of time the industry’s capacity has soared from 23.2 million TEU to a current 34.1 million TEU. It is up 47 percent, and deliveries from the orderbook are likely to continue to drive capacity in the sector.


After a Leak, Troubled Ferry Glen Sannox No Longer Runs on LNG

CalMac
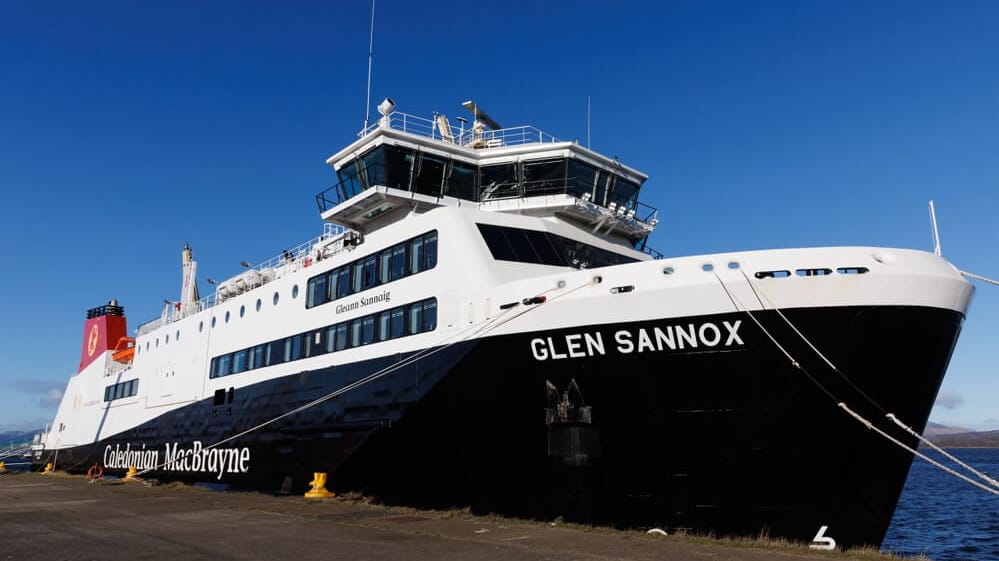
File image courtesy CalMac

Published Sep 11, 2026 9:43 AM by The Maritime Executive

The Scottish ferry Glen Sannox was billed as an environmentally-friendly LNG powered alternative when it was first ordered in 2014, and the builder and the operator invested heavily in bringing its LNG fuel system online, a factor in the vessel's years-long delivery delay. But after a serious gas leak incident last year, it is no longer using the high-spec system and has switched to running on diesel, according to a new investigation by BBC. 

On June 3, 2025, Glen Sannox began a routine crossing from Troon to Brodick, Arran. During the crossing, gas alarms sounded and the port engine automatically cut out, a safety response to an abnormality in the supply of natural gas fuel. The crew switched to diesel and investigated the matter further when they reached the pier in Brodick; no serious issues were found and the vessel departed for the return journey as usual. 

Later that evening, while the vessel was under way back to Troon and running on gas once more, a high-pressure LNG vent valve failed. Over the course of 12 minutes, it released 700 kilos of gas out to the exterior of the ship through a vent pipe on the starboard side. The size of the leak and the location of the vent - just forward of a ventilation intake - meant that a small quantity of gas was drawn back inside the ship, not enough to cause harm but enough to provoke concern.

The crew did not initially recognize that a leak had occurred, and they attempted to restart an engine before they discovered the root cause of the incident. The crew had to manually close the electrically-operated valve for the return journey. That appears to have been the last time that the ship ran on LNG, and the vessel's LNG fuel tank has been empty since late last year.

The operator's internal investigation report - obtained by BBC - found that the vent valve may have been damaged through contact with a loose component, possibly linked to the ship's severe vibration issues when operating astern. It did not have a monitoring sensor or position indicator at the time; that safety function has since been retrofitted. The OEM had previously issued three service memos suggesting that the valve be upgraded or replaced, and reinstalled with extra care in order to prevent loosening of fasteners.

In a statement, operator CalMac said that it has taken remedial action and that the ship is safe to run on LNG, but has not done so for the sole reason of speeding up its return to operations. At the time, CalMac had other serious issues to contend with, notably a persistent problem with hull cracking

The Glen Sannox saga has had many twists and turns, and the BBC's revelation is just the latest. Shipyard Ferguson Marine started work on the CalMac ferry in 2015, went bankrupt after serious design flaws emerged, and was nationalized in 2019. After rework, budget hikes and personnel changes, the ferry finally entered service in January 2025, six years behind schedule and four times over budget. It has been repeatedly out of operation for repairs since delivery. 


Photos: Deconstruction of MSC Baltic III Wreck Nears Halfway Point

wreck removal Canada MSC Baltic III
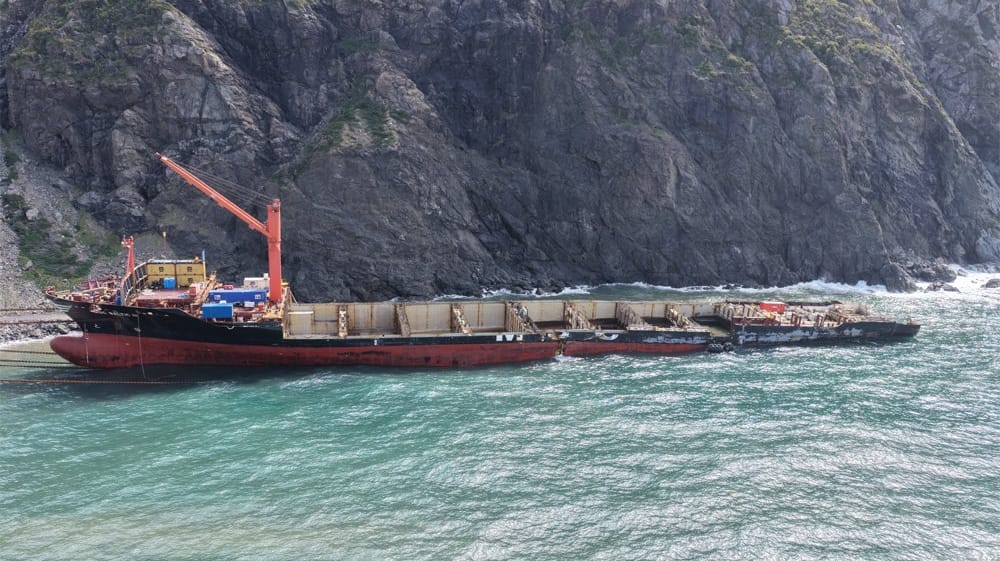
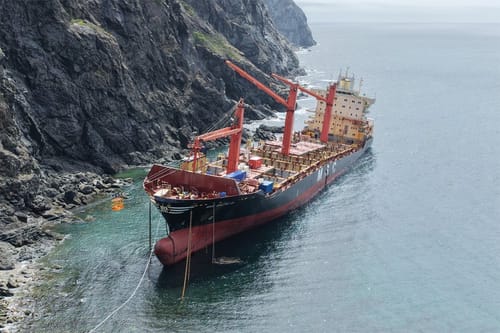
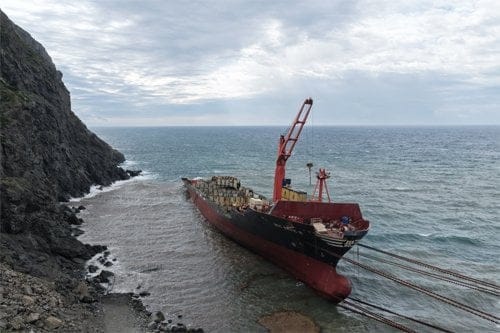
40% of the tonnage of the MSC Baltic III has now been removed in the deconstruction operation (Photos courtesy of Canadian Coast Guard)

Published Sep 10, 2026 2:28 PM by The Maritime Executive


The Canadian Coast Guard reports that the team from Resolve Marine continues to make good progress on the removal of the wreck of the MSC Baltic III. The 33,767-dwt vessel blacked out and was driven ashore in Newfoundland during a storm in February 2025.

Approximately 40 percent of the vessel’s tonnage has now been removed and sent to a recycling facility. The Coast Guard says that 4,200 tonnes have been removed, with pictures showing the deconstruction proceeding down from the vessel’s structure deck. Efforts in the second half of July removed the deckhouse and bridge as well as the cargo equipment and the hatch covers. By the end of July, the Coast Guard reported that the superstructure and cargo removal operations were completed.


Picture from early July illustrates the progress in the removal operation (Canadian Coast Guard)


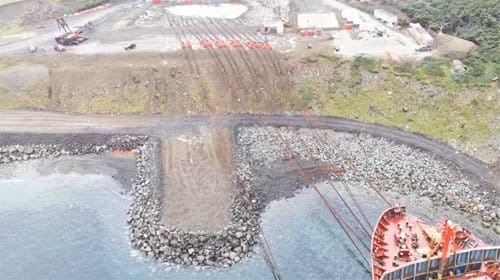
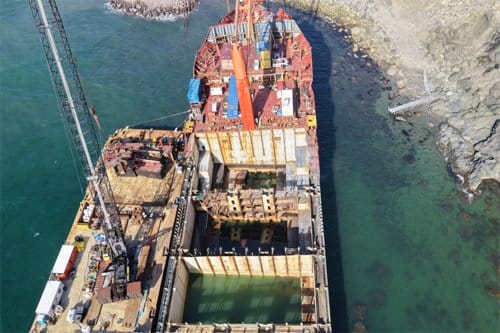
Resolve Marine is working both to continue to deconstruct the vessel and to move it forward onto the shore in the remote cove west of Corner Brook, Newfoundland. Pictures show a barge alongside as the deconstruction continues, and the Coast Guard reports a scrap pad was recently completed on the shoreline to support a shoreline crane for the lightering operations.

Large chain pulls have succeeded in moving the hulk approximately 53 meters (more than 170 feet) forward toward the shoreline. The vessel was 207 meters (679 feet) in length. The pulling operation is continuing during high tides for the added buoyancy on the remnants of the hull. 


Chains attached at the bow are being used to pull the wreck forward (Canadian Coast Guard)


The onboard fuel and other pollutants had been removed during the first phase of the salvage operation in 2025, but the Coast Guard reports efforts are continuing to deal with residual fuel on the ship. There have been some tar balls removed from the shore, and recently a slight sheen was observed outside the wreck. The Coast Guard expected there would be some issues during this phase of the operation due to the residual fuel, and it reports an absorbent boom has been placed inside the holds to help prevent the release of pollution.

Resolve Marine said the operations would continue until winter weather set in across the area. It plans to remove as much of the vessel as possible this year, but said the operation would likely not be completed until 2027. After the ship is removed, the project will be restoring the shoreline.

MSC Mediterranean Shipping and its insurers are paying for the salvage operation under Canada’s principle of “polluter pays.”


Pad was completed for a shoreside crane for the deconstruction as the hull is being pulled forward (Canadian Coast Guard)

A floating crane and barges are being used in the deconstruction effort (Canadian Coast Guard)