It’s possible that I shall make an ass of myself. But in that case one can always get out of it with a little dialectic. I have, of course, so worded my proposition as to be right either way (K.Marx, Letter to F.Engels on the Indian Mutiny)
Wednesday, September 23, 2026
Prysmian, Rio Tinto partner to bring low-carbon aluminum to Amazon data center
Italian cable maker Prysmian (MIB: PRY) said on Friday it had partnered with Rio Tinto (ASX: RIO) to supply electrical cables made with low-carbon aluminium for an Amazon (Nasdaq: AMZN) data centre in Ohio.
The cables will use aluminium produced with ELYSIS “inert-anode” technology, which Prysmian said eliminates direct greenhouse gas emissions from the smelting process, releasing pure oxygen instead.
Project is the first known use of inert-anode-smelted aluminum in a data center, the company said.
“The use demonstrates that the carbon footprint of data centers can be reduced at the raw material level,” it added.
Prysmian will manufacture the cables at its Sedalia, Missouri facility.
The project builds on the collaboration announced by Prysmian and Rio Tinto in March 2026.
Joern Tinnemeyer, Vice President of Data Center Engineering at Amazon Web Services (AWS), linked the initiative to the company’s 2040 net zero target.
(Reporting by Mirko Miorelli, editing by Matt Scuffham)
Big iron ore miners deplete reserves faster than they replace
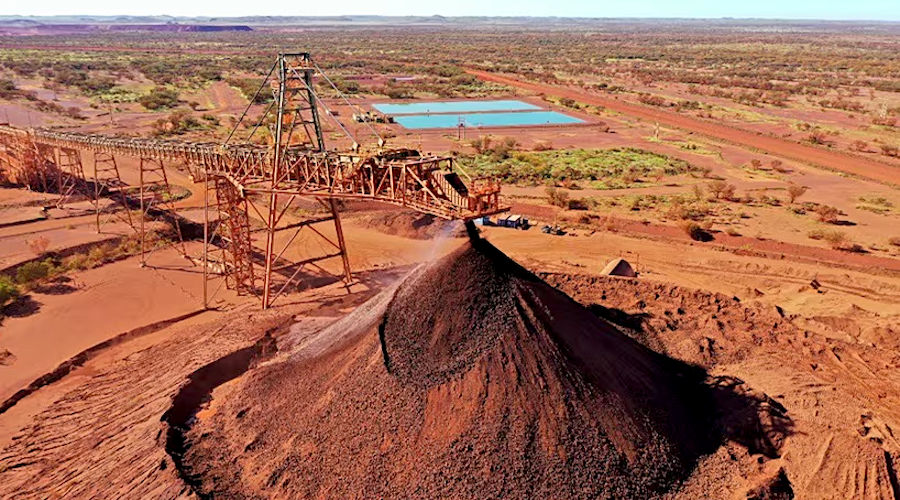
Ore at Jimblebar open-cut pit iron mine in the Pilbara region of Western Australia. (Image courtesy of BHP.)
The world’s biggest iron ore producers are depleting ore reserves faster than they can replenish them, as the cost and complexity of developing replacements continues to rise, according to Wood Mackenzie Ltd.
The six largest iron ore producers, which includes BHP Group and Rio Tinto Group, collectively depleted 11.1 billion tons of ore reserves that could be sold between 2016 and 2025, the consultancy said in a report released Thursday. Only three replaced the volume they mined over the period, and some spent five times more than others to add new reserves, it found.
The industry is increasingly facing an issue with grade depletion, which occurs when the average iron ore content in a mine drops as it ages and requires operators to dig deeper and invest more to extract. Miners are now reaching a point where it’s no longer about growth, but keeping operations running.
“The main challenge for the current iron ore industry is rising costs to maintain existing production,” said Mihir Vora, Wood Mackenzie’s research director for metals and mining. “The industry is investing to sustain production, but it is having to work harder to stand still.”
Costs for major miners have roughly doubled for some companies since 2016, Wood Mackenzie said. Cash margins across the industry peaked in 2021 and have since settled at around $50-$60 a ton, shrinking the margin to absorb rising costs and falling prices.
The analysis also found ore grades had fallen by as much as 1.6 percentage points among some miners since 2016. Higher-grade material is increasingly required to offset the depletion of lower-grade ore, while impurity levels, including alumina, are rising in some products.
(By Katharine Gemmell)
Deluge of copper arriving in US leaves New Orleans with logjam
There’s nothing outwardly remarkable about the journey of the Nord Norfolk, a Liberian-flagged bulk carrier sailing across the Atlantic toward New Orleans.
But the boat is loaded with roughly half a billion dollars of African copper, the highest market value for a single commodity shipment ever recorded by analytics firm Kpler. It’s part of a rush of copper to US shores ahead of potential import tariffs, a deluge that’s key ports are struggling to absorb.
The Port of New Orleans — a key metals gateway and major hub for CME Group’s Comex copper warehouses — is already largely full, according to people familiar with the matter. And that’s before a total of around 100,000 metric tons more of African and South American copper they say is due to arrive in September and October.
“We are seeing serious congestion at marine terminals in the New Orleans area, causing delays for loading copper and other metals and steel to trucks and railcars,” said Anton Posner, chief executive officer of logistics-services provider Mercury Resources. His firm is sending metal up the Mississippi by barge instead.
Port of New Orleans didn’t respond to an emailed request for comment.
The $500 million boatload and the New Orleans logjam are part of a long drama playing out in the global copper market as traders brace for President Donald Trump to decide whether to expand copper import levies to refined metal. He hasn’t done so months after a decision was expected, and the metal is still pouring in for now.
The strength of US copper imports has been the key force behind a record-breaking rally in copper prices, with the global benchmark set on the London Metal Exchange climbing about 50% since Trump first formally proposed tariffs on the metal in February last year. US futures have rallied even more sharply, creating huge arbitrage profits for the traders and producers that have been shipping copper to the US in record volumes.
But in recent weeks the gap between US and international prices has narrowed as doubts grow about whether Trump will ultimately push ahead with tariffs. In turn, the question of whether US imports will slow has become a crucial one in all corners of the copper industry — from investors weighing whether copper’s record rally can be sustained, to Chinese manufacturers who’ve seen costs to secure their own imports surge as copper has gravitated toward the US.
One measure puts the arbitrage gap now at $169 a ton, versus $789 at this year’s height, and it has fluctuated a lot since Trump’s return to office. The narrower premium weakens the incentive to keep shipping to the US, and some future shipments could be redirected instead to Asia. But changing course en route can be complicated and expensive.
“I wouldn’t call the arbitrage dead just yet,” said Marcos Carias, North America economist at global trade-credit insurer Coface.
Warehousing companies are seeking approval for additional capacity from Comex as US storage requirements balloon. Since the start of 2025, the exchange said it has added 20 warehouses and nearly 725,000 short tons of copper capacity. That’s equivalent to about 39% of annual US refined-copper consumption. Sites were added in Mobile, Chicago and Atlanta this year.
Shipper BBC Chartering also added Mobile — on the Alabama coast — as another stop for South American copper, according to a person with knowledge of the matter.
“The potential for tariffs alone has essentially had the effect they want from tariffs; that is, bringing lots of supply into the country and increasing domestic premiums to support domestic projects,” said Ryan McKay, senior commodity strategist at TD Securities. The White House will likely continue to delay a decision to keep this the case, he said.
(By Yvonne Yue Li, James Attwood and Julian Luk)
Attacks on mining operations on the rise in Pakistan: report
More than 30 mining operations have been attacked in Pakistan’s resource-rich Balochistan province in 2026, raising security risks as the country seeks investment to develop some of the world’s largest undeveloped copper-gold deposits.
Balochistan recorded 38 attacks connected with extractive operations between January and September, bringing the total over the past three years to more than 130, according to data from the Armed Conflict Location & Event Data (ACLED) report.
“This risks undermining Pakistan’s drive to attract international investment and develop its mineral sector amid the global scramble for critical minerals,” ACLED South Asia assistant research manager Pooja George said in a news release.
Balochistan is a region swarmed by conflict between separatists and the government especially around extraction of copper, gold, chromite, coal and natural gas. For separatists, extraction equals exploitation of the country’s wealth, causing them to target operations for what they signify.
The attacks make it more difficult for Pakistan to leverage its untapped mineral and fossil fuel wealth, as well as find safety solutions for all parties involved in the conflicts.
Transport targeted
Balochistan has reported over 130 attacks in the last three years directly connected with extractive operations, with 38 being just between January and September 2026.
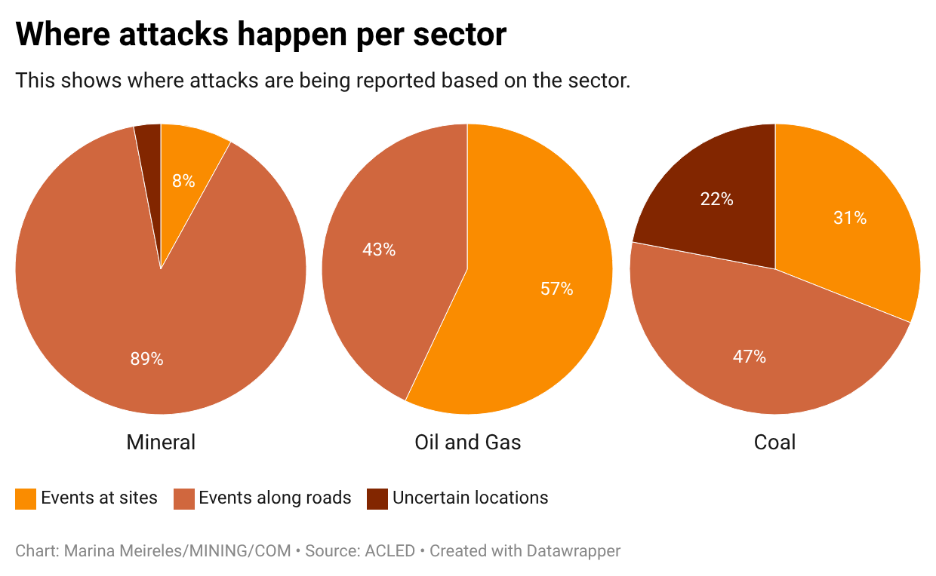
Attacks on mineral projects occur predominantly during transportation, where militants can bypass the heavier security surrounding mine sites, according to ACLED.
Flagship projects such as the Reko Diq copper mine and Saindak copper-gold mine involve foreign partners and receive protection from private and state security forces.
Publicly-owned oil and gas operations face a different pattern. More than half of the attacks against those operations take place on extraction sites, a result of less security when compared to mineral projects. Coal operations have experienced most of its attacks during transportation and about a third on site.
Nature of conflicts
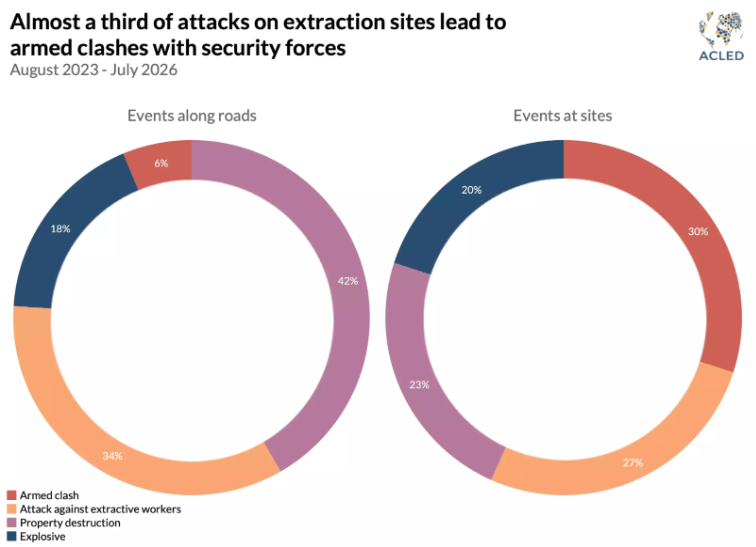
With less than 17% of attacks involving roadside bombs or landmines, ACLED suggests that the purpose of attacks is to disrupt operations by creating an insatiable atmosphere, rather than harming workers and civilians.
Nearly 90% of separatist attacks against mineral projects happen on roads. Gunmen typically fire at vehicle tires to disable trucks and sometimes set the vehicles ablaze after allowing drivers to leave, according to ACLED.
“Most attacks impacting mining involve property destruction rather than fatalities. The aim appears to be disruption: creating and amplifying a sense of instability around mining operations and making the environment increasingly difficult for companies to operate in,” George said.
Militants have also increased roadblocks and checkpoints in the region to facilitate attacks, aiming to show how the state’s authority has decreased and that fear is spreading especially along remote areas. ACLED data show that the number of such events in 2026 is on track to surpass 2025 levels.
Attacks on extractions sites can carry greater human costs because militants are more likely to encounter security forces, increasing the potential for lethal clashes.
Operations workers and companies have felt this increase in instability, with privately-owned mining operations warning about shutdowns or slower operations and workers going on strike.
Impact on Pakistan’s mining future
The stakes are rising as Pakistan courts international investment to develop Balochistan’s largely untapped mineral wealth.
Lack of well-developed and secured transportation infrastructure and the need for state security bring more risks to foreign investors, as separatists are more likely to attack their operations as the government is their biggest adversary.
ACLED also adds that another risk that comes with increased security, is the abuse of those forces, that can carry reputational costs for companies and impact local community engagement, which is key to safe operations.
Continued attacks could also draw more international attention to the separatist insurgence, giving militants a larger platform while potentially exposing them to a stronger state crackdown.
Pakistan has deployed additional security forces to Balochistan, but ACLED argues security measures alone are unlikely to resolve a conflict rooted partly in political disputes over resources, autonomy and the distribution of economic benefits.
“Opposition to resource extraction lies at the heart of the Baloch separatist insurgency, meaning attacks may escalate further as Pakistan seeks to leverage its untapped mineral wealth,” George said.
US battery startup that chose China over Kentucky opens first factory as Trump, Xi meet
A US battery startup that scrapped plans to make Kentucky the site of its first factory has instead built it in China, exposing the limits of President Donald Trump’s efforts to lure manufacturing home just as he welcomes Chinese President Xi Jinping for a summit.
EnerVenue starts mass production at its manufacturing facility in the eastern Chinese city of Changzhou on Thursday, the same day Trump meets Xi in Washington, as relations between the superpowers remain strained by a tariff war the US president launched partly to bring back manufacturing and jobs.
Chief Executive Henning Rath told Reuters the date was a coincidence, and the decision to manufacture in China instead of the US was down to skills and supply chain depth — particularly in Changzhou, which bills itself as China’s “new energy capital.”
“The secret sauce is this industrial cluster,” Rath said, citing the density of hydraulics, pneumatics and automation specialists, along with engineers able to iterate quickly on what he called a “first-of-its-kind” line.
Without building in China, Rath said, it would be “very difficult with the capital available” to prove the manufacturing process at a commercial scale.
EnerVenue’s choice exposes how Trump’s offer of lower taxes, easier permitting and other incentives may not be enough to overcome the advantages offered by places like China, even in a sector viewed as critical to US energy security and supply-chain resilience.
When Rath joined the company in April, he made building in China a precondition for taking the job.
Lower costs, deeper expertise
A floor manager at the Changzhou plant said local suppliers often develop equipment without payment until a design is adopted, unlike foreign vendors that tend to ask for money upfront.
Graduate engineers earn about 12,000 yuan ($1,792) a month, well below US salaries, he added.
EnerVenue, which has R&D in Fremont, California, and was founded by Stanford materials science professor Yi Cui, makes nickel-hydrogen batteries derived from technology NASA used in the Hubble Space Telescope and International Space Station.
It announced a Kentucky factory plan in 2023 with a first phase costing $264 million and creating 450 jobs, but abandoned it a year later.
Rath, speaking as engineers tested spinning hydraulic arms and lidar-guided robots ferried materials between production stations, said the attempted project was a “valuable learning experience,” but the technology wasn’t yet ready.
EnerVenue went on to redesign both the battery and the factory.
Expansion plans
Rath declined to disclose the cost of the Changzhou facility, which is around 95% automated and will employ about 400 workers by the end of the year, but gave a $20 million to $50 million range. Government support was limited to permitting, certification and site selection, he said.
EnerVenue raised more than $300 million in a March funding round led by Full Vision Capital, the family office of Hong Kong property heir Peter Lee Ka-kit, whose broader group includes customer Towngas, Rath said, with other investors including Saudi Aramco and SLB.
The company aims to reach annual capacity of 250 megawatt hours this year, equal to about 300 battery cells a day, rising to 1 gigawatt hours by the third quarter of 2027.
It’s unclear whether China-made cells will qualify for US clean energy tax credits, which Trump’s 2025 tax law kept for battery storage while adding restrictions on Chinese content and ownership.
“We are an American company with a Chinese footprint,” Rath said.
EnerVenue plans to open similar factories in North America, the Middle East and Europe from 2028, with sites to be chosen next year, said Rath.
But he stressed that China is the “factory of factories” and “an important stepping stone” towards global production.
Asked whether EnerVenue would open a US plant, Rath said, “We want to play in the North American market. It depends a little bit now on legislation and regulation.”
($1 = 6.6955 Chinese yuan)
(Editing by Marius Zaharia and Kevin Buckland)
Niche metals test West’s resilience to Chinese export curbs
Three years on from China curbing exports of two niche metals vital to the chipmaking, clean energy and defence sectors, the West is still feeling the price pain and waiting for its own production to come to the rescue.
The export curbs on gallium and germanium have forced Western companies to stockpile, seek alternative supplies, and explore new designs and substitutes. But the decisive response is only now taking shape, with several Western production projects announced in recent months aimed at finally breaking China’s stranglehold on the niche but vital market.
With prices now at 9 to 10 times 2023 levels, that new supply cannot come soon enough.
Chart: Reuters.
“These export controls have acted as a real wake-up call… In response, companies are increasingly diversifying their procurement strategies, turning to recycling, alternative suppliers and emerging non-China projects where possible,” said Cristina Belda, senior analyst at Argus.
Manufacturers of infrared optics used in defence and thermal imaging systems have particularly struggled with tight supply, she said.
AI contributing to rising demand
While production projects take shape, the AI boom, expanding fibreoptic networks and growing use of infrared imaging are pushing up demand.
Gallium demand is seen rising by about 12% per year through 2030 from about 1,000 metric tons in 2025, preliminary S&P Global estimates show.
Global germanium demand is set to rise by 3.3% annually over the same period from an estimated 343 tons in 2025, S&P Global said.
Yet consultancy Project Blue estimates China in 2025 still accounted for 98.9% of primary gallium supply and 68.6% of germanium supply, underscoring the scant progress made so far in reducing China’s dominance.
Chart: Reuters.
In introducing its export controls in 2023, later expanded to include rare earths and other critical minerals, Beijing used that dominance as leverage in trade and other disputes.
Metals substitution
Replacing either metal — primarily byproducts of alumina and zinc processing — with other materials brings its own challenges.
“There is no one-to-one substitute for germanium,” said Jessica DeGroote Nelson, senior vice president of precision optics at US-based Edmund Optics, noting using other materials would require redesigns.
“It’s not impossible, but it is very challenging.”
A source at another optics company said it has succeeded in switching to substitutes in some applications, halving germanium use over the past 18 months, using Western suppliers and raising its prices.
“We do have many customers who are willing to purchase at current prices, the issue here is the availability of supply,” the person said.
Industry participants say gallium arsenide is being replaced by indium phosphide in some semiconductor applications while zinc selenide, zinc sulphide, silicon and chalcogenide glass are gaining traction as germanium alternatives in some infrared applications. Still, all those require costly technological adjustments that take time, industry insiders say.
Stockpiling is another response. DeGroote Nelson said some customers buy germanium before designs are even finalised in order to ensure availability when production begins.Recycling is yet another route being taken by US-based Lattice Materials, which uses germanium to produce crystals for displays in fighter jets, tanks and other military equipment.
“We don’t see supply loosening up anytime in the near-term,” company president Travis Wood told Reuters.
“Every data point we’ve seen shows prices to at least stay at current high levels or even continue the upward trend,” Wood said.
Belgium’s Umicore (EBR: UMI) has also been working with STL, a unit of Gécamines that processes mining waste in the Democratic Republic of Congo, to boost germanium recovery.
Playing catch-up
As the race to build new supply gathers momentum, the pressure from ever rising demand means some producers say they are already playing catch-up.
In Greece, METLEN (LON: MTLN), which has begun pilot-scale production and aims to produce 50 tons of gallium annually by 2028, says demand from potential customers now already exceeds that target several times.
In April, Australia and the US pledged over $3.5 billion to support a range of critical minerals projects, including gallium and germanium, nearly doubling an initial amount agreed last year.
Underscoring the need for that support, S&P Global expects ex-China gallium supply capacity to total 20 tons by the end of 2026, leaving a supply gap of about 678 tons. Non-Chinese germanium metal production is seen at 31 tons, or 177 tons short of demand.
Jack Bedder, founder and director of consultancy Project Blue, told Reuters that the emergence of credible projects with government support offers a chance for greater diversification, but the economies of scale still favour China with its enormous capacity and production costs new Western projects will struggle to match.”We think a material reduction in dependence is achievable over five years, but eliminating dependence on China is much less realistic.”
Government support such as price floors will probably be needed to bring new supply and ensure its long-term commercial viability, said Piyush Goel, consultant at London-based consultancy CRU.
By 2030, S&P Global estimates eight announced projects, including Wagerup in Australia and Clarksville in the United States, could boost ex-China gallium supply to about 386 tons from roughly 5 tons currently.
Yet even that will leave ex-China demand looking to China for 65% of its supply, Reuters calculations based on S&P data show.
New germanium projects in Canada, South Korea and the United States are expected to help lift ex-China germanium refining capacity to 126 tons by 2030. But even with five ex-China refineries potentially operating, capacity would cover only about 48% of projected ex-China demand, according to S&P.
Early stages
Several of the announced gallium projects, including those planned by METLEN in Greece, Alcoa (NYSE: AA) and Sojitz in Australia, Rio Tinto (ASX: RIO) and Indium Corporation in Canada, and Nalco (NSE: NATIONALUM) in India, are still being developed and have yet to reach full commercial production.
New entrants complement those efforts — Korea Zinc is developing gallium and germanium capacity at home and at a planned Tennessee refinery, and US-based ReElement Technologies is developing a refining complex in Indiana.
Titan Mining, a zinc and graphite producer, expects to start germanium production in New York state by year-end at 2.5 to 3 tons, or about 7% to 10% of US demand.
At the same time, a handful of established non-Chinese germanium suppliers are working to boost their output.
Canada’s Teck Resources (TSX: TECK.B) struck a deal with Ottawa in July to support an expansion of production at its facility in Trail, British Columbia.
(Reporting by Ashitha Shivaprasad; additional reporting by Eric Onstad, Ernest Scheyder, Solomon Cefai and Divya Rajagopal; editing by Pratima Desai, Tomasz Janowski and Jason Neely)
China rare earth exports to US drop before Xi-Trump meet
US President Donald J. Trump meeting with Chinese President Xi Jinping in China on May 14, 2026. Credit: The White House | X
China’s exports of rare-earth magnets to the US fell last month, underscoring concerns in the Trump administration that Beijing is still squeezing flows of the critical minerals despite last year’s trade truce.
Shipments of magnets to the US dropped 21% in August to 512 tons from the month before, according to Chinese customs data released on Sunday. The industrial components — along with other types of rare-earth products — became Beijing’s greatest point of leverage over Washington in trade negotiations last year.
President Donald Trump and Chinese leader Xi Jinping are due to meet in the US capital on Thursday to flesh out their approach to topics ranging from trade to artificial intelligence. Ahead of that, top US negotiators signaled rare earth flows were a sticking point and may mean that the truce — which expires November — may be extended only by three to six months.
“I think a lot of it is because China has created this uncertainty,” US Trade Representative Jamieson Greer said in a Monday interview with Bloomberg Television after talks in New York with his Chinese counterparts. “They have limited rare earths exports. They control them, we monitor them, and I think just saying we have full confidence and trust with each other at this point is a little naive.”
China imposed controls on exports of rare-earth magnets — used in everything from cars to consumer goods and weaponry — in April 2025, although they were subsequently eased. The industry is keenly waiting for the outcome of the Xi-Trump talks as they come before the expiration of a US-China trade truce, which includes commitments by Beijing to maintain flows of critical minerals by issuing more generous export licenses.
China hopes to offer more licenses for rare earth exports as a bargaining chip in talks, people with familiar with the matter said, without disclosing what Beijing would demand in return.
“Washington needs stability with Beijing to keep these critical inputs moving,” Chris Kennedy, lead for economic statecraft at Bloomberg Economics, said in a note. “Yet periods of calm that restore access to lower-cost Chinese material weaken the urgency for the US to break its dependence on China.”
Shipments slumped in May last year, but quickly recovered. They’re running at an average of about 504 tons a month this year, although that’s still below 621 tons in 2024 before the curbs. Chinese customs data shows that direct exports of rare earths including yttrium, dysprosium and terbium — subject to export controls — have also dropped compared with previous years.
In May, Greer gave Beijing a “passing grade” for its performance in keeping flows of critical minerals going. US Treasury Secretary Scott Bessent said in July that China should “fully meet its commitments.” Bessent and China’s Vice Premier He Lifeng are holding talks in New York ahead of the leaders’ meeting.
World’s top rare earth magnet maker gives Xi leverage over US
Baotou City: Epicentre of China’s rare earth industry. Image by Matthew Stinson Creative Commons CC BY-NC 2.0
Baotou, an industrial city near the Gobi Desert, is the Silicon Valley of rare earths. Off Rare Earth Street, research institutes sit alongside a museum devoted to the minerals. Nearby, JL Mag Rare Earth Co., the world’s top maker of high-performance magnets, is building its largest plant yet — an expansion that offers a glimpse of how China plans to defend its commanding position in the supply chain.
Over the past year, the US and its allies have pledged billions of dollars to develop new sources of rare earths outside China. Indispensable to everything from missiles to electric vehicles, the minerals are a potent source of Beijing’s economic leverage. As President Xi Jinping arrives in Washington this week, rare earths are at the top of the trade agenda, with China weighing whether to expand export curbs this fall.
But as the US and others attempt to replicate China’s supply chain, Beijing is trying to redefine it. The country already dominates magnet production, and companies like JL Mag are now expanding into increasingly sophisticated components that incorporate them.
That creates a moving target. Mining rare earths is only the first step. The minerals must be separated and refined, turned into high-performance magnets and then manufactured into usable parts. Even if countries outside China secure enough dysprosium or terbium from new mines in places like Brazil, for example, they could still depend on Chinese companies — and their technology, patents and manufacturing scale — to supply fast-growing industries like robotics.
China’s rare earth magnet exports to the US fell last month, and Beijing hopes to offer additional export licenses as a bargaining chip at the summit, Bloomberg News reported.
JL Mag is Exhibit A. Just a few years ago, the company was best known for making rare earth magnets for air conditioners and wind turbines. Today, it has more than 10 times the current production capacity of its closest US competitor and has emerged as a major supplier to the EV industry, with analysts linking it to customers including Tesla Inc. and Volkswagen.
A review of JL Mag’s corporate filings and interviews with magnet makers in Asia and North America, as well as those familiar with the company’s operations, found that the scale and scope of its expansion far eclipse the nascent projects underway in the West. Little known outside the industry, the company is extending its reach from Baotou to as far away as Monterrey, Mexico, where it wants to shift some processing closer to US clients.
“JL Mag can meet the needs of its customers in a way that US competitors just can’t,” said David Abraham, principal at Materium Strata, a critical minerals advisory and market intelligence firm. “Customers can just give them their specs, and JL Mag basically presses a few buttons on their machines and out comes the product. Catching up to that is incredibly hard.”
Estimates put JL Mag’s share of the global rare earth magnet market at 10% to 20%, with its products used across the world’s top 10 new-energy vehicle brands. By 2028, it plans to add as much as 20,000 tons of annual capacity in Baotou, a 50% increase that would extend its lead in an industry where its three closest rivals are also Chinese.
The expansion is already visible. JL Mag’s Baotou site sits on the block next to Rare Earth Park, where Chinese scientists are carved into a granite wall and stainless-steel cubes embossed with chemical symbols dot the flower beds. At the factory, a recruitment flyer hangs on the front gate. The plant takes more than half an hour to walk around.
Robotics shows where JL Mag wants to go next. Last year, the company launched a business unit dedicated to humanoid robots that reports directly to its chief executive, with plans to expand its presence in the sector. Daiwa Securities has identified the firm as the sole supplier of motor rotors for Tesla’s Optimus robots. Another analyst estimates that JL Mag supplies about 80% of the magnets used in Tesla vehicles.
“They came out of nowhere,” said Constantine Karayannopoulos, the former chief executive officer of Neo Performance Materials Inc., which also operates a magnet plant in China. “To me, there is JL and then there is everybody else. They are a juggernaut. They can take business at any price.”
JL Mag referred questions about its operations and expansion plans to its exchange filings.
The company has long been on Beijing’s radar. In May 2019, Xi stopped at some of JL Mag’s facilities in southern China, touring production lines and inspecting the furnaces used to make rare earth magnets. The visit was celebrated in state media and JL Mag’s publications. To remain “undefeated in fierce competition,” Xi said, according to state media, “we must firmly grasp technological innovation as a strategic foundation.” China’s top trade negotiator, Liu He, stood at his side.
The timing and choice of venue were provocative then and prescient in hindsight. Just 10 days earlier, US President Donald Trump had hiked tariffs on Chinese goods, escalating a trade war that would punctuate his first term in office.
It would take until last year — just after Trump’s “Liberation Day” tariffs — for Xi to pull the trigger. China imposed export controls on rare earths, choking off supplies and threatening swaths of US manufacturing before helping force a trade truce with Washington.
Yet JL Mag has been largely unfazed. US efforts to diversify rare earth flows still face “numerous challenges,” the company said in its latest annual report. Chinese magnet makers will remain the “dominant players.”
In 2024, China accounted for about 94% of global rare earth permanent magnet manufacturing — far exceeding its share of mining — according to the International Energy Agency. That same year, JL Mag says it became the world’s largest magnet producer by both output and sales. Between Xi’s visit in 2019 and 2025, the company’s annual capacity more than quadrupled, according to its historical reports. By next year, it wants to boost that by another 50%, to 60,000 tons.
That advantage is reinforced by clusters like Baotou, where processors, magnet makers and research institutes sit just a few hours by train from the giant Bayan Obo mine. The proximity cuts logistics costs and makes it easier to share suppliers, recruit specialized workers and tap decades of expertise.
By comparison, MP Materials Corp., which operates the only rare earth mine and processing facility in the US, started producing rare earths magnets from its plant in Fort Worth, Texas, last year. After the Trump administration invested $400 million in the company, for a roughly 15% equity stake, MP unveiled plans to spend more than $1.25 billion on a much bigger magnet-making plant in Northlake, Texas, that would eventually bring its production to about 10,000 tons a year.
That expansion would equal about a third of JL Mag’s production in 2025, without factoring in the Chinese firm’s plans to expand.
Other US companies have made similar pledges to build magnet facilities but have little experience and capital to show for it.
Demand, meanwhile, is surging, benefiting JL Mag and Chinese rivals such as Ningbo Yunsheng Co. Ltd. Consumption of rare earths used in permanent magnets has doubled since 2015 and is projected to rise another third by 2030, according to the IEA. Outside China, demand is expected to climb 50% by 2035, with existing and planned magnet projects meeting less than a fifth of it.
“The Western companies are still developing their technology, doing everything from scratch,” said Derek Zhang, a Daiwa Securities analyst. “The Chinese companies can ramp up capacity very easily and the cost is maybe about 1/10th.”
JL Mag was founded by industry outsiders. Two decades ago, Cai Baogui was hunting for his next business opportunity. He grew up in Jiangxi province, the southern heartland of China’s rare earths sector, but had spent his career elsewhere — first as a university lecturer and later as a senior executive overseeing plastics manufacturing operations in Dongguan.
Renewable energy caught his attention after he met the chairman of emerging wind-turbine maker Goldwind, according to a rare interview Cai gave to a Chinese news outlet in 2020. Soon after, he teamed up with two friends, Hu Zhibin and Li Xinnong, to explore making rare earth magnets needed for such machines.
In 2008, the trio launched JL Mag by uniting opposite ends of the supply chain. Ganzhou Rare Earth provided a link to raw materials, while Goldwind became an important early customer. The idea was to move beyond the mining, separation and smelting that dominated the city of Ganzhou’s rare earth industry and capture more value by turning those resources into the magnets that make technologies actually work. JL Mag’s founding philosophy, Cai said, was “long-termism.”
Success was hardly assured. Rare earth prices surged more than tenfold in a matter of months in 2011 before collapsing, according to Cai, who remains the firm’s chief executive officer. If raw materials became too expensive, he said, it would be like having “flour more expensive than bread.”
By 2013 and 2014, Cai recalled, employees were leaving and he faced a choice over whether to abandon the industry.
But by the time Xi visited in 2019 — a moment Cai said “greatly boosted our confidence” — JL Mag had emerged from the downturn with a growing business supplying magnets for wind turbines, ACs and EVs. It had also gone public in Shenzhen the previous year.
Four years later, JL Mag raised about HK$4.2 billion ($540 million) in Hong Kong, giving it access to more capital as it embarked on a massive expansion.
In the years since, government support has accompanied JL Mag’s rapid expansion. The company received tens of millions of dollars in subsidies recognized over the past three years, while local authorities have repeatedly designated its factories as major projects.
Some describe JL Mag as unusually well-positioned to weather even the stormiest stretches in relations with Washington. When Beijing’s rare earth controls disrupted manufacturers abroad last year, JL Mag was among the first Chinese companies granted a general export license. Its US sales revenue rose 40%.
The firm has for years been one of the government’s “favorite sons,” said John Ebert, the longtime US representative for magnet producer Ningbo Yunsheng, which he left this year. “That’s why JL Mag grew so quickly from almost nothing into something.”
For potentially huge new markets like robotics, the company is going all-in.
JL Mag named humanoid robots as its next major growth pillar in its latest annual report. Their joints rely on magnet-powered motors that effectively act as muscles, allowing for precise, agile movement. JL Mag is pushing beyond simply supplying these magnets to making finished components, adding another layer of the supply chain for Western competitors to replicate.
“Moving forward the company will continue to increase its investment in research and development of magnetic components for humanoid robots,” JL Mag said.
China is already an early leader in humanoid robotics, accounting for 97% of global shipments in the first half of 2026, according to one survey.
The potential is substantial. Nomura says humanoids use significantly more rare earth material per motor than EVs. JL Mag expects China to remain dominant, telling Citigroup analysts it will likely still produce 80% of the world’s magnets in 2030.
“Even if Western projects materialize, management believes they may solve the ‘availability’ issue, but are unlikely to compete with China on costs, scale, quality and customization,” Citigroup said in a February report, summarizing JL Mag’s views.
That helps explain another US strategy for reducing China’s leverage: eliminating rare earths from magnets altogether.
Niron Magnetics, a Minnesota-based manufacturer, is pursuing that approach with magnets made from iron and nitrogen. The Pentagon is backing the company as it develops factories capable of eventually producing as much as 11,500 tons annually. Looming restrictions are also helping create a market for alternatives: Starting Jan. 1, the Pentagon will stop procuring certain defense technology containing Chinese rare earth magnets.
But the economics remain daunting. Niron has seen a “massive” influx of inquiries from prospective defense customers ahead of the deadline, said Tom Grainger, its vice president of commercial and corporate development. Demand has already overwhelmed the relatively small company — before it has even begun targeting robotics.
“If you take major economic buckets like labor, or government support, you just can’t compete with China,” Grainger said.
How Austria can loosen China’s grip over a key critical mineral
Erzberg mine in Austria. Stock image by dudlajzov.
Nestled between a turquoise-colored lake and the soaring peaks of the Austrian Alps, Plansee Group is building one of the West’s most formidable critical minerals operations outside China.
The closely held company, based in the town of Reutte, sells tungsten, a metal that attracts far less attention than rare earths but is no less vital to modern industry. The material’s exceptional hardness makes it ideal for tools that cut and shape car parts. Its resistance to heat is crucial to semiconductor manufacturing. And its extraordinary density, nearly twice that of lead, gives armor-piercing ammunition much of its penetrating power.
Few metals can match that versatility, but sourcing it comes with a familiar vulnerability: Beijing dominates the supply chain. A series of moves by China over the past two years — restricting exports, drawing in more raw material and, most recently, cutting off key shipments to Japan — has intensified a global scramble for tungsten. In turn, its cost has soared.
That marks a stark turnaround after years of low prices forced many Western tungsten suppliers out of business. A similar shift is playing out across several critical minerals markets, as Chinese export controls and surging prices put a spotlight on the handful of alternative producers capable of quickly boosting supply.
Plansee is one of them. The company has built up its position in tungsten over decades, securing ore from a mine in South Korea and expanding US processing alongside its European operations. Today, it’s by far the largest manufacturer outside China, accounting for about 12% of global demand and supplying some of the world’s most valuable companies, including ASML Holding NV and SpaceX.
Increasingly, the company’s advantage is that much of its tungsten requires no new mining at all. More than 90% of the 15,000 metric tons it can produce each year comes from worn drill bits, milling inserts and other scrap, thanks to two decades spent developing ways to recycle used material into tungsten comparable in quality to that made from ore.
“Our starting point was China independence,” Chairman Karlheinz Wex said from the company’s headquarters, located a two-hour drive south of Munich. “The basis for becoming independent was recycling.”
That strategy gives Plansee greater control over its materials — and more leverage as competition for supply intensifies. China still accounts for more than 80% of mined tungsten, while its own supplies are tightening as mines age and domestic demand grows. After the country became a net importer last year, Chinese buyers began aggressively snapping up US scrap, in some cases outbidding domestic traders, according to Wex.
China also curbed exports of intermediate tungsten products. Wex estimates that about 20,000 tons of material that flowed annually to Western markets a decade ago has since disappeared.
Amid supply concerns, the Trump administration effectively halted US tungsten scrap exports in August, requiring sellers to offer all of it to domestic buyers.
Tungsten is a niche market on paper, valued at only around $16 billion globally — about 5% of copper’s. But its reach is far greater. Carbide tools made with the metal are used throughout modern manufacturing, from aircraft and automobiles to computers and phones.
“The world would stand still without these carbide tools,” said Simon Jost, managing director of Plansee’s Ceratizit unit in Reutte.
Inside the highly-automated factory, robots navigate between hundreds of workers. They’re ferrying tungsten plates and rods to be stamped, pressed and polished. Some are as thin as a human hair and used by hospitals to perform surgeries. Others look like menacing claws and can bore tunnels through mountains. Nearly every manufactured product requires something to be drilled, cut or shaped along the way, Jost said.
Tungsten is hardly an isolated case of China’s dominance in critical minerals. The country is the leading refiner of the vast majority of strategic metals, according to the International Energy Agency. The IEA estimates that China’s rare earth export curbs alone could put $6.5 trillion in annual downstream production at risk. Ursula von der Leyen, President of the European Commission, warned this week about “dangerous dependencies” on Beijing for critical minerals.
Austria central bank Governor Martin Kocher said policymakers are paying closer attention to how shortages of critical materials can constrain production and fuel inflation. Central bankers have long factored oil and gas into their models. Now they’re looking at less visible inputs such as tungsten, where a shortage of a relatively cheap material can hold up production worth many times more.
Plansee has treated the squeeze as an opportunity to gain market share and advertise its services. The company’s global network makes it one of the few able to turn scrap and ore into usable tungsten without relying on China. Material collected in Europe can be processed in Austria, Finland or Pennsylvania before moving to factories and customers.
Recycling leaves Plansee less exposed to volatile mining markets and swings in Chinese exports. The company is a rarity in Europe.
“We are not particularly good at recycling in Europe right now,” said Román Arjona, chief economist at the European Commission’s internal-market and industry directorate. Too much critical material is still lost because Europe lacks the investment, skills and infrastructure to recover it, he said.
Recycling also cuts Plansee’s environmental footprint. Products made from recycled tungsten generate four to five times fewer carbon emissions than those made from newly mined material, Wex said. Renewable sources provide 98% of Plansee’s electricity, helping the group cut its carbon footprint by almost a third over the past five years.
Revenue rose 4% to €2.35 billion in fiscal 2026, and Plansee has invested €145 million in new capacity to process concentrate, make powder and produce higher-value tungsten products.
Plansee’s location explains some of its success. Jewish chemist and entrepreneur Paul Schwarzkopf founded the company in the Alpine town of Reutte in 1921, lured from Berlin by cheap hydropower from nearby Lake Plansee.
Schwarzkopf fled to the US as Nazi persecution intensified, and his factory was expropriated and converted into an armaments plant. He returned after World War II and eventually recovered ownership following a prolonged restitution struggle. A century later, the same access to low-carbon power remains a competitive strength.
Plansee’s ability to produce tungsten outside China is becoming more valuable for the US, in particular. This year, the company formed a joint venture with Manhattan Five Partners — a US property developer that works with the federal government — to build a strategic reserve of tungsten oxide. Plansee plans to expand its Pennsylvania plant to process about 12,000 tons annually, using recycled scrap and ore from approved sources.
The push is becoming more urgent ahead of January 2027, when new Pentagon restrictions will further limit the use of tungsten originating in China, Russia, Iran or North Korea. Defense suppliers will increasingly need to trace the metal back to where it was mined or recycled and processed — playing to Plansee’s decades of investment in tracking material across borders.
Plansee is also locking in new supplies. It recently extended a deal to buy tungsten concentrate for another 21 years from Almonty Industries Inc.’s Sangdong mine in South Korea. Plansee owns about 10% of Almonty, its largest shareholder, which is also restarting the long-shuttered Los Santos mine in Spain.
Sangdong is instructive of how tough it is to compete with China. The mine closed about three decades ago after cheap Chinese tungsten drove down prices. Now being revived, it could eventually supply as much as 20% of the tungsten concentrate produced outside China, according to Plansee.
This time, the deal includes protections designed to keep Sangdong viable if prices fall again.
“You must think long term,” Wex said.
The European Union is trying to build resilience more broadly. Its Critical Raw Materials Act calls for the bloc by 2030 to extract 10%, process 40% and recycle 25% of the strategic materials it consumes, while reducing dependence on any single foreign country.
Tungsten illustrates the challenge. Europe has mines, processors such as Plansee and a vast stock of the metal already embedded in tools and machinery. Almonty has been working to start up a major potential project in Spain since 2013, but the future of the operation has been thrown into doubt after a regional government issued a non-binding negative environmental assessment against it in July.
Ultimately, recycling more tungsten is key to reducing reliance on China — but only if the scrap remains in Europe long enough to be recovered.
“We need to make sure that all the used tools stay in the Western world,” Jost said.
Boddington moine led Australian gold output. Credit: Newmont
Australian gold output held around the same level it has averaged over the past decade in the year ended June, even as seismic disruptions at Newmont (NYSE, ASX: NEM; TSX: NGT)’s Cadia mine weighed on the latest quarter.
Production totalled 303 tonnes, or about 9.7 million oz., up four tonnes from the previous financial year and worth about A$60 billion ($42 billion) at current prices, Melbourne-based mining consultant Surbiton Associates said Sunday. Output in the quarter ended June 30 rose by nearly two tonnes from the previous three-month period to 76 tonnes.
“Most operations produced more gold in the June quarter than in the previous quarter, with several smaller producers also starting up,” Surbiton director Sandra Close said. “Toll treating, or the alternative of selling ore, are both popular with the smaller end of the list of producers.”
The steady national tally comes ahead of a larger expansion cycle highlighted by Surbiton last month. Northern Star Resources’ (ASX: NST) is working to expand the Super Pit processing plant to 27 million tonnes annually from 13 million tonnes, with commissioning already underway.
Boddington leads
Newmont’s Boddington mine was Australia’s largest gold producer in the financial year at 563,000 oz., followed by the Super Pit at 480,429 oz. and the AngloGold Ashanti (NYSE: AU)-Regis Resources (ASX: RRL) Tropicana mine at 478,095 ounces.
Newmont’s Tanami operation produced 395,000 oz., while Gold Fields’ (NYSE, JSE: GFI) St Ives mine produced 354,900 ounces.
Boddington also posted the largest quarter-over-quarter increase among major operations, adding 49,000 oz. from the March quarter. Tropicana gained 23,000 oz. and Northern Star’s Thunderbox-Bronzewing operation added 15,500 ounces.
Cadia moved in the opposite direction, with production falling by 60,000 oz. after seismic activity disrupted operations. National output would have been almost two tonnes higher if Cadia had matched its March-quarter production, Surbiton estimates.
Copper boost
High copper prices are also reshaping the economics of some Australian gold operations.
Evolution Mining’s (ASX: EVN) 80%-owned Northparkes mine in New South Wales treated ore grading 0.17 gram gold per tonne and 0.57% copper in the June quarter. Copper credits pushed its gold all-in sustaining cost to minus A$10,696 per ounce, according to Surbiton.
The result underlines the growing benefit of copper credits for Australian mines producing both metals as copper prices trade at historically high levels. Copper has gained about 46% in the past year to $6.72 per lb. as of Monday morning, according to data compiled by Trading Economics.
Larvotto begins gold, antimony production at Hillgrove
Larvotto Resources (ASX: LRV) has produced its first gold and antimony concentrate at the Hillgrove mine in New South Wales, advancing a project expected to become Australia’s largest antimony producer as global supplies tighten.
Hillgrove is expected to produce about 4,900 tonnes of antimony and 40,500 oz. of gold annually over an initial eight-year mine life. Larvotto has secured binding offtake agreements with Wogen Resources for antimony and Glencore (LON: GLEN) for gold concentrate.
“With the successful production of first concentrate, we now move into the delivery phase of the offtake agreements we have secured, namely the antimony offtake with Wogen Resources and the gold concentrate offtake with Glencore,” managing director Ron Heeks said in a news release.
The mine is expected to supply about 7% of global antimony requirements, giving Hillgrove strategic importance as Western governments seek new sources of the critical mineral amid constrained global supply.
Ramp-up begins
First concentrate from the processing plant followed the commissioning of Hillgrove’s flotation circuit and concentrate filter presses, part of an extensive redevelopment and plant upgrade program at the operation.
“These partnerships are significantly important, providing Larvotto with established access to global commodity markets and supply chains,” Heeks said.
Larvotto is now focused on ramping Hillgrove up to its nameplate capacity while pursuing plans to extend the operation well beyond its initial mine life.
“Our focus remains on ramping up Hillgrove to nameplate capacity and growing the project into a multi-decade critical minerals operation,” Heeks said.
The start of production comes as antimony has gained greater strategic importance because of its role in industrial and defence applications and concerns about the concentration of global supply. Hillgrove gives Larvotto exposure to both the critical-minerals market and gold while providing a new Australian source of antimony.