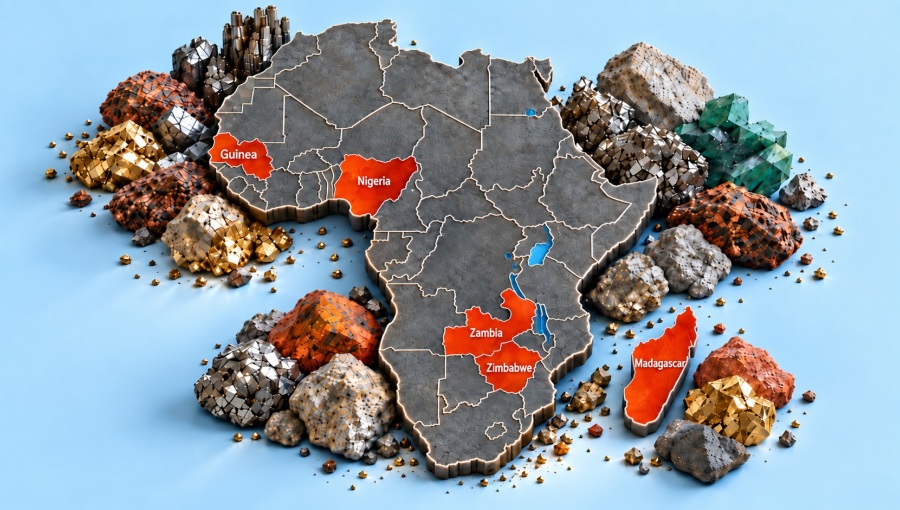
Chinese companies already operating or building processing plants in Zimbabwe, Guinea and Nigeria are best placed to benefit from a new United Nations programme to help five African states keep more of their mineral wealth at home.
On September 23, the UN chose Guinea, Madagascar, Nigeria, Zambia and Zimbabwe, along with Indonesia, for its Country Support Mechanism on Critical Energy Transition Minerals. The programme names no companies and carries no announced funding. So any corporate gain depends on whether its policy and regulatory advice makes local processing easier to finance and operate.
Chinese groups start with a clear advantage because they can often combine mine finance, construction, processing technology and long-term offtake in a single investment package. A programme that offers advice rather than capital does not by itself change that.
The picture is less clear for the African states themselves, and for the domestic and non-Chinese companies operating there.
What the UN is offering
The UN mechanism is intended to help mineral-rich developing countries move beyond raw-material exports into processing, manufacturing and other higher-value activities.
Announced by UN Secretary-General António Guterres, it will provide policy advice, legal and regulatory expertise, environmental and social safeguards, and support for building domestic mineral value chains. The UN Development Programme (UNDP) and the UN Development Coordination Office are leading it.
It grows out of the Panel on Critical Energy Transition Minerals, established in 2024, and a task force launched in December 2025 that coordinates UN work across value addition, traceability, mining legacies, artisanal mining and circularity.
Selwin Hart, Guterres’ special adviser and assistant secretary-general for climate action, warned that without such support, resource-rich countries risk remaining “mere exporters of raw materials, while others benefit enormously from their mineral wealth”.
Why processing is the prize
The strategic concern increasingly lies in processing rather than in where ores are mined. The International Energy Agency said in its 2026 outlook that China is the dominant refiner for most key energy minerals and accounts for more than 90% of global refined supply of gallium, graphite, manganese and magnet rare earths. China’s share of global copper-smelting capacity has also risen from about 15% in 2005 to around 50% in 2025.
Africa captures only a small share of the value generated from the minerals it produces. The IEA estimates that the continent supplies around 75% of the world’s manganese, 70% of its cobalt and nearly 20% of its copper, yet captures less than 1% of the value generated by manufacturing clean-energy technologies and components. Moving downstream requires more than access to ore: processors need reliable electricity, transport infrastructure, finance, technical skills and customers.
What counts as a critical mineral varies by jurisdiction. The EU’s Critical Raw Materials Act identifies 34 critical raw materials, 17 of them classed as strategic for green and digital technologies, defence and aerospace, while the United States’ 2025 list contains 60 critical minerals; both include materials central to the mining sectors of the five African countries in the programme, including aluminium, copper, cobalt, lithium, graphite, nickel, manganese and rare earths.
See IntelliNews: China’s grip on Africa’s critical minerals faces growing pushback from the continent's leaders, while the US and EU compete for access
See IntelliNews: Africa’s push for local mineral processing reshapes mining investment
Zimbabwe: one plant built, others racing the ban
Zimbabwe has taken one of the most interventionist approaches to forcing the shift downstream. It suspended lithium concentrate exports in February, resumed them in April under quotas and a 10% export tax, and plans a full ban from January 1, 2027.
Miners are moving towards deeper local processing, although Benchmark Mineral Intelligence has warned that slow construction of planned lithium sulphate plants could make the timetable difficult to meet.
Zimbabwe exported 1.128mn tonnes of spodumene concentrate to China in 2025, about 15% of China’s lithium concentrate imports, Reuters reported, and Chinese companies dominate the sector.
Zhejiang Huayou Cobalt (SSE: 603799; SIX: HUAYO) is furthest ahead, having built a $400mn plant to turn concentrate into lithium sulphate. Sinomine (SZSE: 002738) and Yahua (SZSE: 002497) have announced similar investments, while Chengxin Lithium Group (SZSE: 002240) and Tsingshan Holding Group are also active, Miningmx reported, citing Reuters.
The Lithium Producers Association of Zimbabwe asked the government for a grace period, citing limited plant readiness. However, Mines Minister Polite Kambamura rejected the request in July, saying the government was “still sticking with January 1”. Companies able to convert concentrate into permitted processed products will therefore be better positioned to continue exporting after the concentrate ban takes effect.
Zimbabwe already offers an early indication of the sums involved. Huayou’s Arcadia operation made the country’s first commercial shipment of lithium sulphate in April, moving beyond spodumene concentrate into an intermediate battery chemical. The Lithium Producers Association of Zimbabwe said in August that industry turnover had averaged about $580mn annually in 2023-2025 after raw-ore exports generated roughly $60mn in 2022, and projected turnover of about $1bn in 2026 following the first lithium-sulphate exports. The figures are industry estimates rather than audited sector data, and they also reflect changes in volumes and prices.
See IntelliNews: Zimbabwe eyes $1bn turnover from lithium sulphate exports amid beneficiation drive
Guinea: three Chinese refinery projects
Guinea faces the same value-capture problem at a different stage of the chain. The country was the world’s largest bauxite producer in 2024, accounting for an estimated 33.2% of global output, according to the US Geological Survey. Still, far less value is retained locally through alumina refining. Chinese state-controlled aluminium producer Aluminum Corporation of China Limited, or Chalco (SSE: 601600; HKEX: 2600), began building a roughly $1bn alumina refinery at Boffa on June 13, with a planned capacity of 1.2mn tonnes a year.
Chalco’s plant is one of three new Chinese-backed refinery projects of similar scale. State Power Investment Corporation and Winning Consortium Alumina Guinea, both Chinese, have each announced refineries of 1.2mn tonnes a year, with each of the three investments put at about $1bn, Ecofin Agency reported.
Compagnie des Bauxites de Guinée (CBG), in which the state holds 49% alongside partners including Alcoa (NYSE: AA; ASX: AAI) and Rio Tinto (ASX: RIO; LSE: RIO; NYSE: RIO), aims to start building its own refinery by the end of 2026. Guinea’s mines ministry said on September 21 that it had discussed possible involvement in that project with the US International Development Finance Corporation and the US Export-Import Bank. The country’s only operating refinery, Friguia, is run by Russia’s Rusal (HKEX: 486; MOEX: RUAL).
Nigeria: Chinese capital, US framework
Nigeria is also trying to push more mineral processing onshore. On July 2 it commissioned the $250mn Diamond New Energy lithium mining and processing plant in Nasarawa State, with capacity to process 6,000 tonnes of lithium ore a day. The project was developed by Chinese investors in partnership with the state government, Jiuling Lithium and Canmax Technologies (SZSE: 300390).
Chinese capital dominates the rest of the sector too. An earlier plant in Lafia, also in Nasarawa State, is operated by Avatar New Energy Materials and has a capacity of 4,000 tonnes a day. Reuters reported in 2025 that Chinese firms had provided more than 80% of the funding for four new lithium processing plants in Nigeria.
Nigeria has also turned to the United States, signing a critical-minerals framework in New York in September covering exploration, mining, processing, infrastructure and technical capacity, although details of projects and financing have not been made public.
See IntelliNews: Nigeria opens Chinese-built $250mn lithium plant, targets leading role in battery supply chain
Zambia: smelting capacity is the constraint
Zambia shows how limited smelting capacity can undercut a beneficiation policy. The government wants to move further down the copper value chain but suspended a 10% export duty on copper concentrates to help clear stockpiles while major smelters underwent extended maintenance.
The waiver covered 271,742 tonnes of concentrate. The suspension expired on September 30 without a replacement measure being announced, meaning the standard duty reverted, renewing the tension between domestic beneficiation goals and available smelting capacity.
The waiver was shared among six producers. Mopani Copper Mines, owned by Abu Dhabi-based International Resources Holding and state investment vehicle ZCCM Investments Holdings (LuSE: ZCCM-IH; Euronext Paris: MLZAM; LSE: ZCC), held the largest duty-free quota at 100,000 tonnes, followed by the Lumwana mine of Barrick Mining (NYSE: B; TSX: ABX) at 56,986 tonnes. First Quantum Minerals (TSX: FM) and Chinese-owned Nkana Mining and Minerals Processing each held about 43,000 tonnes, while Lubambe Copper Mine, 70% owned by China’s JCHX Mining (SSE: 603979), and Vedanta’s Konkola Copper Mines held 15,000 tonnes and 12,541 tonnes respectively.
The allocations show which producers were eligible for the waiver, not how exposed each is to the duty. Mopani declined to use its quota and intends to process all available concentrate through its own smelter, Bloomberg reported in June. Producers able to process more of their concentrate domestically are generally less exposed to the duty’s return.
See IntelliNews: Zambia extends copper concentrate export-duty waiver, prioritising output over beneficiation amid smelter constraints
Madagascar: processing planned offshore
Madagascar illustrates perhaps the clearest gap between mineral endowment and domestic downstream processing. It has important graphite, nickel and cobalt resources but remains concentrated in upstream activity, and it imposes no major local-processing requirement on graphite producers, Ecofin Agency reported.
The main examples are in graphite and mineral sands. Canada’s NextSource Materials (TSX: NEXT; OTCQB: NSRCF), which operates the Molo graphite mine, has approved a battery-anode plant in Abu Dhabi. Energy Fuels (NYSE American: UUUU; TSX: EFR) is developing the Vara Mada mineral sands and rare-earths project, formerly known as Toliara, and plans to ship its monazite to its White Mesa mill in Utah for processing.
The Ambatovy nickel and cobalt operation is one of the few examples of significant local processing. It has been owned since May by Ambatovy Mineral Resources Investment Holding Company, a consortium led by Essenwood Partners with Zungu Investments that took over Sumitomo Corporation’s stake, and Korea Mine Rehabilitation and Mineral Resources Corporation.
Among other operators, Rio Tinto holds 80% of the QMM mineral sands mine, and Total Graphite (LSE: TGR; OTCQX: TGRHF), formerly Tirupati Graphite, owns the Vatomina and Sahamamy graphite projects in the Toamasina region, of which Vatomina has been paused since July for an optimisation programme and Sahamamy is on care and maintenance.
A UNCTAD assessment published in June identified 124 actionable products across eight sectors, most of them outside mining, that could create about 19,700 direct and indirect jobs.
See IntelliNews: How graphite could make Madagascar prosperous
Selection and reaction
Hart told Bloomberg that 15 countries had been considered, including the Democratic Republic of Congo, the world’s largest cobalt producer. Work already under way in the countries not selected would continue, he said. His office later said the six were selected using five criteria: government commitment; mineral endowment and development potential; UN system readiness; prospects for resource mobilisation; and demonstration and replicability value.
Governments in the first cohort welcomed the move. Zambia’s Foreign Minister Mulambo Haimbe said the country’s ambition was not simply to produce more copper but to create greater value at home through investment, value addition, industrialisation and jobs. Zimbabwe’s Foreign Minister Amon Murwira said the country, as one of the world’s leading lithium producers, recognised that critical minerals were central to the global energy transition.
UNDP Administrator Alexander de Croo said critical minerals could help countries diversify and transform their economies if value creation, environmental protection and good governance were pursued together. UN Environment Programme Executive Director Inger Andersen said the agency would help countries protect environmental integrity and advance circularity.
The limits: finance and governance
Financing remains a central constraint. Building refineries, processing plants and the supporting power and transport infrastructure needed to move further down mineral value chains will require capital on a scale beyond policy and regulatory assistance alone.
Independent governance experts have welcomed the initiative but cautioned that value addition will require more than technical assistance. Suneeta Kaimal, president and chief executive of the Natural Resource Governance Institute, said participating countries would need stronger negotiating positions, robust governance and meaningful participation by civil society and affected communities to avoid repeating the inequities of earlier mineral booms.
Publish What You Pay Indonesia, a transparency campaign group based in the cohort’s only non-African member, raised a more specific concern about implementation. National coordinator Aryanto Nugroho said in a September 25 statement that it must be clear who will have a seat at the table before country-level work plans are drawn up, because communities around mines and smelters bear the greatest social and ecological costs. The UN announcement did not mention the role of civil society and Indigenous peoples, or set out a funding scheme or implementation timeline, Tempo reported.
For the companies involved, the programme’s value will be measured by whether processing plants become easier to finance, power and supply. Until then, the advantage lies with those already building or operating capacity: Chinese groups in Guinea, Nigeria and Zimbabwe, and producers with domestic smelting capacity such as Mopani in Zambia. Western-backed projects include CBG’s proposed Guinean refinery, which is still seeking finance, and Madagascar ventures whose planned downstream processing is offshore. The states’ own direct stakes include Guinea’s 49% of CBG and the Zambian state investment vehicle’s share of Mopani.