Showing posts sorted by relevance for query P3 PUBLIC PENSIONS FUND PRIVATIZATION. Sort by date Show all posts

Saturday, November 25, 2006

P3= Public Pension Partnerships


In Canada the biggest players in the P3 racket are public pension funds. Public sector workers pensions in fact. Both the Ontario Teachers Pension fund and OMERS are funds that are wanting to invest in privatization of public infrastructure. So perhaps we should call these P3's Public Pension Partnerships.

Is there a problem with this? Well yes there is because these funds are not controled by the workers who pay into them but by professional investment managers. In Canada private sector union pension funds also look to invest in infrastructure. This would not be problematic if the workers whose pensions make up these funds actually had control of the funds, hired the managers and set the mandate for investments. But they don't. Unions need to put pension fund reform on their agenda's

With direct control of these pension funds and their investments public sector workers could use it as leverage for for social equity, environmental stewardship, job security, living wages, etc. etc.

The myth of private sector partnerships with the state is just that a myth. What this is really is public sector funding of the state. And the irony is that the whole P3 racket was supposed to be about the private sector taking a risk with it's investments. It was part of the neo-con myth that the private sector is more efficient than the public. It was an attempt by them to reduce the public sector, to contract out public sector jobs. Now that same public sector with its pension funds and public sector workers that are being used to fund government infrastructure.


So is every Canadian. When CPP was privatized, to allow an arms length investment arm to be created we now have our federal pension plan engaging in P3's as well as other questionable investments such as in the Arms Industry and Wal-Mart.

Like union pension funds, Canadians need reform of the CPP to have citizen representatives including labour, women, environmental and consumer groups, on the board with ethical guidelines for investing.

The Harper Conservative Government push for P3's is not about free market economics (ain't no such a creature in capitalism) it is just good old fashioned conservative state capitalism.


P3 or not P3? Big pension funds hope for new infrastructure opportunities

TORONTO (CP) - Canada's major pension funds, after investing billions of dollars abroad in assets ranging from British waterworks to New Zealand timberland, are hopeful that a logjam holding back their flow of money into infrastructure within Canada is giving way.

The Ontario Teachers' Pension Plan is acquiring its first piece of Canadian infrastructure - the dominant freight container terminal operation on Canada's Pacific Coast - as part of a US$2.4-billion deal announced Thursday.

The announcement coincided with indications the federal government will smooth the road for pension fund investment in public infrastructure such as highways, transport hubs and utilities.

The Advantage Canada plan outlined by Finance Minister Jim Flaherty on Thursday included a pledge to give maximum impact to government spending through public-private partnerships.

These so-called P3s "will also provide opportunities for Canadian pension funds and other investors to participate in infrastructure projects here in Canada rather than being forced to look abroad, as is often the case now," according to the finance ministry.

Flaherty plans to set up a federal P3 office, and intends to force provinces and municipalities to "consider P3 options" for all large projects that get federal funding.

"It's about time," Michael Nobrega, CEO of the Borealis Infrastructure unit of the Ontario Municipal Employees Retirement System, said Friday.

"We hope he follows through. Pension funds are looking to put money out, so until the follow-through occurs it's not real, but's certainly very, very encouraging."

At the Teachers fund, officials are "quite heartened . . . because Canada has not had a lot of infrastructure opportunity," said Deborah Allan, director of communications for the pension plan, which has $96-billion of assets under management.

Teachers announced Thursday it is paying US$2.4 billion to Orient Overseas of Hong Kong for Deltaport at Roberts Bank south of Vancouver and Vanterm in the Burrard Inlet inner harbour - which operate under long-term leases with the federal Vancouver Port Authority - as well as the New York Container Terminal on Staten Island and the Global Terminal and Container Systems complex in Bayonne, N.J.

The Canadian and U.S. port terminals are of roughly equal value, said Jim Leech, who heads the Teachers fund's private capital portfolio.

In the wider Canadian infrastructure world, "the main complaint that pension funds have had is whether or not the levels of government have the political will to have public assets owned by private enterprise," Leech said.

"You've got some people ideologically opposed, believing that all public infrastructure - highways, airports, et cetera - should be owned 100 per cent by the government, and taxes should just go up to fix them," he said.

"We've been sitting on the sidelines, waiting for the debate to be had and somebody to make a decision."

In the meantime, Teachers' foreign infrastructure investments include Scotia Gas Networks in Scotland and England, 10 power plants internationally, and the Northumberland Water Group in the U.K., along with large timber tracts in New Zealand and the United States.

Other Canadian pension funds have also gone abroad. The Canada Pension Plan Investment Board last month put $1.05 billion into a consortium bid for British water utility AWG PLC, the CPP's largest infrastructure investment to date.

The volume of pension fund money going into infrastructure is increasing globally, observed Andrew Harrison, a pension specialist at law firm Borden Ladner Gervais.

"The principal reason is that these, by their nature, are long-term assets - and that's the key in a pension fund, where you've got people who are accruing benefits today who won't see their last payment out of the fund for 50 or 60 years," he said.

Infrastructure "also tends to provide some inflation protection, in that the payments off the infrastructure tend to rise over time."

The only potential pitfall he sees is that infrastructure assets "tend to be illiquid; if something does happen it's very hard to unload one of these investments."

Rock Lefebvre, vice-president of research at CGA-Canada, observed that defined-benefit pension funds can't depend on safe fixed-income instruments such as bonds to cover their future liabilities.

"They have to risk, so this is a fairly nice risk for all the parties involved."

Domestic infrastructure would have the extra advantage of eliminating currency risk, but fund managers have been complaining for years that Canada's governments have been slow to allow private money into public projects.

"Governments are starting to realize that they can't fund all the infrastructure investment that has to happen," said Harrison, who heads the government relations committee of the Association of Canadian Pension Management.

"You've got these enormous capital pools in Canada to pay benefits to Canadians. There does seem to be a symmetry to using that money to invest in the infrastructure those same Canadians use."


See

P3

CPP


Find blog posts, photos, events and more off-site about:
, , , , , , , , , , , , , , , ,
, , , , , , , , , ,

Wednesday, April 11, 2007

Public Pensions Fund Private Partnerships


The battle of publicly funded pensions funds, your money and mine, being used in collaboration with private equity firms, hedge funds, to do leveraged buyouts needs to be seriously addressed, since those who pay into these funds have no controlling say over the fund managers.

As Robert Blackburn of New Left Review has written, the pension funds created over the past fifty years are huge new source of capital available for use to shore up capitalism.

But it is still public money, from union or public sector and government pensions. But without any meaningful corporate regulations giving the owners of these funds, us, any say in how they are invested. The democratization of public and institutional funds needs to be on the agenda of unions, the left, and the public. While institutional funds like pension funds call for their rights as shareholders, they do not allow their own shareholders the same rights of representation.

Teachers' BCE campaign gaining support

Some of BCE Inc.'s largest shareholders are lining up behind the Ontario Teachers Pension Plan and pledging to support the pension fund if it attempts to lead a takeover of the telecommunications company or even oust its embattled senior management.

Teachers, exasperated with BCE's weak stock performance under chief executive officer Michael Sabia, has already approached U.S. buyout firm Providence Equity Partners Inc. to explore a bid for the company worth close to $40 a share, according to sources.

That hefty price -- about a 30-per-cent premium to where BCE was trading last month -- could be enough to sway many of the company's long-suffering investors if Teachers decides to act. Although it chose not to submit a formal bid after BCE indicated it wasn't interested in selling, Teachers ratcheted up the pressure on the company in a regulatory filing this week by signalling its intentions to shift from a passive investor to an active one. Several investors said the only way BCE may be able to fend off an unwanted suitor now is for Mr. Sabia to step aside.

He said Teachers, like many investors, has become frustrated by what it views as unresponsive management and the glacial pace of Mr. Sabia's turnaround strategy.

In a filing with U.S. regulators on Monday, the pension fund said it was "exploring its options" regarding BCE, and sources confirmed it has been in contact with several buyout firms and pension funds in both Canada and the United States about the prospect of a takeover. The filing came less than two weeks after it was revealed that BCE had spurned another advance from private equity titan Kohlberg Kravis Roberts & Co., which has allied itself with the Canada Pension Plan Investment Board.

These sources described the KKR advance as a "wake-up call" for Teachers, which is bent on leading any privatization effort of the Montreal-based parent of Bell Canada. One person familiar with the matter said the $106-billion pension fund is dismayed by the cool reception its proposals have received from both Mr. Sabia and BCE chairman Richard Currie. Mr. Sabia and Mr. Currie could not be reached for comment.

"At some point the shareholders will speak," said one person familiar with Teachers' plans. "Boards of directors are supposed to represent the shareholders at the table."

See

P3

AIM High

Your Pension Dollars At Work

P3= Public Pension Partnerships


Find blog posts, photos, events and more off-site about:
, , , , , , , , , , , , , , , ,
,

Thursday, February 19, 2026

P3; PUBLIC PENSIONS FUND PRIVATIZATION
Investing Public Pensions in Fossil Fuel and AI Companies Is More Than Amoral – It’s Bad Business

Corporations are using the hard-earned money of today’s workers to further their own goals—many of which are directly at odds with the goals, livelihoods, and futures of public employees.


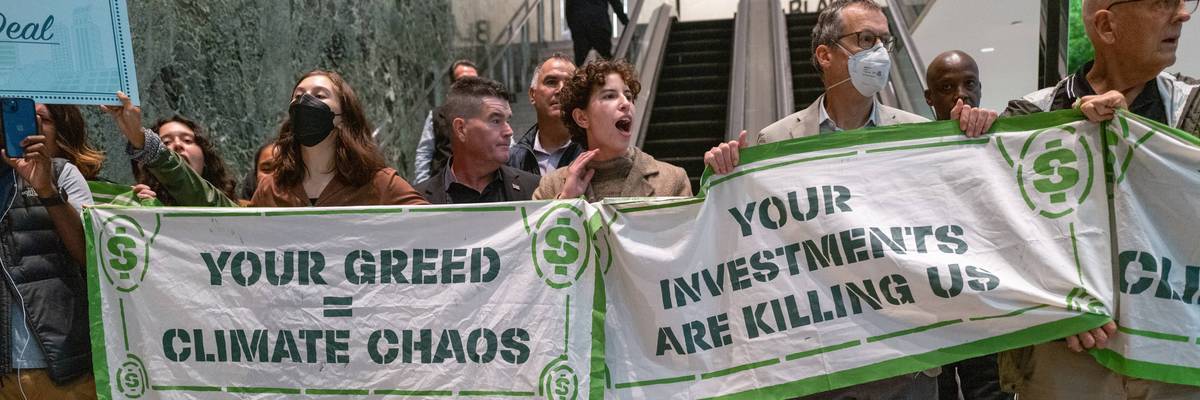
Climate activists block an escalator and throw coal on the ground at the New York headquarters of the financial investment firm BlackRock on October 26, 2022 in New York City.
(Photo by Spencer Platt/Getty Images)
Stephen Lerner
Feb 18, 2026
Common Dreams

Our country faces an affordability crisis amidst fundamental attacks on democracy. Public employee pension plans can either be part of the solution or part of the problem.

Late last year, New York City Comptroller Brad Lander recommended the city’s pension boards drop BlackRock and other portfolio managers that don’t have decarbonization plans up to the city’s standards. Lander’s initiative was blocked, and the editorial board of The Washington Post accused him of playing politics. But Lander argued that his recommendation was in line with the government’s fiduciary duty to protect the long-term value of pension funds, the retirement systems most public sector workers rely on—and have been paying into their entire careers. He’s right. In this critical moment in history, companies that are actively hastening climate change, threatening housing security, eliminating jobs and industries, and destabilizing our democracy and economy do not deserve our investment. Yes, they are acting immorally but they are also very bad investments with little promise of future returns for public sector workers. It’s not “playing politics” to refuse to fund their efforts to dismantle our society. That’s why we’re calling on pension boards across the country to take a hard look at their portfolios and make the smart business decision: stop investing in companies like this today.

The stakes could not be higher: pension funds account for $6.1 trillion in state and local defined-benefit funds alone. Every month, nearly 15 million workers across the country contribute part of their paycheck to ensure they have enough income to retire securely. This is a big pot of money and the companies that boards choose to invest it with matter. For public sector workers, pensions are not only retirement funds, but deferred current compensation. Workers are forsaking their hard-earned money today for the potential of a dignified future. Meanwhile, corporations are using that money today to further their own goals—many of which are directly at odds with the goals, livelihoods, and futures of public employees.

The interests of public workers and these companies dangerously diverge, but even the one area of alignment is fraught: secure return on investment.

Public pension systems across the country, including the California State Teachers’ Retirement System (CalSTERS), California Public Employees’ Retirement System (CalPERS) and New York City retirement funds, are heavily invested in Blackstone, the private equity company turning profits by hiking up rents during a housing affordability crisis. RealPage, the company sued last year by the DOJ for allegedly operating a nationwide rental price-fixing scheme, has investments from over a dozen pension funds through private equity funds. Public workers are watching their deferred compensation funnel into corporate exploitation while they fight to pay their own rent or mortgages.

Palantir, the data surveillance software company whose co-founder has stated his support for public hangings and apartheid, has multi-million dollar investments from The Teacher Retirement System of Texas, the Ohio Public Employees Retirement System, CalPERS, CalSTERS and other pension funds. Palantir’s tools have been used by the military to conduct destabilizing wars around the world, by DOGE to gather and merge data on millions of US residents, endangering the safety and security of us all, and by ICE to terrorize individuals and families across the country— threatening our democracy at home and abroad.

The interests of public workers and these companies dangerously diverge, but even the one area of alignment is fraught: secure return on investment. We are almost undeniably in the midst of an AI bubble, much larger than the dot com bubble that came before. With so many pension fund portfolios overly concentrated in the tech industry, funding new data centers built on speculative calculations and crypto companies propped up by hype—Palantir, Coinbase, VC firms like Andreessen Horowitz and others, NVIDIA and many more—a shift in the global appetite for new technology could empty the pockets of millions of workers. Short-term gains are not a good predictor of long-term returns for investors like public employees, who are stuck with the terms of their retirement funds and can’t pull out when markets turn. When the editorial board of the Washington Post writes that “the job of pension fund managers is to maximize returns for retirees who depend on them,” they should take these very real—and apolitical—risks into account.

Public pension funds are an enormous engine driving the economy today, and the investment choices that pension boards make are critical to the future of the country and the world. When boards invest workers’ money, they contribute to the specific visions and plans of companies and the people who run them. And when those plans include the destruction of our environment, our right to housing and fair work, and our democracy, it’s assisted suicide. Today we are urging pension boards to think beyond short-term gains and market bubbles. We’re calling on leaders to speak out and push for change as Former Comptroller Brad Lander did. Public worker retirement money must be invested responsibly in a secure future for us all.


Our work is licensed under Creative Commons (CC BY-NC-ND 3.0). Feel free to republish and share widely.


Liz Perlman
Liz Perlman is the executive director of AFSCME 3299, the University of California’s first employee union — representing more than 40,000 Service workers (SX), Patient Care Technical workers (EX), Skilled Craft workers (K7), and more at UC’s 10 campuses, 5 medical centers, numerous clinics, research laboratories, and UC Hastings College of Law.
Full Bio >

Stephen Lerner
Stephen Lerner is a fellow at Georgetown University's Kalmanovitz Initiative for Labor and the Working Poor and is one of the architects of the Justice for Janitors Campaign.
Full Bio >

Sunday, August 26, 2007

Infrastructure Collapse

When your infrastructure was built fifty years ago, and was expected to only last half that time, well this is what happens when you waste a decade fighting the deficit chimera of the nineties.
Tunnel ceiling cracks close Montreal streets

–A large section of downtown Montreal will remain closed for the weekend after two cracks were found in a tunnel that makes up part of the underground city.

Montreal police widened a safety perimeter last night to include a number of blocks in the city's downtown core after officials felt there was a real risk of a road collapse following the discovery of cracks in an underground tunnel.

Fire chief Serge Tremblay told reporters last night that a second fissure was also found, but experts haven't been able to conclude what caused the cracks or how long they had been there.


Bridge to Laval latest to undergo repairs

Since the collapse last year of the Laval overpass, Quebec's Transport Department has been conducting more thorough inspections of the province's infrastructure.

Last week, responding to fears a 69-year-old north-end Montreal overpass could collapse because its concrete has "weakened," the city barred all trucks from the heavily-used structure and announced plans to demolish and rebuild it next year.

This is the empirical result of the neo-conservative political agenda of reducing taxes and regulations,failing to fund infrastructure and public services, and promoting privatization.

Bridges in Canada have reached 49 per cent of their useful life, according to a 2006 Statistics Canada study, and experts warn our country's roads, wastewater plants and other infrastructure isn't in any better shape.

A Statistics Canada study examining the age of infrastructure in Canada cited wastewater treatment facilities as the oldest, with 63 per cent of their useful life behind them in 2003. Roads and highways had reached 59 per cent of their useful life, and sewer systems 52 per cent.


Of course it is not only occurring in Canada, but also in the U.S. which originated the daft ideology of the neo-cons.

Emergency personnel look over a truck that lies in a hole in the street after a steam explosion in midtown Manhattan, New York, Wednesday, July 18, 2007. (AP Photo/Seth Wenig)


Cataclysmic infrastructure collapse: Who pays?
A recent Minneapolis bridge collapse and New York steam pipe explosion, both of which collectively caused the deaths of at least six people and more than US$250 million in damages, has brought infrastructure liability to the fore, according to a report by KPMG.

At issue is whether insurers are on the hook for the cataclysmic failure of a decaying urban infrastructure.

KPMG Insurance Insider quotes Claire Wilkinson, the vice president for global issues at the Insurance Information Institute, on the issue of where liability falls in the event of a massive infrastructure failure.

She notes that, in the United States, federal and local authorities that administer bridges and road can claim "sovereign immunity" to avoid liability. But she adds the common-law defense may no longer apply if the infrastructure was under repair, opening the public entities and contractors to charges of negligence..
"A contractor employed by the state could cause damage where the state would be held liable," KPMG quotes Wilkinson as saying.

And even if a contractor has liability coverage, Wilkinson adds, in a world of multi-million construction projects, the limits would likely be quickly eclipsed. KPMG notes that in the event a state contractor exceeded liability limits, the pubic entity might be held responsible for project liability associated with the costs of reconstruction, casualty, property business interruption and/or workers compensation claims.
And so the result is the idea that P3's will solve the under investing done by Governments at all levels for the past two decades. Except the so called 'private' partner, ain't. It's your and my pension funds. In other words you and I pay twice, as taxpayers then as Pension Fund participants.

The bridge collapse in Minneapolis is giving rise to other concerns. Hundreds of billions is needed to rebuild the nation's infrastructure. It's not just roads and bridges. It's also generation and transmission.

Enter infrastructure investing: Public and private pension funds currently invest in varied assets that range from stocks to bonds to real estate. But some are now taking a look at vital infrastructure as a way to earn better-than-average returns as well as to guarantee the longevity of an area's economic growth. If such allocations could provide competitive returns, pension experts say that fiduciaries and trustees would not violate their obligation to act solely in the interest of plan participants.


See:

Minister of P3

Mr. P3

Super P3

Public Pensions Fund Private Partnerships

Pension Fraud Brings Down Japans Government


Find blog posts, photos, events and more off-site about:
, , , , , , , , , , , , , , ,
,
, , , , , ,
, , , , ,


Wednesday, August 08, 2007

Dumb and Dumber


P3's don't save taxpayers money.

This was a costly dumb idea under the Mulroney Conservatives and the Harper Conservatives are going to repeat the same mistake.

The government has reportedly received advice that Edmonton's Canada Place is the most valuable of the nine buildings being considered for sale. It is worth $265 million if sold under a 25-year lease-back deal.

Canada Place was valued at $152 million when the Treasury Board approved its construction in 1984. But in 1988 Kenneth Dye, then the federal auditor general, reported that the new Edmonton home of 3,200 federal civil servants would end up costing taxpayers $100 million too much.

Part of the extra cost was the result of a decision to have Canada Place built privately under a lease-purchase deal instead of having the government build it.

And the irony in this is that it will be public sector workers pensions that will probably ending up owning it.

But Dawson wasn't sure how a benefit for business can work for the government.

"They're not in business and they're not necessarily going to re-employ that money at any kind of a return."

As for possible buyers for Canada Place, Dawson said large pension funds may be interested.

The Canadian Pension Plan Investment Board (CPPIB) now invests 45% of its assets outside Canada, up from 36% in 2005. Ontario Teachers' Pension Fund increased the percentage of non-Canadian assets in its equities portfolio from 56% in 2005 to 66% in 2006. OMERS has increased its foreign assets from 29% in 2000 to 39% in 2006.

With almost $500-billion in combined assets, the five top Canadian pension funds are getting a bigger piece of the global play book.

Not surprisingly, Canadian pension funds are now viewed as virtual private equity groups, says David Mongeau, of U.K.-based Avington International, a global mergers and acquisitions advisory firm that stickhandled a number of recent deals including the Legacy REIT sale with Caisse de depot, and the BCIMG purchase of the Canadian Hotel Income Properties Real Estate Investment Trust.

See:

Minister of P3

Mr. P3

Super P3

Public Pensions Fund Private Partnerships


Find blog posts, photos, events and more off-site about:
, , , , , , , , , , , , , , , ,
,
, , , , , , , , , , ,

Wednesday, November 07, 2007

Your Pension Plan At Work

We may end up owning an airport in New Zealand. I can't wait to retire and visit.

WELLINGTON (Reuters) - The Canadian state pension fund said on Wednesday it would make a partial all-cash offer for NZ's Auckland International Airport Ltd (AIA.NZ: Quote), a week after the company rejected a previous offer.

The Canada Pension Plan Investment Board said it would offer NZ$3.6555 a share for up to 40 percent of Auckland Airport shares valuing the company at around NZ$4.5 billion ($3.5 billion). CPPIB said Auckland Airport shareholders encouraged it to bid again, after the board rejected the previous proposal as too risky.

Shares in Auckland Airport, 23 percent owned by two local authorities, closed on Tuesday at NZ$2.91, having traded between NZ$2.06 and NZ$3.50 over the past 12 months.

($1=$1.29)


In response to a stinging snub from the board of New Zealand's largest airport, the Canada Pension Plan Investment Board (CPPIB) has fired back with a plan to take its partial takeover offer directly to shareholders.

After a months-long friendly process in which the Canadian pension fund manager was given ample access to Auckland International Airport Ltd.'s books, its board put out a surprising and sharply worded release last week quashing the CPPIB's bid.

Four of its five members voted against the offer for up to 49 per cent of the company. The revised all-cash offer is valued at $1.8-billion New Zealand ($1.3-billion Canadian) for 40 per cent.

Alongside its concern about the level of debt involved in the partial privatization, Auckland International's board also took an unusual poke at the expertise level of the $120.5-billion (Canadian) pension fund manager, which is considered by many to be one of the world's most sophisticated investors in infrastructure.

The CPPIB's second wind, however, has come from institutional investors including the airport's largest, the Auckland City Council.

The council owns a 12.75-per-cent stake and has encouraged the pension fund to continue on with its plan.

"We are really going down this route because shareholders have lobbied us to find a way to opine on the proposal," Mark Wiseman, CPPIB senior vice-president, private investments, said in an interview.

The airport's other large shareholders include the Manakau City Council, the city just south of Auckland in which the airport is located, along with infrastructure investors Macquarie Bank of Australia and New Zealand's Infratil Ltd.


Actually this is another case of public sector funds being used as a P3 Public-Public-Partnership. Privatization by another name,except all the investors are publicly owned institutions or pension funds. Ironic that.

Privatization of infrastructure is now being paid for by public funds. No capitalist is willing to invest in long term infrastructure. Not private equity companies or Hedge Funds. So while neo-cons promote the myth that private capital is willing to invest in public infrastructure the reality is that it is workers pension funds, public funds that are used to rescue the public sector and the commercial private sector investments in infrastructure.

Canadian pension plans, Australian bank to acquire Puget Energy

A multinational consortium lead by an arm of Australia's Macquarie Bank and including three Canadian public-sector pension plans is acquiring Puget Energy (NYSE:PSD) amid continued infrastructure investments by major Canadian pension funds seeking more lucrative returns to pay pensions.

The deal values the U.S. utility company at US$7.4 billion, including $3.2 billion in shareholder capital provided by the consortium, $2.6 billion in existing debt that will be assumed and $1.6 billion of newly issued debt.

In addition to Macquarie, the consortium includes the Toronto-based CPP Investment Board, British Columbia Investment Management Corp. and Alberta Investment Management.

"PSE is Washington's oldest and largest energy utility - it is a strong, stable company with a growing customer base in a market that has displayed consistent demand over time," Christopher Leslie, chief executive of Macquarie Infrastructure Partners, stated Friday.

TORONTO, ONTARIO--(Marketwire - Nov. 1, 2007) - RioCan Real Estate Investment Trust ("RioCan") (TSX:REI.UN) today announced its financial results for the three and nine months ended September 30, 2007.

Financial Highlights

RioCan reported net earnings for the quarter ended September 30, 2007 of $35,917,000 ($0.17 earnings per unit basic and diluted) as compared to net earnings of $41,763,000 ($0.21 per unit basic and diluted) for the three months ended September 30, 2006. For the nine months ended September 30, 2007, RioCan reported a net loss of $32,790,000 ($0.16 loss per unit basic and diluted) as compared to net earnings of $120,377,000 ($0.61 per unit basic and diluted) for the comparable period in 2006.

For the quarter ended September 30, 2007, rental revenue was $160,559,000 as compared to $145,339,000 for the three months ended September 30, 2006. Rental revenue for the nine months ended September 30, 2007 was $483,824,000 versus $429,291,000 for the comparable period in 2006.

FFO for the quarter ended September 30, 2007 was $76,029,000 ($0.36 per unit) as compared to $72,533,000 ($0.36 per unit) for the three months ended September 30, 2006. For the nine months ended September 30, 2007, FFO was $227,120,000 ($1.09 per unit) as compared to $209,440,000 ($1.06 per unit) for the nine months ended September 30, 2006.

RioCan's Consolidated Financial Statements, Management's Discussion and Analysis and a Supplemental Information Package for the three and nine months ended September 30, 2007 are available on RioCan's website at www.riocan.com.

FFO is a widely accepted supplemental measure of a Canadian real estate investment trust's performance and should not be construed as an alternative to net earnings or cash flow from operating activities determined in accordance with Canadian generally accepted accounting principles. RioCan's method of calculating FFO may differ from certain other issuers' methods and accordingly may not be comparable to measures reported by other issuers.

Portfolio Stability

At September 30, 2007:

- Portfolio occupancy was 97.6%;

- 65.1% of rental revenue was derived from properties located in Canada's six high growth markets (including and surrounding Calgary, Edmonton, Montreal, Ottawa, Toronto and Vancouver);

- 82.6% of annualized rental revenue was derived from, and 83.1% of space was leased to, national and anchor tenants;

- Approximately 49.7% of annualized rental revenue was derived from its 25 largest tenants; and

- No individual tenant comprised more than 5.7% of annualized rental revenue.

Development Activity

With over a billion dollars at cost of ongoing developments, project activities remained strong throughout the third quarter as RioCan continues to focus on its development program. At the end of the third quarter, approximately 8 million square feet was under development, of which RioCan's ownership interest was approximately 3.4 million square feet. Third quarter highlights include:

- Oakville, Ontario - RioCan Centre Burloak, located at the intersection of Burloak Drive and Queen Elizabeth Way, is a 552,000 square foot new format retail centre anchored by Home Depot (retailer owned), SilverCity Oakville Cinemas, Longo's and Home Outfitters. This joint venture with the Canada Pension Plan ("CPP") Investment Board is 100% leased with approximately 92% to be occupied by national and regional retailers.

Construction is well underway and store openings are now being phased-in. A number of retailers have recently opened for business including Home Depot, Nike, Sony and Tommy Hilfiger. Additional retailers opening by the end of 2007 include SilverCity Oakville Cinemas, Suzy Shier, Guess, La Vie En Rose, Reitmans, Le Chateau, Urban Barn, Benix & Co., Bowring and many more. Other retailers such as Longo's, Home Outfitters, Urban Planet, Kitchen Stuff Plus, Structube, Solutions, Kelsey's, Montana's and Swiss Chalet will be opening in 2008.


- Edmonton, Alberta - Construction is ongoing at RioCan Meadows, another development joint venture with CPP Investment Board. Upon completion, this 502,000 square foot new format retail centre will be anchored by a Real Canadian Superstore (retailer owned) and Home Depot. Some retailers that recently opened for business include Winners, Dollarama, TD Canada Trust and Wok Box. Additional retailers opening later this year and in 2008 include Petsmart, Reitmans, Laura, Scotia Bank and Swiss Chalet.

- Calgary, Alberta - Also moving towards completion is the construction of RioCan Beacon Hill, a 788,000 square foot new format retail centre featuring shadow anchors Costco and Home Depot, both of whom are open for business, as well as Canadian Tire and Shoppers Drug Mart, both of which are expected to open in spring 2008. This joint venture with Trinity Development Group Inc. and CPP Investment Board boasts a number of national retailers, many of which are already open for business, including Winners, HomeSense, Royal Bank, Linens 'N Things, Golf Town, Michaels, The Shoe Company, Mark's Work Wearhouse, LaSenza, Thyme Maternity and Sport Chek. Additional retailers such as EB Games, Telus and Bell Mobility are anticipated to open later this year.


However what remains lacking is shareholder control of our pension funds. Without that we have no checks and balances on how our funds are being used, for instance if jobs are cut at the airport which are not in our interests or those of the workers affected.

Or in the case of affordable housing our pension funds are being used for commercial real estate investments instead of creating affordable housing in overheated markets.

While institutional funds, as our public pension funds are called in the investment industry, cry for more control over the boardrooms of the companies they invest in, we the owners/shareholders of these funds have no say in their boardrooms.

This is an issue the labour movement and civil society needs to address soon.
Canada says G7 to discuss state investment funds

Group of Seven finance ministers will discuss the need for more transparency by state-backed investment funds in a meeting on Friday and will likely mention the issue in their final statement, a Canadian government official said on Tuesday.

Ministers from the world's richest nations will gather in Washington on Friday to discuss the global economic outlook following this summer's credit crunch as well as possible regulatory changes for financial market players.

But sovereign wealth funds are also high on the agenda and will be the subject of an "outreach session" with non-G7 members Friday evening, said the official, who declined to be named.

Although they are not new, these funds have grown in number and size in recent years as the central banks of oil-rich Middle Eastern countries and countries such as China, which have huge reserves, invest in riskier assets in search of higher returns.

The main concern in Canada and other countries is that not enough is known about the huge capital flows from these funds, which can create imbalances in the global financial system. The funds need to be guided by clearly stated market-based principles to assure the countries hosting their investments that they are not motivated by anything other than economics, the official said.

At a special meeting that will also include China, Korea, Kuwait, Norway, Russia, Saudi Arabia, Singapore and the United Arab Emirates, Canada will hold up its Canada Pension Plan Investment Board as a model of accountability that could be adopted by state-owned investment funds. Norway's state fund is another model.

The CPP Investment Board is responsible for investing pooled pension assets worth C$120.5 billion and operates at arm's length from the government, with an independent board of directors. It undergoes external audits every year and tri-annual reviews by government authorities.

It is required also to hold public meetings periodically and to disclose its investment performance on its Web site.


Charge higher CPP premiums to firms without pension plans

The National Union of Public and General Employees (NUPGE) is launching a campaign to change Canada Pension Plan rules, requiring employers without workplace pension plans to pay higher Canada Pension Plan (CPP) premiums.

The extra money would be used to pay higher CPP benefits at retirement to workers who do not have a workplace pension plan.

NUPGE outlined the proposal at a recent conference attended by more than 300 union representatives and leading pension policy experts. The event was arranged by the Canadian Labour Congress (CLC), which brings together affiliated unions with a combined membership of more than three million members.

NUPGE is one of Canada's largest unions, representing 340,000 public and private sector workers across the country. Collectively, the NUPGE members participate in pension funds with combined assets of more than $100 billion.

The union recently released a research report identifying an alarming decline in pension coverage in Canada. The report revealed that the percentage of the Canadian workers covered by a pension plan declined from 46% in 1991 to 38.5% in 2005.

Employers lack incentives to provide pensions

Larry Brown, NUPGE's national secretary-treasurer, says Canada now provides few incentives for employers to create pension plans, despite the obvious social and economic benefits of doing so for workers and for society in general. In fact, disincentives exist to discourage employers from setting up their own plans, he said.

Brown says employers with pension plans now pay exactly the same CPP premiums as those without plans. At the same time, they assume legitimate administrative costs and requirements set out in pension legislation, including funding obligations and reporting and actuarial evaluations, he said.

“Employers have a moral obligation to their employees to provide decent pensions, but our system does very little to encourage this behavior. Instead, it subjects employers who provide pensions to necessary but often complex legislative requirements,” Brown notes.

"Why should an employer assuming the burdens and obligations of providing a pension plan pay the same CPP premiums as employers who do not?" he asks.

“We don’t think that makes sense and we’re launching a campaign that calls for an extra payment to the CPP from those employers that don’t offer a workplace pension plan,” he says.

"We are saying that employees should receive improved CPP benefit coverage during any years they work for employers without a workplace plan, and those benefits should be financed by additional CPP premiums collected from employers who do not offer pension plans.”

Brown says this would create an incentive for employers to provide pension plans. "They would pay for a workplace pension plan, or pay higher CPP premiums. Either way, they would be required to meet their moral obligations to their employees”, he said.

SEE:

Vencap

AIM High

P3 Myth Busting

Infrastructure Collapse

Fire Sale

Dumb and Dumber

Public Pensions Fund Private Partnerships

Golden Parachutes

Your Pension Dollars At Work

P3= Public Pension Partnerships


Find blog posts, photos, events and more off-site about:
, , , , , , , , , , , , , , , ,
,

Tuesday, August 21, 2007

Fire Sale


After costing taxpayers an extra $100 million dollars in construction costs due to being a Mulroney government P3 the Federal Building in Edmonton and eight others across Canada are being sold at fire sale prices.

The $400 million they make off this mistake will not cover the 25 year rental cost to taxpayers of $79 million a year. Instead it's going to cost us almost $2 billion to lease back.

So would you sell your house and then rent it back, and agree to invest in upgrades? This is another example of neo-con ideology trumping economic common sense.


The federal government is selling nine office complexes, including two in Ottawa, to a private Vancouver developer for $1.64 billion -- $400 million more than the appraised value for the properties.

At the same time, the union representing many of the federal workers in the buildings labelled the deal "a give-away of colossal proportions."

"In addition to ceding ownership of the nine premium properties, the federal government has, in effect, written a $630-million cheque signed by Canadian taxpayers," said Patty Ducharme, the union's national vice-president.

The union cited its own study, done by Informetric, an Ottawa economic consultant. It valued the nine properties at almost $2.3 billion, Ms. Ducharme said.

The deal involves the sale of government property to Larco Investments Ltd., but also requires the federal government to lease back the office space for 25 years. That substantially reduces the risk to the new private owner.

The lease-back agreement calls for the government to pay base rent of $79 million a year plus operating and maintenance costs, officials said. Rents will be set annually by Public Works and Government Services to cover agreed-upon services, including annual maintenance costs.

Of the $1.644-billion purchase price, $1.567-billion will go to the government. Of this, RBC and BMO will each receive commissions of $5.7-million, according to a government official. There will also be up to $500,000 in expenses for the sale.

The remaining $77-million of the sale price will be used to undertake a 10-year capital repair program, while the government will be responsible for other expenses, including maintenance, repairs and other building improvements.

The government has agreed to lease back the nine buildings for 25 years, with payment amounts rising in five-year increments. Lease payments will total $505.3-million over the 25 years, rising from $82.2-million in the first five years, to $122.1-million in years 20 to 25.


See:

Minister of P3

Mr. P3

Super P3

Public Pensions Fund Private Partnerships


Find blog posts, photos, events and more off-site about:
, , , , , , , , , , , , , , , ,
,
, , , , , , , , , , ,

Saturday, March 24, 2007

AIM High

Having been burned with government bureaucrats running the Alberta Government Venture Capital fund (VenCap) it was sold off by the Ralph regime to Onex corporation in 1995.
It had potential, and even with a deficit its shares were worth $8 on the TSX. Which was not bad for the time. But the debt and defict hysteria led the government to sell off this potential golden goose.

In terms of publicly-funded venture capital funds, Alberta’s experience has not been positive. Vencap was established by the Alberta government with funding of $240 million and the objective of investing in venture capital. Vencap experienced many of the same problems as LSVCCs – a lack of good investments and a reluctance to take risks. As a result, a relatively small percentage of Vencap’s equity ended up in new Alberta ventures. The Alberta Opportunity Company faced similar problems in operating a program to support investments in start-up knowledge-based industries.


Yet its deficit was still underwritten by the Heritage Trust fund five years later, the Ralph regime was panic driven, selling off all government services it could at fire sale prices..

December 2000: All of the loans made to provinces from 1977 to 1982 have been paid back on time and without any missed payments. The only project loans left on the Heritage Fund books are Vencap and Ridley Grain Ltd. for a total of $98.8 million, which represents 0.8% percent of the Heritage Fund's total portfolio.


The Government is
a risk averse regime that would rather underwrite private capitalists than use it's own capital.

Institutional investors key to growth of city's tech sector

Unlike other provinces and public pension funds, including the federal CPP, Alberta was more interested in selling off government assets and services to the private sector, than developing its capital base with the Heritage Trust fund and its other investment funds.

Risk adverse, wanting to divest itself of any economic responsibility, "we are not in the business of business", the government finally has realized it is a capitalist state and should be investing its social capital. However its social capital is not just the Heritage Trust fund, but public sector pension funds as well.


In a move predicted to earn up to an extra $500 million a year, the Stelmach government plans to create a new provincial Crown corporation to oversee $70 billion worth of financial assets.

The Edmonton-based investment powerhouse will be the fifth-largest pool of managed capital in Canada.

It would be exceeded in size only by the Caisse de depot et placement du Quebec ($143.5 billion), the Canada Pension Plan Investment Board ($111 billion), the Ontario Teachers' Pension Plan ($96.1 billion), and the B.C. Investment Management Corp. ($76.3 billion).

AIM Corp. would assume responsibility for managing the $16.3-billion Alberta Heritage Savings Trust Fund, several public endowment funds -- including the Alberta Heritage Foundation for Medical Research -- and a basket of public-sector pension funds.

The latter includes the $13.5-billion Local Authorities Pension Plan (LAPP), the province's largest public pension fund, and the $5.7 billion Public Service Pension Plan, among several others.

A recent study for the government concluded a stand-alone organization would be the best way "to achieve investment excellence," Alberta Finance said in a brief news release.

"The proposal follows best practices for top public sector investment funds such as the Canada Pension Plan, the B.C. Investment Management Corporation and the Ontario Teachers' Pension Plan."


During the Ralph regime everything not making money was sloughed off and contracted out or privatized. In order balance out the reduction in royalties and taxes coming in from the Oil industry, in the nineties the PC's found that like many governments they were carrying pension debt. As the third party to the Local Authorities Pension Plan(LAPP) which covers all MUSH employees and management in Alberta, they never contributed to the plan, rather like other governments they put all pension earnings into general revenues.

In the late nineties with a deficit and debt crisis, they looked at the debt they owed the LAPP and hived it off in plans to allow the contributors, employees and management as well as MUSH employers, to run it. Without of course the governments missing contribution. This left the LAPP in a deficit situation, causing its members to have to pay for the governments debt owed them.

In return for paying down the governments debt to the LAPP the members of the plan were offered investment autonomy, with moves to privatize the plan under membership control. Which was not a bad thing. It removed statist bureaucracy and red tape at a time when the market was booming, and as a fund managed by employee representatives from unions, management and professional associations, and employers. The board was in place, and hired its own CEO,and investment managers, as well as holding a series of input meetings with the membership, both for feedback and for an explanation as to how the funds would be managed.

In a short five years the LAPP was out of debt and the members actually paid less then was expected and in fact got a payback for overpayment's of the government debt. The reason? Bre-X. While the Bre-X swindle saw many make fortunes on the largest run of a penny stock to a $200 share in the shortest period in Canadian mining history, even for the mining scandals of the sixties, many also lost fortunes as the shares collapsed under the salting scandal that ensued. But not the LAPP they made money off Bre-X, and other investments. Because they were autonomous and now were no longer risk adverse, that is they were investing to make up the deficit, while maintaining the capital for their fiduciary responsibility to their retirees.

Once out of debt and making money, as they have for a decade, the government realized it was selling the golden goose if it allowed full autonomy, it reigned in its plans to privatize the LAPP. It remained under autonomous management but was still a subject to regulation by the Finance Department.

Had it been allowed full autonomy it would have made even more money. As it was with partial autonomy, and its own investment policies and managers it went from a deficit to $13. 5 Billion in assets.

Seeing it had a golden goose again, the Government has refused out right autonomy and has moved away from privatization of LAPP. Which may be the reason for it not wanting to talk about how it is looting public pension funds to underwrite its new investment corporation.

I almost missed it, but there it was, posted on the Alberta finance department's website.

The cryptic, one-page news release outlined a bill, introduced in the legislature Tuesday, to create a new provincial Crown corporation called Alberta Investment Management Corporation, or AIM Corp.

It will boast roughly $70 billion in assets.

That was it. There was no fanfare. No press conference. No grandiose quotes about the cosmic significance of this bold initiative from Alberta Premier Ed Stelmach, or Finance Minister Lyle Oberg. In fact, the latter didn't even respond to my followup call Wednesday. A department flack did.

The release itself was so blandly written it appeared designed to put reporters to sleep.

There is an irony here in that the ultimate capital partner in government P3 projects is not private hedge funds, nor private industry, but public pension funds. The Alberta government will find itself funding its own P3 projects with its new AIM Corporation. Just as governments world wide are being funded by Canadian institutional pension funds. And these same pension funds are crying about not having more government real estate and infrastructure projects in Canada to invest in.


See

P3

Your Pension Dollars At Work

P3= Public Pension Partnerships


Find blog posts, photos, events and more off-site about:
, , , , , , , , , , , , , , , ,
,

Saturday, July 22, 2023

The Privatization of Water Is a Scam
07.22.2023

British water companies have loaded up with debt while pumping sewage into waterways, raising bills and delivering huge profits to shareholders. This can only end by the government taking water back from these corporations.

An aerial view shows the Thames Water Long Reach water treatment facility on the banks of the Thames estuary in Dartford, east of London, on March 3, 2023. (Ben Stansall / AFP via Getty Images)

The neoliberal obsession with privatizing essential industries and services is haunting the UK. Profiteering by gas, oil, railways, mail, and other entities is the root cause of the current high inflation and misery for millions. The water industry has been hoisted by its own profiteering, and Thames Water, England’s largest water and sewage business, is teetering on the edge.

The seeds of destruction were sown by the 1989 privatization. The government sold water entities in England and Wales for a meagre £6.1 billion. In the absence of parallel water and sewage pipes, competition isn’t possible, and companies have captive customers.

The industry has adopted the classic private equity business model. Its key elements are high prices, low investment, and financial engineering to extract high returns. Instead of shareholders making long-term investment through equity, the business model uses debt because interest payments qualify for tax relief — effectively a public subsidy. This reduces the cost of capital and increases returns to shareholders, but also increases vulnerability to interest rate hikes.
Minimum Investment, Maximum Profits

Since 1989, water charges have increased by 40 percent in real terms. Companies seem to have a profit margin of 38 percent, a very high percentage for a no-competition, low-risk business whose raw material virtually falls out of thin air.

Some 2.4 billion liters of water are lost every day to leaks due to poor infrastructure. Despite the population growing by nearly ten million, no new reservoirs have been built. Water companies are required to provide clean water but have actually increased contamination by dumping sewage into rivers. Unplugged leaks and sewage dumping increase profits, dividends, and performance-related executive pay.

A report from the House of Lords estimated that the industry needs between £240 billion and £260 billion of new investment by 2050, compared to £56 billion suggested by the government. However, the industry has been focused on cash extraction. It has paid out £72 billion in dividends since privatization and is expected to pay another £15 billion by 2030. It has debts of around £60 billion. Of each £1 paid to the industry, 38p is earmarked as profit. Out of this 20p services debt, 15p is taken by dividends and 3p for things such as tax.

The focus on investment and efficiency has been low. The industry assumed that it could carry on borrowing at low cost forever. Household bills are inflated to cover the cost of borrowing, which would not be necessary if the regulator, the Water Services Regulation Authority (Ofwat), had insisted on prudent practices.

There is the usual story of regulatory capture or at least cognitive alignment. Around two-thirds of England’s biggest water companies employ key executives who previously worked at Ofwat. Six of England’s nine water and sewerage companies have hired directors of corporate strategy or heads of regulation who previously worked at Ofwat.

For years, red flags have been publicly raised about financial engineering at water companies. In 2018, Ofwat suggested that “gearing” or the debt ratio at water companies should not exceed 60 percent (there is a complex calculation), but companies have resisted that.

Years of regulatory indulgence have been given visibility by the crisis at Thames Water. Thames loses around 630 million liters of water a day in leaks and routinely dumps tons of raw sewage in rivers. Since 2010, it has been sanctioned ninety-two times for failures and has been fined £163 million. Over the last three years, the salary of its recently resigned chief executive doubled.

Since privatization, it has paid £7.2 billion in dividends and has debts of £14.3 billion secured against £17.9 billion of regulated operating assets. In common with other water companies, it has used index-linked bonds for its borrowing, meaning that interest payments rise as general rates of interest increase.

Thames is partly owned by state entities from China and Abu Dhabi, and Ofwat seems to have had no success in securing prudent conduct from its foreign shareholders. Thames Water has a debt ratio of around 80 percent, against the Ofwat recommendation of 60 percent. Auditors PricewaterhouseCoopers routinely gave the company a clean bill of health even though it lacked financial resilience. As the Bank of England increased interest rates, Thames found that it could not make the minimalist required investment and service its debt.

The distress at Thames Water is due to the failure of privatization, profiteering, financial engineering, and customer exploitation. Auditors have been silent. The City of London didn’t care much, and Ofwat has done little to check predatory practices. Interestingly, Cathryn Ross, the current joint chief executive of Thames, is a former head of Ofwat. Its director of regulatory policy and investigations and director of regulatory strategy and innovation are also former Ofwat executives.
Ending the Scandal

There is public clamor for the renationalization of water. However, the Conservative government is unlikely to do that. In 2020, during his campaign to become leader of the Labour Party, Keir Starmer promised to bring the water industry into public ownership but has since reneged. Leaked emails suggest that Labour leadership and water companies have secretly been discussing the possibility of forming “social purpose” companies that would stay in private hands but give greater weight to the needs of customers, staff, and the environment.

Section 172 of the Companies Act 2006 requires company directors to have regard for the interests of “employees,” ‘‘customers,” and “the community and the environment” in making decisions. Water company directors have shown little regard for that duty. The woolly concept of “social purpose” is unlikely to curb rapacious practices.

The toxic influence of shareholders and the dash for maximum returns needs to be checked by public ownership and customer empowerment. Water company shares would be practically worthless if environmental and customer protection standards were to be rigorously enforced. In the event of default, secured creditors are unlikely to get much, and the government can buy the assets cheaply. The cost can be funded by issuing public bonds to local people with the inducement that in addition to interest payments, bondholders will get discounts on their water bills. In addition, customers should be empowered to vote on executive pay. That will ensure that executives face public scrutiny and will not be rewarded for abusive practices.


CONTRIBUTOR
Prem Sikka is an emeritus professor of accounting at the University of Essex and the University of Sheffield, a Labour member of the House of Lords, and a contributing editor at Left Food Forward.


P3 PUBLIC PENSIONS FUND PRIVATIZATION
OMERS THE ONTARIO MUNICIPAL EMPOYEES PENSION FUND OWNS 30% OF THAMES WATER